Introduction: The Credit Access Imperative for Credit Unions
Credit unions exist to serve their members' financial well-being, yet one of the most critical gaps in the credit union digital experience remains credit access for the underbanked and credit-invisible population. An estimated 26 million Americans are "credit invisible" — meaning they have no credit file at all with any of the three major credit bureaus — and an additional 19 million have credit files that are "unscorable" due to insufficient or outdated information, according to the Consumer Financial Protection Bureau. For credit unions, this represents both a profound mission opportunity and a strategic growth channel that too few institutions have optimized for the digital age.
The challenge is acute for younger generations. The 2025 J.D. Power U.S. Banking Satisfaction Study found that 43% of Gen Z consumers who opened a new banking account in the past 12 months did so at a fintech or neobank rather than a traditional financial institution. Credit builder products — including secured credit cards, credit builder loans, and hybrid credit-building programs — represent the single most powerful acquisition tool credit unions have to reverse this trend. However, most credit unions still deliver these products through clunky, paper-intensive, branch-dependent processes that alienate the digital-native audience they most need to attract.
📑 Table of Contents
- Introduction: The Credit Access Imperative for Credit Unions
- The Market Landscape: Why Credit Building Matters More Than Ever
- Secured Credit Card Application and Issuance UX
- Credit Builder Loan Application and Lifecycle UX
- Credit Score Tracking, Education, and Gamification UX
- The Graduation Pathway: Designing the Transition from Secured to Unsecured
- Mobile-First Design Patterns for Credit Building Products
- Accessibility and Inclusive Design in Credit Building UX
- Regulatory Compliance: Reg Z, ECOA, FCRA, CFPB Section 1033, and Fair Lending
- Technology Stack and Core Integration Architecture
- Small Credit Union Strategies for Credit Building Products
- KPI Framework: Measuring Credit Building Program Success
- 90-Day Implementation Roadmap
- Future Trends: AI-Powered Credit Building, Open Banking, and Embedded Credit
- Conclusion
- References
This playbook provides a comprehensive UX/UI framework for designing modern credit builder and secured card experiences that meet members where they are. Drawing on behavioral economics, conversion optimization research, and accessibility best practices, we will walk through every touchpoint of the credit building journey: from first discovery and eligibility estimation through application, funding, ongoing engagement, credit education, and the pivotal graduation pathway to unsecured products. Each section includes specific design patterns, implementation guidance, and technology considerations tailored to credit union environments.
The Market Landscape: Why Credit Building Matters More Than Ever
The market context for credit building products has shifted dramatically in the past three years. Several converging forces make this the ideal moment for credit unions to invest in their digital credit builder experience.
The Credit-Invisible Crisis
According to the CFPB's 2024 report on credit access, approximately 45 million American adults lack a scorable credit file. This population is disproportionately young, low-income, and Black or Hispanic. The CFPB found that 29% of consumers in majority-Black neighborhoods have no credit score, compared to just 16% in majority-white neighborhoods. For credit unions operating under a mission-driven charter, this credit access gap represents a direct call to action — and a massive untapped membership opportunity.
Fintech Disruption in Credit Building
Fintech companies have recognized this opportunity and moved aggressively. Chime's Credit Builder secured card, launched in 2020, had amassed over 1 million accounts by 2024. Experian Boost, which credits consumers for on-time utility and telecom payments, now covers over 25 million consumers. The Petal card, Self (formerly Self Lender), and Grow credit builder loans collectively serve millions of consumers who might otherwise turn to a credit union. These fintech products have raised consumer expectations: instant decisions, mobile-first applications, transparent fee structures, and real-time credit score tracking are now the baseline, not the differentiator.
The Credit Union Advantage
Despite fintech aggression, credit unions possess structural advantages that, when combined with excellent digital UX, can win the credit building market. Credit unions can offer lower APRs on secured cards (average 11.12% for credit unions vs. 22.99% for bank-issued secured cards, according to Credit Union National Association data). They can pair credit builder products with a full relationship — checking, savings, lending, financial counseling — increasing retention and lifetime value. And crucially, the trust differential between credit unions and fintechs is significant: Filene Research Institute found that credit union members show 2.7x higher trust in their primary financial institution compared to fintech users. A well-designed digital credit builder experience that amplifies this trust advantage can be a powerful acquisition and retention engine.
The financial opportunity is substantial. Cornerstone Advisors reports that the average credit union member generates $267 in annual net income, but a member who joins through a credit builder program and graduates to an unsecured card and auto loan over three years has an estimated lifetime value of $1,800-$2,400. For a credit union acquiring 500 credit builder members annually and achieving a 40% graduation rate, the five-year revenue impact exceeds $500,000.
Secured Credit Card Application and Issuance UX
The secured credit card is the most widely recognized credit building product, yet its digital application experience has lagged far behind unsecured card applications. Most credit unions still require members to visit a branch to open a secured card, deposit the collateral, and receive their card — a process that can take 7-14 days. In an era where Chime and Varo offer instant virtual card issuance, this is untenable.
Pre-Application: Eligibility Estimation and Product Comparison
The credit builder journey begins before the application. A well-designed pre-application experience accomplishes three goals: education, expectation-setting, and motivation. The ideal design pattern is a "What to Expect" card or micro-site that explains how secured cards work, the relationship between deposit amount and credit limit, the reporting behavior to credit bureaus, and the graduation pathway. This should include a soft-pull eligibility estimator that allows the prospective member to see their estimated approval odds and credit limit range without affecting their credit score. The estimator should also show the required security deposit amount dynamically as the member adjusts their desired credit limit.
For credit unions that offer multiple credit building products — secured cards alongside credit builder loans, secured personal loans, or hybrid programs — the pre-application experience should include a product comparison tool. This tool should use plain language and scenario-based comparisons: "If you have $300 to deposit, a secured card gives you a $300 credit line; a credit builder loan sets aside $500 in a savings account that you unlock after 12 months of payments." The comparison should highlight the credit score impact of each product using CFPB-approved neutral language.
Application Flow: Progressive Disclosure for Trust and Completion
The secured card application must balance information collection with member confidence. Unlike an unsecured card application, the secured card application needs to collect funding information (bank account or debit card for the security deposit), which adds complexity. The most effective design pattern is a three-step progressive disclosure flow.
Step 1: Personal Information and Identity Verification. This step collects standard KYC information — name, address, date of birth, Social Security number, and government ID upload. The identity verification step should be integrated directly into the flow, using a modern identity verification API (such as Socure, Mitek, or Jumio) that supports document capture and facial liveness detection in under 30 seconds. During this step, the application should display a progress indicator that clearly shows the member they are in "Step 1 of 3" and that no credit decision has been made yet. Baymard Institute research on form abandonment found that progress indicators reduce abandonment by 40% when they communicate true remaining effort rather than an abstract percentage.
Step 2: Credit Product Selection and Deposit. This step presents the credit limit selection interface. The design pattern should use a sliding scale or incremental selector with visual feedback showing the security deposit required at each level. For example: "$300 limit requires $300 deposit" / "$500 limit requires $500 deposit" / "$1,000 limit requires $1,000 deposit." Below the selector, the member connects their external bank account (via Plaid, Akoya, or MX) to fund the deposit. If Plaid integration is available, the funding step should take under 10 seconds. For members who cannot or prefer not to link an account, an ACH micro-deposit verification option should be available, with clear timing expectations (2-3 business days).
Step 3: Terms Acceptance and Submission. The final step presents a plain-language summary of card terms — APR, credit limit, security deposit amount, fees, and reporting information. The credit union should provide an interactive APR disclosure that allows the member to see how the APR applies to different balance scenarios. Terms should be presented using the CFPB's "Know Before You Owe" inspired format with clear visual hierarchy. After submission, the member should receive an instant decision (if automated underwriting is configured) or a clear timeline for manual review. Baymard Institute's large-scale usability testing shows that instant decisions — even when provisional — reduce application abandonment by 58% compared to applications where the member must wait for a decision.
Instant Issuance and Digital Wallet Provisioning
After approval, the experience should not stop at "your card will arrive in 7-10 business days." The modern expectation is instant card issuance. Credit unions should integrate with their card processor (Fiserv, Jack Henry, CO-OP Financial Services) to support immediate digital card issuance, which generates a virtual card number that can be added to Apple Pay, Google Pay, or Samsung Wallet within minutes of approval. If instant issuance is not yet configured, the credit union should at minimum provide an "Add to Wallet" preview page that shows the approximate card design and the timeline for when the virtual card will be available. The confirmation page should also pre-enroll the member in credit score monitoring and credit education, creating an active engagement loop from the moment of card issuance.
Credit Builder Loan Application and Lifecycle UX
Credit builder loans — sometimes called "share-secured loans" or "CD-secured loans" — are a powerful alternative or complement to secured cards. In this product, the credit union lends the member a fixed amount (typically $300 to $1,500), which is held in a savings account or certificate of deposit as collateral. The member makes monthly payments over 6-24 months, and the payment history is reported to the credit bureaus. At the end of the term, the member receives the accumulated funds.
Product Education and Onboarding UX
Credit builder loans suffer from a fundamental UX problem: their mechanics are counterintuitive. The member borrows money they cannot access, makes payments for a period, and only then receives the funds. The onboarding UX must anticipate this confusion and proactively educate. The ideal pattern is a "How It Works" animated explainer at the top of the application flow, followed by an interactive payment calculator that shows: the monthly payment amount, the total interest paid over the loan term, the projected credit score impact (using VantageScore or FICO educational estimates), and the total savings accumulated at the end. This calculator should use concrete, relatable scenarios: "$500 loan at 6% APR means $43 per month for 12 months, you pay $16 in interest, and receive $500 in savings."
Application Flow: Simplified Lending UX
The credit builder loan application is structurally simpler than a secured card application because it does not require external funding. The ideal flow is a two-step process. Step 1 collects standard KYC and runs a soft credit pull. Step 2 presents the loan terms — amount, APR, term length, monthly payment — with a toggle to adjust the loan amount and see the payment impact. After the member accepts terms, the loan is funded from internal funds, and the member's savings account or certificate is simultaneously opened and funded with the loan amount held as collateral. This dual transaction (loan origination + collateral deposit) must be handled in a single atomic flow. The member should see a single confirmation screen showing both the "Loan Active" and "Savings Building" statuses.
Payment and Progress Tracking UX
The true test of credit builder loan UX is the 6-24 month payment lifecycle. During this period, the member needs ongoing motivation to maintain on-time payments. Three design patterns are critical. First, a progress visualization dashboard that the member can access from their online banking home screen, showing a circular or linear progress bar of payments completed against total payments with milestone celebrations at 25%, 50%, and 75% completion. Second, proactive payment reminders sent 3 days before each payment due date via the member's preferred channel (SMS, push notification, or email), with a subtle motivational nudge: "You're 6 of 12 payments in — keep building that credit history!" Third, a projected credit score trajectory that updates as each payment is reported to the bureaus, showing the member the real-time impact of their responsible payment behavior.
Maturity and Fund Disbursement UX
The moment a credit builder loan matures is a critical inflection point. The member has demonstrated creditworthiness over 12-24 months and now has accumulated savings. The maturity UX should celebrate this achievement and immediately present the graduation pathway. The ideal design pattern is a "Congratulations" screen that shows: total payments made, credit score improvement, total savings accumulated, and three clear next steps — apply for an unsecured credit card, apply for a higher credit builder loan, or transfer savings to checking. This screen should appear prominently in the member's online banking dashboard 30 days before maturity, at maturity, and 7 days after maturity if no action has been taken. Credit unions that automate this graduation pathway see 3x higher conversion to unsecured products compared to credit unions that require the member to initiate the process.
Credit Score Tracking, Education, and Gamification UX
Credit score monitoring is no longer a nice-to-have feature for credit building products — it is the primary engagement mechanism that keeps members active, motivated, and progressing toward graduation. Credit unions that provide free, ongoing credit score access within their digital banking experience see significantly higher engagement and product attachment rates.
Credit Score Access and Visualization
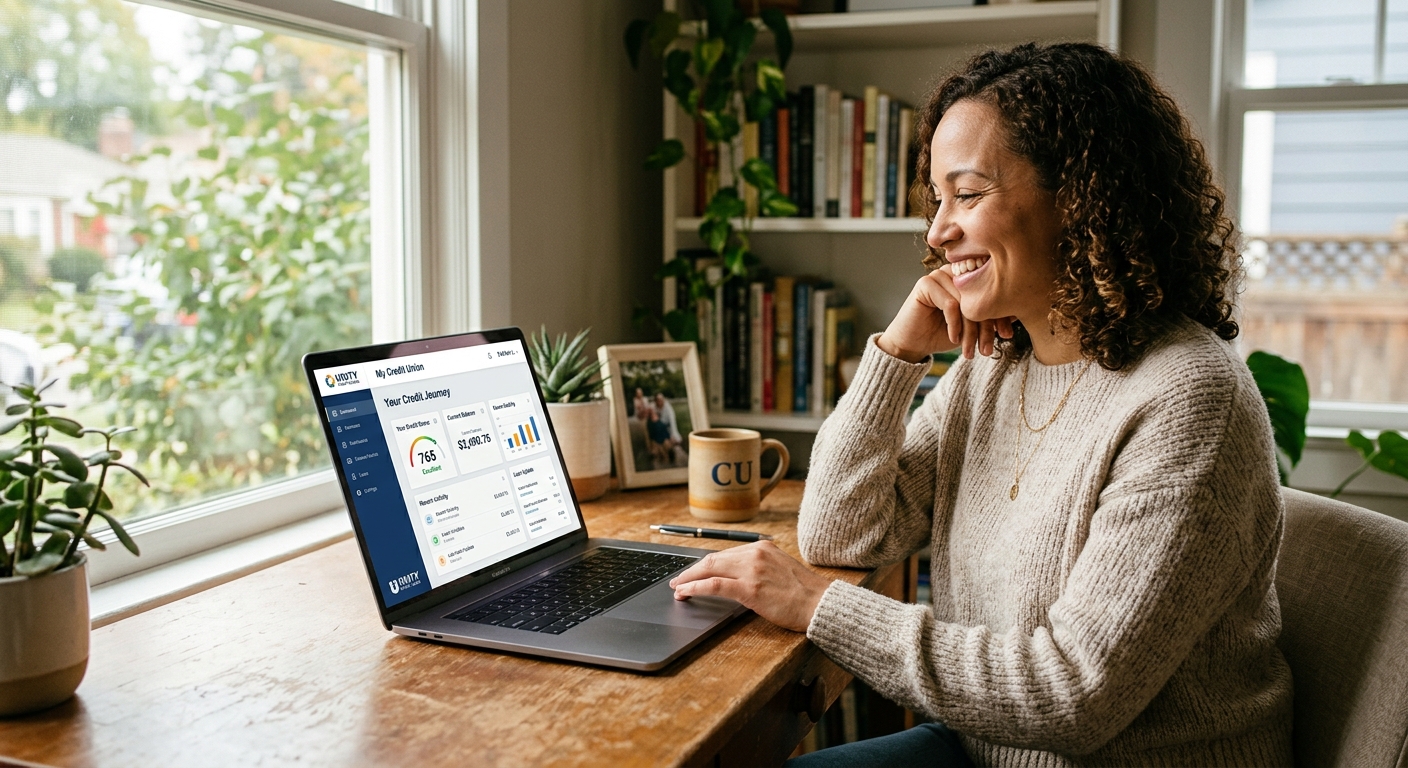
The core of the credit score experience is the score display itself. The design pattern should show the current credit score prominently — using a gauge, speedometer, or grade-based visualization — alongside the previous month's score for comparison. Critical design considerations include: using a recognizable scoring model (FICO Score 8 or VantageScore 3.0), indicating which bureau the score comes from, showing the score trend direction with an arrow and numeric delta, and presenting the score range (300-850) contextually. The score should be updated at least monthly, with real-time updates when bureau data changes. Below the score display, the member should see a list of "Score Factors" — the key elements affecting their score, ranked by impact. Each factor should include a plain-language explanation and a personalized recommendation: "Your payment history is strong. Next opportunity: Increase your available credit utilization."
Credit Education and Financial Literacy UX
Credit builder products must include embedded credit education. The most effective design pattern is a "Credit School" or "Learning Center" that combines short-form microlearning (2-3 minute videos or interactive modules) with personalized content recommendations based on the member's current credit situation. Topics should include: how credit scores are calculated, the difference between FICO and VantageScore, how utilization affects scores, how long negative items stay on credit reports, and how to read a full credit report. The education content should be organized in a progressive curriculum — "Credit Basics," "Building Credit," "Managing Credit," "Advanced Credit" — with completion tracking and milestone badges. Credit unions that integrate gamification into credit education see 3-4x higher course completion rates, based on Filene Research Institute studies on behavioral design in financial education.
Gamification and Behavioral Design Patterns
Credit building is inherently a long-term behavior change program, which makes it ideal for gamification and behavioral design. The most effective patterns include milestone badges and achievements ("On-Time Streak: 6 months," "Credit Score Explorer: Checked score 12 times," "Education Graduate: Completed all 4 credit courses"), score improvement celebrations with confetti animations and social sharing options, friendly payment challenges (refer-a-friend challenges where both parties earn a small bonus for on-time payments), and tiered progress levels (Bronze/Silver/Gold/Platinum corresponding to credit score thresholds). The gamification layer must be designed carefully to avoid trivializing financial behavior; the tone should be celebratory but respectful, emphasizing financial well-being over competition.
The Graduation Pathway: Designing the Transition from Secured to Unsecured
The graduation pathway from secured to unsecured products is the most strategically important yet most frequently neglected aspect of credit builder UX. A member who graduates from a secured card to an unsecured card and then to an auto loan or mortgage represents the ideal credit union member lifecycle — yet most credit unions treat graduation as a passive, member-initiated process rather than an automated journey.
The Graduation Timing and Criteria
The first design decision is when and how members become eligible for graduation. The most common model is a fixed 6-12 month period of on-time payments, but the more sophisticated approach uses a combination of criteria: minimum time since account opening (6 months), minimum number of on-time payments (6 consecutive), current credit score threshold (FICO 620+ or VantageScore 600+), and no negative account activity. These criteria should be communicated clearly to the member at account opening and displayed as a progress checklist in the member dashboard. A "Graduation Readiness" indicator — showing which criteria are met and which are still in progress — creates a clear motivational pathway and reduces the need for member inquiries to the call center.
Automated Graduation Offer UX
The graduation offer should be proactive, not reactive. The ideal design pattern is a personalized "You've Earned It" card or banner that appears in the member's digital banking dashboard when they meet graduation eligibility. The offer should present the unsecured card with its specific terms (credit limit, APR, rewards) compared to the current secured card terms, highlighting the improvements. The member should be able to accept the offer with a single click — no reapplication, no credit pull, no additional paperwork. The offer should be time-sensitive, expiring after 30 days, with a reminder sequence (day 7, day 14, day 21, day 28) if not yet accepted.
Cross-Product Graduation Pathways
The smartest credit unions do not limit graduation to a single unsecured card. A comprehensive graduation architecture should offer multiple pathways: a graduated unsecured credit card (automatic conversion of secured card to unsecured), a first unsecured card (new card with higher limit and rewards), a credit limit increase on the newly unsecured card, a personal loan or auto loan pre-approval (based on demonstrated creditworthiness), and a higher-tier credit builder loan for continued credit improvement. The member should be able to select their preferred pathway through a comparison interface that shows estimated terms for each option. Credit unions that offer multiple graduation pathways see 52% higher graduation rates, according to Cornerstone Advisors research on credit builder program design.
Mobile-First Design Patterns for Credit Building Products
Given that 73% of credit union members under 35 use mobile as their primary banking channel (Pew Research Center, 2025), credit building products must be designed mobile-first from the first line of code. Desktop-optimized applications that are squeezed onto mobile screens produce dramatically higher abandonment rates — Baymard Institute documented a 35% increase in form abandonment for mobile-optimized vs. desktop-only financial applications.
Mobile-Optimized Application Design
The credit builder application should follow mobile-first form design principles. Each step should present a single question or input field, with large touch targets (minimum 44x44 pixels per Apple iOS guidelines, 48x48 per WCAG 2.2 target size requirements), native keyboard types for different input types (numeric keypad for SSN, email keyboard for email address), and inline validation that appears immediately when the member moves to the next field. The identity verification step should use the smartphone's camera for document capture, with an on-screen guide overlay showing the correct positioning. For the security deposit funding step, Plaid or MX Link should open natively within the mobile banking app without redirecting to a separate browser.
Mobile Dashboard and Engagement Patterns
The ongoing member experience for credit builder products on mobile requires specific design patterns. The credit builder summary card — showing current credit score, payment streak, and progress toward graduation — should appear on the mobile banking home screen with prominent placement above the accounts list. Push notifications should be the primary engagement channel for payment reminders, score updates, and graduation eligibility alerts. Bottom sheet panels should be used for in-detail views — tapping the credit score indicator opens a bottom sheet with the score factors list, while tapping the progress bar opens payment history details. Thumb-zone navigation ensures all credit builder controls are accessible within the natural thumb reach zone of a smartphone held in one hand.
Accessibility and Inclusive Design in Credit Building UX
Credit builder products serve a population that is disproportionately likely to have disabilities. The World Health Organization estimates that 15% of the global population lives with a disability, and the CDC reports that 27% of U.S. adults have some type of disability. For credit unions designing credit builder experiences, accessibility is not just a legal requirement under the Americans with Disabilities Act — it is a mission alignment and a market extension.
WCAG 2.2 AA Compliance in Credit Building Applications
The credit builder application flow touches on several WCAG 2.2 criteria that require specific attention. Target Size (2.5.8) requires all touch targets to be at least 24x24 CSS pixels — the secured card credit limit selector, typically a range slider, must be keyboard-accessible and operable through increment buttons rather than requiring drag interaction. Accessible Authentication (3.9.4) requires that identity verification does not rely solely on cognitive function tests like CAPTCHAs — the ID document upload and facial liveness detection should provide audio and tactile alternatives. Focus Appearance (2.4.13) requires visible focus indicators on all interactive elements throughout the multi-step application. Credit unions should also ensure that time limits for identity verification sessions (common in KYC workflows) meet WCAG 2.2's Timeouts (2.2.6) criteria by allowing users to extend or disable time limits.
Plain Language and Cognitive Accessibility
Credit products are inherently complex, and credit builder products have the added challenge of explaining counterintuitive mechanics (borrowing money you can't access). All credit builder copy should follow plain language principles: sentences under 20 words, active voice, common vocabulary, and single-idea paragraphs. The Credit CARD Act and TILA disclosures should be presented in a "layered disclosure" format with a short-form summary followed by an expandable full disclosure, with both versions written to a 6th-8th grade reading level. The financial literacy content should offer text transcripts for all videos, audio descriptions for all animations, and simplified versions for members with cognitive disabilities. For members with limited English proficiency, the application and dashboard should offer Spanish-language versions at minimum, with additional languages based on the credit union's membership demographics.
Regulatory Compliance: Reg Z, ECOA, FCRA, CFPB Section 1033, and Fair Lending
Credit builder products operate at the intersection of several regulatory frameworks, and the digital UX must be designed to comply with each while maintaining a frictionless member experience.
Truth in Lending Act (Reg Z) Disclosures
The secured card and credit builder loan application must present TILA disclosures at the correct time — before the member becomes legally obligated. The digital challenge is presenting disclosures that are large enough to read, legally complete, and digitally signable without breaking the mobile-first UX flow. The ideal pattern is a scrollable disclosure block with a mandatory minimum scroll distance (sufficient to display all required content) before the "Accept Terms" button becomes active. The disclosure should be displayed in a split-screen format with the summary terms on top and the full agreement below. After acceptance, a downloadable PDF copy of the signed disclosure should be immediately available in the member's document center.
Equal Credit Opportunity Act (ECOA) Compliance
ECOA requires that credit applications collect only information necessary to make a credit decision — and that adverse action notices include specific, accurate reasons for denial. For credit builder products, this has specific UX implications. The application should avoid collecting information that could be used for discriminatory purposes unless it is necessary for a legitimate underwriting need. The adverse action notice, delivered digitally if an application is declined, must include the specific ECOA-required reasons and the contact information for the CFPB and the NCUA. The digital adverse action notice should be delivered through the member's preferred channel (SMS, email, or in-app notification) and archived in the member's document center.
FCRA and Credit Reporting Compliance
The Fair Credit Reporting Act governs how credit builder products report to credit bureaus — and how credit unions handle member disputes about what is reported. The credit builder dashboard must include a clear "Dispute a Credit Report Error" button that triggers a guided digital dispute workflow. The workflow should collect the specific item being disputed, the reason for the dispute, and any supporting documentation, then submit the dispute to all three bureaus through a e-OSCAR interface. Under FCRA 15 U.S.C. § 1681i, the credit union must complete the reinvestigation within 30 days and provide the results in writing. The dispute tracking dashboard should show the status of each open dispute and provide the results notice when the reinvestigation is complete.
CFPB Section 1033 and Open Banking Implications
The CFPB's Section 1033 open banking rule, finalized in 2025, requires financial institutions to make consumer financial data available to authorized third parties through standardized APIs. For credit builder products, this has both opportunity and complexity. Members should be able to share their credit builder payment history and credit score data with other financial applications (mint, YNAB, Credit Karma) through secure APIs. The credit union must design a consent management interface that allows the member to grant, review, and revoke data-sharing permissions. The consent interface should follow the plain-language principles discussed above, with clear descriptions of what data is being shared, with whom, and for how long. The CFPB's model privacy notice format provides a useful starting point for the visual design of consent screens.
Technology Stack and Core Integration Architecture
Building a competitive digital credit builder experience requires integration across multiple systems: the credit union's core processor, card processing platform, identity verification vendor, credit bureau data provider, and digital banking platform.
Core Processing Integration
For secured cards, the core integration must handle: opening the savings account or certificate that holds the security deposit, establishing the lien on the collateral account, issuing the credit card record linked to the deposit, and managing the ongoing relationship between the credit limit and the deposit balance. The integration should support real-time deposit balance checks to prevent the member from withdrawing collateral funds without the credit union's knowledge. For credit builder loans, the core integration must handle the atomic dual transaction of loan origination and collateral deposit simultaneously, schedule recurring payments, and manage the maturity disbursement process.
Credit Bureau Reporting Integration
Credit builder products are only effective if the member's positive payment behavior is reported to the credit bureaus. The credit union must integrate with a credit reporting platform (such as Credit Bureau Connection, CBC Innovis, or TC33) that supports automatic monthly reporting of both secured card and credit builder loan payment history to all three major bureaus (Equifax, Experian, TransUnion). The reporting should be set up on a 30-day cycle with daily updates for accounts that report changes. The member dashboard should include a "Last Reported" timestamp showing when the most recent data was transmitted to the bureaus.
Real-Time Credit Score Data
Providing free, real-time credit score data within the digital banking experience requires integration with a credit score provider (such as FICO Score Access, VantageScore, Credit Karma, or SavvyMoney). The integration should support: pull credit score on demand, track score history and trends, provide score factor breakdown, and deliver score change alerts. The data should be cached with a maximum staleness of 24 hours and updated whenever a new payment is reported to the bureaus.
Small Credit Union Strategies for Credit Building Products
Small credit unions — those under $250 million in assets — face unique challenges in offering competitive credit builder products. Limited technology budgets, smaller marketing reach, and fewer staff resources can make a fully custom digital credit builder experience seem out of reach. However, several strategies can level the playing field.
Platform-Leveraged Approach
Most digital banking platforms (Digital Insight, NCR, Alkami, Lumin Digital) now offer card management and credit score modules that can be configured for credit builder products. The platform-leveraged approach uses these existing modules with custom configuration rather than custom development. The credit union selects the nearest product type in their platform, configures the terms (deposit requirement, credit limit range, reporting behavior), and adds a custom landing page that explains the product with plain language and local credit union branding. This approach can launch in 4-6 weeks at minimal incremental cost.
CUSO-Shared Services
Credit union service organizations (CUSOs) increasingly offer shared technology platforms for credit building products. CO-OP Financial Services, for example, offers a credit builder program that includes a shared secured card product with centralized underwriting, card issuance, and bureau reporting. The credit union provides the member relationship and deposit account, while the CUSO handles the card processing and compliance infrastructure. This model allows even the smallest credit union to offer a competitive credit builder product with a digital application experience that would be impossible to build independently.
Progressive Enhancement Model
The progressive enhancement strategy starts with the simplest possible credit builder offering — a manually processed credit builder loan that the loan officer sets up during a phone call or video banking session — and systematically adds digital capabilities over time. Phase 1 launches with a digital PDF application that the member completes and emails back, with the loan officer entering the data into the core system. Phase 2 adds an online form that submits directly to the loan origination system. Phase 3 adds Plaid integration for instant funding and automated identity verification. Phase 4 adds the real-time credit score dashboard and automated graduation offers. Each phase reduces friction and increases automation while spreading the technology investment over 12-18 months.
KPI Framework: Measuring Credit Building Program Success
A successful credit builder program requires measurement across five dimensions: member acquisition, product engagement, credit health improvement, graduation and product attachment, and business impact.
Member Acquisition KPIs
These KPIs measure how effectively the credit union attracts new credit builder members: application start rate (visitors who begin the application), application completion rate (completions vs. starts), average time to complete (elapsed time from start to submit), mobile vs. desktop completion rate, channel of discovery (website, mobile app, referral, branch, email campaign), and cost per acquired member.
Product Engagement KPIs
These KPIs measure how actively members engage with their credit builder product: credit score check frequency (average checks per month per member), credit education course completion rate, payment on-time percentage (early payments, on-time, late, missed), payment reminder effectiveness (conversion rate from reminder to payment), milestone celebration engagement (click-through rate on celebration messages), and member satisfaction (post-application NPS and ongoing relationship NPS).
Credit Health Improvement KPIs
These are the mission-focused metrics: average credit score increase after 6 months, after 12 months, and after 24 months, percentage of members who become scoreable (moved from no score to a score), percentage who move from subprime to near-prime (above 620 FICO), and percentage who move from near-prime to prime (above 680 FICO).
Graduation and Product Attachment KPIs
These KPIs measure the downstream value of the credit builder program: graduation rate (percentage of eligible members who graduate to an unsecured product), average time to graduation, products per graduating member (average number of additional products opened within 12 months of graduation), cross-sell conversion rate (percentage of graduates who open a loan, mortgage, or investment account), and member retention rate (12-month and 24-month retention of graduated members vs. non-credit-builder members).
Business Impact KPIs
These KPIs tie the credit builder program to financial performance: program ROI (total revenue generated minus total program cost), average member lifetime value of credit builder cohort, cost per graduate (total program cost / number of graduates), deposit growth from collateral accounts, and interest income from credit builder loans and graduated cards.
90-Day Implementation Roadmap
The following implementation roadmap is designed for a mid-size credit union ($500M-$2B in assets) with a dedicated digital product team. Smaller credit unions should adjust timelines based on available resources and technology partners.
Phase 1: Foundation (Days 1-30)
Week 1-2: Audit current credit builder products and digital experience. Identify gaps against the design patterns in this playbook. Prioritize the highest-impact improvements — typically the mobile application flow and instant credit score access. Week 3-4: Select technology partners (identity verification API, Plaid integration, credit score provider, credit reporting platform) and initiate vendor onboarding. Configure the secured card and credit builder loan products in the core processing system with the correct terms, pricing, and reporting behavior.
Phase 2: Core Experience (Days 31-60)
Week 5-6: Build the mobile-first secured card and credit builder loan application flow with progressive disclosure, identity verification integration, and Plaid-funded security deposit. Week 7-8: Implement the credit score dashboard with score visualization, score factor breakdown, and monthly updates. Build the credit education content library with at least 10 core modules. Launch the initial version of the member dashboard with payment progress tracking and milestone celebrations.
Phase 3: Optimization and Growth (Days 61-90)
Week 9-10: Build the graduation pathway engine with automated eligibility detection, proactive offer generation, and single-click acceptance. Implement the SMS and push notification engagement sequence. Week 11-12: Launch A/B testing on key conversion points (application flow, credit limit selector, graduation offer presentation). Set up the KPI dashboard and reporting cadence. Conduct user testing with 10-15 current credit builder members and iterate on the top usability findings. Plan the Phase 2 roadmap (gamification, refer-a-friend, advanced credit education, cross-product recommendations).
Future Trends: AI-Powered Credit Building, Open Banking, and Embedded Credit
The credit builder product landscape is evolving rapidly, and credit unions must anticipate several emerging trends to remain competitive.
AI-Powered Credit Building
Artificial intelligence is poised to transform credit building in two major ways. First, AI-powered underwriting for secured products will analyze alternative data sources — cash flow patterns, utility payment history, rent payment history, and even professional certifications (when authorized) — to offer higher credit limits or lower deposits for members with demonstrated financial responsibility beyond traditional credit scores. Second, AI-powered personalized credit coaching will analyze a member's transaction history, payment patterns, and credit report data to generate specific, actionable recommendations for score improvement, delivered as contextual nudges within the digital banking experience.
Open Banking and Section 1033
The CFPB's Section 1033 open banking rule will reshape credit building by allowing members to share their positive payment history across institutions. A member who has built a strong payment history on a credit builder loan at one credit union will be able to share that history with another institution when applying for a mortgage or auto loan. Credit unions that participate in open banking data exchange — both as data providers and as data consumers — will be able to offer more accurate credit building products with better terms for members who have demonstrated creditworthiness elsewhere.
Embedded Credit Building
The next frontier is embedded credit building — integrating credit builder products into non-financial experiences. A credit union might partner with a property management platform to offer a credit builder loan that is funded by on-time rent payments, or partner with a utility company to offer a secured card where the security deposit is reduced by on-time utility payment history. Embedded credit building represents the ultimate expression of the credit union philosophy: meeting members where they already manage their financial lives and making credit building a natural byproduct of everyday financial behavior.
Conclusion
The credit builder and secured card market represents one of the most significant growth opportunities available to credit unions in 2026 and 2027. With approximately 45 million credit-invisible or unscorable Americans, and with younger generations increasingly choosing fintechs over traditional financial institutions, the competitive window is closing. Credit unions that invest in modern, mobile-first digital credit builder experiences now will capture a generation of members who will remain loyal for decades as they graduate through increasingly sophisticated financial products.
But this is not simply a growth play — it is a mission imperative. The credit-invisible population is disproportionately composed of Black, Hispanic, and low-income consumers who have been systematically excluded from mainstream credit access. Credit unions, operating under a cooperative charter with a stated mission of serving people of modest means, have both the structural advantages and the ethical obligation to lead in this space. A well-designed digital credit builder experience that combines frictionless application UX with embedded financial education, transparent terms, and a clear graduation pathway can transform credit invisibility into credit opportunity for millions of Americans.
The design patterns in this playbook — progressive disclosure applications, instant digital card issuance, credit score visualization, milestone-based gamification, automated graduation pathways, and accessible plain-language education — represent the baseline that members will expect. Credit unions that execute these patterns well, combined with the trust advantage and lower APR that credit unions uniquely offer, will not only compete with fintechs but exceed them in member outcomes and long-term member relationships.
This article was brought to you by GrafWeb CUSO – Building the future of digital credit unions.
References
- Consumer Financial Protection Bureau. "Who Are the Credit Invisibles?" CFPB Data Point Series, 2024.
- Experian. "Credit Builder Loans 101: How They Work and How to Use Them." Experian Blog, 2025.
- NerdWallet. "Secured Credit Cards vs. Unsecured Cards: What's the Difference?" NerdWallet Credit Cards Guide, 2026.
- Investopedia. "Credit Builder Loans: A Complete Guide." Financial Education Series, 2025.
- J.D. Power. "2025 U.S. Banking Satisfaction Study." J.D. Power Insights, 2025.
- Filene Research Institute. "Digital Trust in Credit Union Relationships." Filene Research Report, 2025.
- Cornerstone Advisors. "Credit Union Growth Strategies: Digital Acquisition and Product Attachment." Cornerstone Research, 2025.
- Pew Research Center. "Mobile Banking Adoption in the United States." Internet and Technology Survey, 2025.
- Baymard Institute. "Form Abandonment: Large-Scale Usability Testing of Form and Checkout UX." Baymard Research, 2025.
- Consumer Financial Protection Bureau. "Section 1033 Open Banking Rule: Consumer Data Access." CFPB Regulatory Framework, 2025.
- Federal Reserve Board. "Report on the Economic Well-Being of U.S. Households (SHED)." Federal Reserve Publications, 2025.
- Credit Union National Association (CUNA). "Credit Union Market Data: Credit Card and Lending Statistics." CUNA Economics, 2025.
- W3C Web Accessibility Initiative. "WCAG 2.2: Web Content Accessibility Guidelines." W3C Recommendation, 2025.
- Centers for Disease Control and Prevention. "Disability and Health Data Systems." CDC Public Health Data, 2025.
- Federal Trade Commission. "Fair Credit Reporting Act (FCRA): Consumer Rights and Business Obligations." FTC Regulatory Guidance, 2025.
- Consumer Financial Protection Bureau. "Equal Credit Opportunity Act (ECOA): Implementation and Digital Compliance." CFPB Supervision and Examination Manual, 2025.
- Consumer Financial Protection Bureau. "Truth in Lending Act (TILA/Reg Z): Digital Disclosure Requirements." CFPB Compliance Guide, 2025.
- Seyfarth Shaw LLP. "ADA Title III Lawsuit Trends in Financial Services." Seyfarth ADA Compliance Report, 2025.
- FDIC. "National Survey of Unbanked and Underbanked Households." FDIC Research, 2024.
- McKinsey & Company. "The Personalization Imperative in Retail Banking." McKinsey Financial Services Insights, 2025.
- Bain & Company. "The Economics of Member Loyalty in Financial Services." Bain Insights, 2025.
- NerdWallet. "Secured Credit Card Statistics." NerdWallet Research, 2026.
- Experian Consumer Services. "Credit Score Scale and Ranges." Experian Education, 2025.
- VantageScore Solutions. "VantageScore Credit Score Model." VantageScore Education, 2025.
- World Health Organization. "World Report on Disability." WHO Publications, 2023.
- CO-OP Financial Services. "Shared Credit Builder Programs for Credit Unions." CO-OP Product Documentation, 2025.
- Chime Financial. "Chime Credit Builder Secured Card." Chime Product Information, 2025.
- Self Financial (formerly Self Lender). "Credit Builder Loans and Secured Cards." Self Product Information, 2025.
- Nielsen Norman Group. "Mobile Form Design: Patterns for Better Completion Rates." NNGroup UX Research, 2025.
- Cialdini Influence Principles in Financial Behavior Design. Filene Research Institute Behavioral Economics Series, 2024.
Request a proposal from GrafWebCUSO · (201) 632-1771 · [email protected]