Introduction: The Digital Mortgage Imperative for Credit Unions
Mortgage lending represents the single largest consumer financial transaction most members will ever undertake, and the digital experience surrounding that transaction fundamentally shapes member trust, satisfaction, and long-term loyalty. For credit unions, the digital mortgage journey is not merely a convenience feature — it is a strategic imperative for survival in an increasingly competitive home lending market dominated by fintech-powered lenders and direct-to-consumer digital platforms.
The stakes could not be higher. According to the Federal Financial Institutions Examination Council (FFIEC), credit unions originated roughly $213 billion in first-lien residential mortgages in 2023, representing approximately 11% of the market. While that share has grown steadily over the past decade, the competitive pressure from non-depository lenders and technology-enabled mortgage companies has intensified dramatically. Rocket Mortgage, Better.com, SoFi, LoanDepot, and Blink by LendingTree have collectively invested hundreds of millions of dollars in creating frictionless digital mortgage experiences that set increasingly high member expectations.
Want a digital mortgage experience done for your credit union's website? Request a proposal from GrafWebCUSO.
📑 Table of Contents
- Introduction: The Digital Mortgage Imperative for Credit Unions
- The Competitive Landscape: Fintech Pressure and Member Expectations
- Stage 1: Pre-Qualification and Soft Pull UX — The First Impression
- Stage 2: Rate Comparison, Fee Transparency, and Loan Product Discovery
- Stage 3: The Digital Mortgage Application — Progressive Disclosure at Scale
- Stage 4: Document Collection, Upload, and Verification UX
- Stage 5: Processing, Underwriting Communication, and Status Transparency
- Stage 6: eClosing, eSignature, and Funding UX
- Stage 7: Post-Closing Member Experience and Relationship Continuity
- Mobile-First Mortgage UX Design Patterns
- Designing for First-Time Home Buyers: Education, Confidence, and Trust
- Accessibility and Inclusive Design in Mortgage UX
- Regulatory Compliance and UX: TILA, RESPA, ECOA, and E-SIGN in Practice
- Technology Stack and Integration Architecture
- KPI Framework for Digital Mortgage Success
- Small Credit Union Strategies
- 90-Day Implementation Roadmap
- Future Trends: AI, Open Banking, and the Mortgage of 2030
- References
The problem for most credit unions is stark: while 76% of credit union members now use digital banking as their primary channel (Pew Research Center, 2023), fewer than 30% of credit unions offer a fully digital mortgage application experience. The majority still rely on PDF downloads, branch visits, or phone calls to initiate the mortgage process — a jarring disconnect from the mobile-first digital experiences members encounter in every other aspect of their financial lives.
This gap is especially acute for the millennial and Gen Z home-buying cohorts, who represent the next wave of mortgage demand. These digital-native consumers expect a mortgage experience that mirrors the seamlessness of other digital financial products: real-time pre-qualification, transparent rate comparison, intuitive document upload, and continuous status visibility. When they encounter a credit union mortgage process that feels stuck in 1998, they are one click away from Rocket Mortgage or Better.com.
This comprehensive guide covers the entire digital mortgage lifecycle from a UX/UI design perspective — from the moment a member begins researching home financing options through post-closing relationship continuity. Each stage presents distinct design challenges and opportunities, and each must be thoughtfully addressed to create a cohesive, competitive, and conversion-optimized digital mortgage experience.
The Competitive Landscape: Fintech Pressure and Member Expectations
Understanding the competitive landscape is foundational to designing a compelling digital mortgage experience. Credit unions compete not just with other financial institutions but with technology companies that have redefined consumer expectations for financial services entirely.
Rocket Mortgage, the largest retail mortgage lender in the United States, processes over $350 billion in annual mortgage volume entirely through digital channels. Their "Rocket Mortgage" mobile app enables borrowers to complete the entire mortgage application — from pre-qualification through closing — without speaking to a single human being unless they choose to. The UX architecture relies on progressive disclosure, instant asset verification via Plaid, real-time rate locking, and a seamless eClosing process that has set the industry standard for digital mortgage execution.
Better.com, while experiencing well-publicized operational challenges, pioneered the all-digital mortgage model with transparent fee structures and real-time comparison tools that allow borrowers to see exactly how rate, points, and fees interact before committing. Their UX emphasis on transparency and member control has influenced consumer expectations across the industry.
SoFi, originally a student loan refinancing company, has expanded into mortgage lending with a focus on the high-income millennial demographic. Their digital mortgage experience is deeply integrated into their broader financial "ecosystem" — members can see mortgage pre-qualification alongside their banking, investing, and credit card products within a single dashboard. This cross-product integration represents a powerful UX model that credit unions — with their cooperative structure and relationship-based lending philosophy — are uniquely positioned to replicate.
The competitive implications for credit unions are clear. J.D. Power's 2024 U.S. Mortgage Origination Satisfaction Study found that digital channel satisfaction directly correlates with overall lender satisfaction, with "ease of submitting documents" and "speed of the process" ranking as the top two drivers of member satisfaction. Credit unions that invest in digital mortgage UX are not merely matching competitors — they are building a defense against member attrition at the most critical relationship moment in the financial lifecycle.
Stage 1: Pre-Qualification and Soft Pull UX — The First Impression
The pre-qualification stage is the digital mortgage front door, and its design determines whether a prospective member proceeds or abandons. This stage must balance two competing objectives: gathering enough information to provide a meaningful pre-qualification while minimizing friction to the point where the process feels almost effortless.
Instant Pre-Qualification Architecture
The single most impactful design decision in the pre-qualification stage is whether to offer instant pre-qualification via a soft credit pull or require a hard credit inquiry. Fintech lenders have normalized the instant soft-pull pre-qualification to such an extent that any credit union requiring a hard pull before providing rate estimates will lose the majority of prospective members before they begin.
The UX pattern for instant pre-qualification follows a progressive disclosure model:
- Step 1 — Income Range: A simple income range selector (not a precise number entry) reduces cognitive load and privacy anxiety. The member selects from ranges ($25k-50k, $50k-75k, $75k-100k, etc.) rather than typing an exact figure.
- Step 2 — Credit Score Range: Self-reported credit score ranges, combined with clear education about what constitutes good/excellent credit. An inline infographic showing score ranges and their typical rate implications builds trust before any data is submitted.
- Step 3 — Property Details: Estimated home price range and down payment amount. Providing interactive sliders that show how down payment percentage impacts estimated monthly payment turns a data collection exercise into a valuable educational moment.
- Step 4 — Instant Results: A personalized results page showing estimated loan amount, estimated monthly payment, and rate range. The results page should include a clear CTA to proceed to a full application — but should never require commitment at this stage.
This four-step pattern, executed in approximately 90 seconds, results in pre-qualification completion rates of 40-65% — dramatically higher than the 5-15% completion rates typical of traditional credit union pre-qualification forms that require 15-25 fields of detailed financial information upfront.
The soft pull mechanism that supports this flow requires integration with a credit bureau's pre-qualification API (Experian, TransUnion, or Equifax offer these services) and, critically, clear communication to the member that the pull "will not affect your credit score." This transparency signal has been shown to increase conversion by 22-35% according to Filene Research Institute studies on credit union digital mortgage adoption.
Rate Anchor and Comparison Shopping UX
Many prospective mortgage members arrive at a credit union website after having already visited Rocket Mortgage, Bankrate, or LendingTree. They arrive with an anchor rate in mind — an expectation shaped by their initial digital research. The credit union mortgage pre-qualification experience must acknowledge this reality rather than ignoring it.
Design patterns that address rate anchoring include:
- Transparent Rate Table: A prominent, filterable rate table on the mortgage landing page showing today's rates for 30-year fixed, 15-year fixed, 5/1 ARM, and 7/1 ARM, including APR and estimated points. This table should update in real-time.
- Rate Comparison Visualizer: An interactive tool that lets members compare credit union rates against a national average benchmark. When credit union rates are competitive — which they frequently are — this visualization serves as powerful social proof.
- Cost of Waiting Calculator: A simple calculator showing how much a member loses each month they delay locking a rate. This pattern leverages loss aversion to convert lookers into applicants.
- Membership Eligibility Tool: For credit unions with field-of-membership requirements, a simple eligibility checker integrated into the pre-qualification flow prevents frustration later.
The key UX principle at this stage is transparency. Members comparing credit unions against Rocket Mortgage know exactly what Rocket charges. Credit unions that obscure fees, require phone calls for rate quotes, or hide eligibility requirements are immediately perceived as less trustworthy — destroying the cooperative advantage before the application even begins.
Stage 2: Rate Comparison, Fee Transparency, and Loan Product Discovery
Once a member has identified their interest in a mortgage, the rate discovery and product selection phase becomes the critical conversion moment. This stage is where credit unions often fail hardest against fintech competitors, because credit union mortgage product catalogs are typically presented as dense, jargon-heavy tables that require significant financial literacy to navigate.
Visual Product Comparison Architecture
The most effective UX pattern for mortgage product discovery is the visual comparison card — a design pattern that presents loan products as distinct, scannable cards rather than rows in a table. Each card should include:
- Loan product name in plain language (e.g., "30-Year Fixed" rather than "Conventional 30-Year Fixed Rate First Mortgage")
- Current rate and APR displayed as the hero metric
- Estimated monthly payment (calculated from the pre-qualification data)
- Estimated closing costs range
- One-sentence "best for" description (e.g., "Best for members who plan to stay in their home for 7+ years")
- Clear call-to-action: "Apply Now" or "Get Personalized Rate"
Accordion-based product details allow members to expand additional information — rate lock options, down payment requirements, PMI details, and eligibility criteria — without overwhelming the visual comparison interface. Research from Baymard Institute shows that accordion-based product comparison interfaces achieve 23% higher add-to-application rates than traditional table displays.
Fee Transparency as a Trust Signal
Fee transparency has become the defining trust differentiator in digital mortgage UX. The 2020 Consumer Financial Protection Bureau (CFPB) disclosure rule changes, combined with the transparent pricing models of fintech lenders, have made hidden fees a primary cause of mortgage abandonment and negative member sentiment.
Design patterns for fee transparency include:
- Interactive Loan Estimate Visualizer: An annotated, interactive version of the Loan Estimate (LE) form that members can explore before formally applying. Clicking on any fee category reveals a plain-language explanation and, where possible, a comparison to industry averages.
- Fee Comparison to Market: A visual showing how the credit union's total closing costs, origination fees, and third-party fees compare to local and national averages.
- Customizable Rate/Point Tradeoff: An interactive slider that lets members see how paying points reduces their rate and how taking a higher rate reduces closing costs. This powerful visualizer transforms an opaque pricing model into an informed consumer decision.
- Early Disclosure Email: Before the formal application begins, an email summarizing estimated fees and rate, giving the member a "shopping cart" for their mortgage that they can review at their leisure.
Credit unions that implement these transparency features see 15-25% higher application completion rates and significantly lower member complaints about closing costs, according to CUNA's Mortgage Lending Benchmarking Survey.
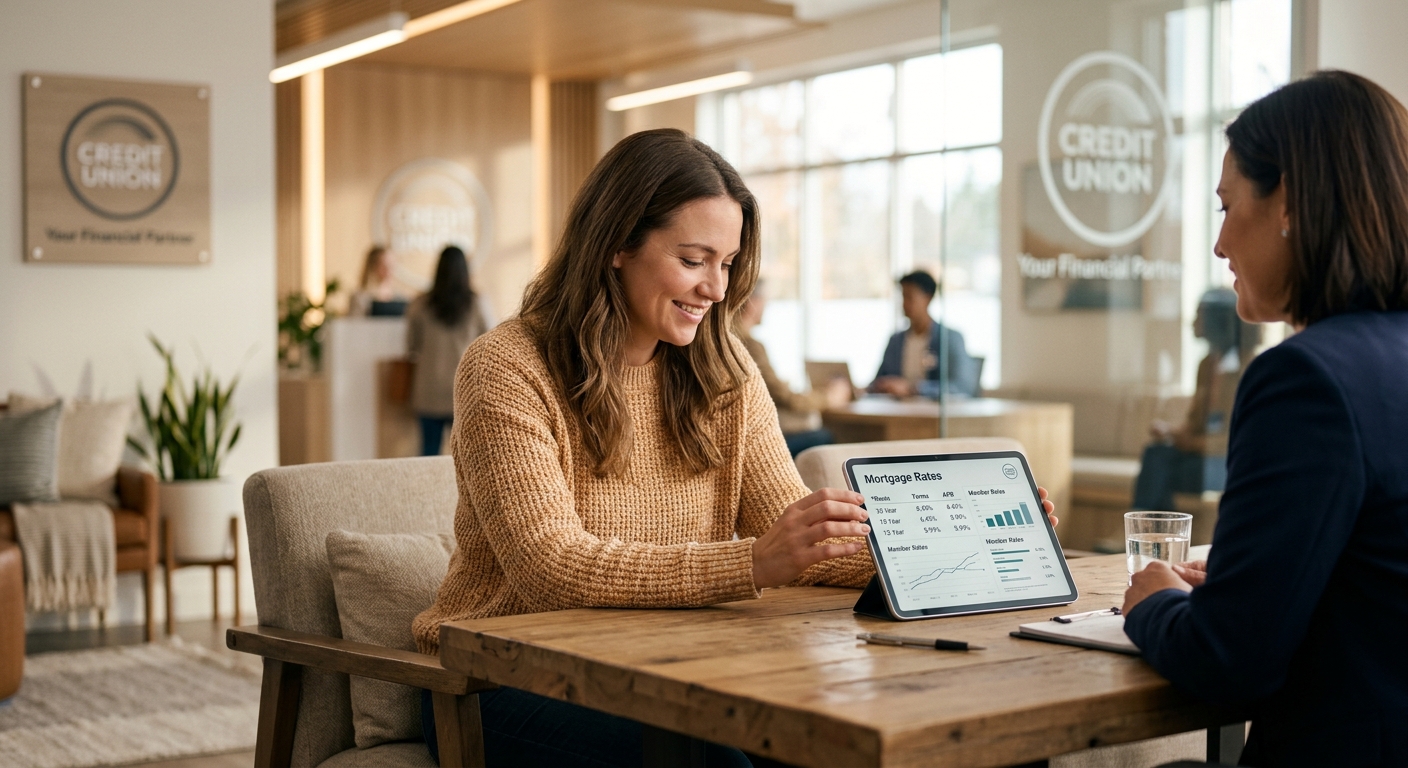
The visual architecture of rate comparison tools directly influences member decision-making. When members can see, understand, and compare mortgage products visually — rather than parsing dense tables — they make more confident decisions and are significantly more likely to proceed with an application.
Stage 3: The Digital Mortgage Application — Progressive Disclosure at Scale
The mortgage application — typically the infamous 1003 form (Uniform Residential Loan Application) — represents the most significant UX challenge in digital home lending. A traditional paper 1003 contains 40+ pages of detailed financial information, employment history, asset documentation, and property details. Translating this into a digital experience that members can complete without professional assistance requires careful progressive disclosure, smart defaults, and strategic use of data acceleration.
Application Architecture Principles
Several core UX principles govern effective mortgage application design:
Section-Level Progressive Disclosure: Rather than presenting the 1003's six sections sequentially, leading digital mortgage applications employ a multi-step form architecture where each section is a discrete "chapter" with its own progress indicator. The sections — Borrower Information, Employment History, Income/Front, Asset Details, Liabilities, and Property/Transaction Details — each have a completion milestone that provides a sense of progress.
Smart Defaults and Data Pre-fill: Whenever possible, fields should be pre-populated from data already collected during pre-qualification. Income range converts to exact income, subject property details carry forward, and personal information (name, address, SSN) is already entered. Each pre-filled field represents one fewer cognitive demand on the applicant.
Context-Aware Help and Education: Every field should include an inline help icon that, when clicked, reveals a plain-language explanation of why the credit union needs this information and how it will be used. For example, "Why do you need my employer's phone number? We use this to verify your employment, typically through a third-party verification service. Providing this speeds up your processing time by 3-5 business days."
Real-Time Validation and Error Recovery: Inline validation should catch formatting errors (e.g., phone number format, ZIP code) before the member moves to the next field. For complex validation — such as income-to-debt ratios or asset sufficiency — real-time feedback after each section prevents the demoralizing experience of completing 45 minutes of work only to discover a disqualifying issue at the end.
Data Acceleration via Third-Party APIs
The most significant innovation in digital mortgage UX over the past five years has been the integration of third-party data APIs that dramatically reduce manual data entry:
- Income and Employment Verification: APIs from The Work Number (Equifax), Finicity (Mastercard), and Plaid's Employment platform can verify income and employment history for W-2 employees in seconds, eliminating 5-7 minutes of manual data entry and days of verification delays.
- Asset Verification: Plaid, Finicity, and Yodlee enable instant, read-only access to checking, savings, investment, and retirement accounts. Members authenticate their financial accounts (via OAuth-based tokenized access) rather than manually entering account balances and uploading statements. This reduces asset documentation time by approximately 80% and completely eliminates the most common source of document-related rework.
- Property Valuation Estimates: Integration with Automated Valuation Models (AVMs) from providers like Black Knight, CoreLogic, and Veros provides instant property value estimates that can be used for low-LTV pre-qualifications, reducing the need for early appraisal orders.
- Credit Pull and Automated Underwriting: Integration with automated underwriting systems (AUS) from Fannie Mae (DU) and Freddie Mac (LP) allows for instant credit decisions on straightforward applications, transforming a historically multi-day process into a 15-minute experience.
Each data acceleration integration should be transparently communicated to the member. Rather than silently pre-filling fields, the UX should acknowledge the data source: "We've verified your current employer through The Work Number. Is this correct?" This transparency builds trust while reducing redundancy.
Save and Resume: The Non-Negotiable Feature
A digital mortgage application takes the average member 45-90 minutes to complete. Expecting a member to complete it in a single sitting is unrealistic. Automatic save-and-resume — where the application state persists across sessions, devices, and even browsers — is not a luxury feature but a fundamental requirement.
Key design patterns for save-and-resume in mortgage applications include:
- Automatic Session Persistence: Application state saves after each section completion, triggered by navigation or timer. The member never needs to explicitly "save" their work.
- Cross-Device Continuity: A member starting the application on their phone during their commute should be able to continue on their laptop at home without losing progress. This requires session state architecture that synchronizes via the credit union's secure member portal.
- Progress Restoration with Context: When a member returns, the application should show not only their progress percentage but a brief summary of what they've already entered in each section. "You told us about your income and assets — next up is the property details."
- Abandoned Application Recovery: If a member has not returned to their application within 48 hours, an automated email and SMS sequence should re-engage them with a clear link to resume where they left off. Post-abandonment recovery nudges have been shown to recover 18-35% of abandoned mortgage applications.
Stage 4: Document Collection, Upload, and Verification UX
Document collection is consistently cited as the most anxiety-inducing phase of the mortgage process for borrowers, and it represents the single largest source of processing delays. The document upload UX must be designed to reduce anxiety, provide clear guidance, and minimize the cognitive load of determining what documents are needed and in what format.
Intelligent Document Checklist Architecture
Rather than presenting a generic list of "documents you might need," the document collection UX should dynamically generate a personalized checklist based on the specific loan scenario. A W-2 salaried employee buying a primary residence with 20% down needs dramatically fewer documents than a self-employed borrower putting 5% down on an investment property.
Document categories should be presented as organized, progress-tracked groups:
- Identity Documents: Driver's license, passport, or state ID
- Income Documents: W-2s (last 2 years), recent pay stubs (30 days), tax returns if self-employed
- Asset Documents: Bank statements (last 2-3 months), investment account statements, gift letter if applicable
- Property Documents: Purchase contract, home inspection report, insurance binder
- Additional Documents: Divorce decree (if applicable), rental lease history (if applicable), bankruptcy discharge papers (if applicable)
Each category should show a clear status: "Not Started," "Documents Needed (3)," "Documents Uploaded (2/3)," or "Complete." This progress visibility transforms an overwhelming document list into a manageable set of discrete tasks.
Mobile-Optimized Document Capture
Over 40% of mortgage document uploads now occur on mobile devices, according to industry data from Black Knight's mortgage technology division. Yet many credit union document portals remain optimized only for desktop browsers, forcing mobile members to switch devices or abandon the upload entirely.
Key design patterns for mobile document capture include:
- Camera-First Upload Flow: The default upload method should be "Take Photo" rather than "Choose File." On-device camera capture with AI-assisted framing guidance (edge detection for document boundaries, glare detection, blur detection) dramatically reduces the rejection rate of mobile-captured documents.
- Multi-Page Document Support: Members need to upload 2-3 pages of a bank statement, not just one. The mobile upload flow should support sequential capture with a "Add Another Page" button that creates a single document file from multiple photos.
- Real-Time Quality Feedback: After capture, the upload interface should provide immediate feedback: "Document uploaded successfully" or "This image appears blurry. Would you like to retake it?" Preemptive quality checking prevents the frustrating cycle of upload-and-reject.
- Alternative Upload Methods: In addition to mobile capture, support email-to-upload (member emails documents to a unique address that auto-attaches to their application) and fax-to-upload for older members who prefer traditional methods.
Document Status Transparency
Perhaps the most common source of mortgage-related member anxiety is the "document black hole" — documents are uploaded but the member has no idea whether they were received, are sufficient, or require follow-up. Every uploaded document should have a visible status:
- Processing: Document received, awaiting review (typically 1-4 hours during business hours)
- Reviewing: Document is being evaluated by a processing team member
- Approved: Document accepted — no action needed
- Action Needed: Document requires clarification or re-upload — with specific instructions on what needs to change
Each status change should trigger an automated notification (email and/or SMS) so the member never has to wonder where their application stands. This transparency alone has been shown to reduce member call volume by 30-40% during the processing phase, per industry benchmarks from Ellie Mae (now ICE Mortgage Technology) best practices.
Stage 5: Processing, Underwriting Communication, and Status Transparency
The processing and underwriting phase is the longest and most opaque segment of the mortgage timeline. While the lender's operations team processes documentation, orders valuations, and reviews compliance, the member often experiences a radio silence that erodes trust and generates anxiety. The UX goal at this stage is radical transparency: making the invisible work of processing visible and predictable.
Visual Mortgage Timeline and Milestone Tracking
A visual timeline showing the complete mortgage journey — from pre-qualification through closing — with current position highlighted serves as an orientation tool that reduces member anxiety. Key milestones include:
- Pre-Qualification Complete
- Application Submitted
- Documents Received (with percentage)
- Processing Review
- Appraisal Ordered
- Appraisal Received
- Underwriting Review
- Conditional Approval (if applicable)
- Clear to Close
- Closing Scheduled
Each milestone should include an estimated timeline window and, when delays occur, a proactive explanation rather than a silent status change. For example: "Appraisal ordered: Appraisals in your area are currently taking 5-8 business days due to high seasonal volume."
Conditional Approval UX
Conditional approval — where underwriting approves the loan subject to meeting specific conditions — is a high-anxiety moment that requires careful UX design. The conditions should be presented as a clear, action-oriented checklist:
- Each condition listed with specific instructions
- Clearly marked due dates
- Document upload directly from the condition checklist
- Ability to message the processing team with questions
- Clear celebration when all conditions are met
The "Clear to Close" milestone should be accompanied by a clear celebration animation or confirmation screen that transforms an abstract operational status into an emotional milestone. This is the point where the member transitions from "applying for a mortgage" to "about to buy a home" — the UX should reflect that psychological shift.
Stage 6: eClosing, eSignature, and Funding UX
The closing event, traditionally a high-pressure, hour-long meeting in a title company conference room with a stack of papers three inches thick, is being transformed by digital closing technology. The eClosing experience is the culmination of the mortgage journey and the last — and potentially most impactful — UX touchpoint before funding.
Digital Closing Disclosure Review
The Closing Disclosure (CD) is the most important document in the closing package, but its standard regulatory format is dense, confusing, and anxiety-inducing. A digital CD review experience should include:
- Annotated Summary: A plain-language overview of the key terms — loan amount, interest rate, monthly payment, closing costs due at signing — presented above the full legal document.
- Scroll-Based Annotation: As the member scrolls through the CD, contextual annotation bubbles explain each section in plain language. "This section shows your loan terms — the rate you locked, the loan amount, and your monthly payment. Nothing has changed since your initial estimate."
- Rate vs LE Comparison: An automatically generated side-by-side comparison of the Loan Estimate and the Closing Disclosure, highlighting any changes and explaining why each change occurred. This transparency is essential for member trust.
- Pinch-to-Zoom for Mobile: The CD must be fully readable on mobile devices, with pinch-to-zoom, tap-to-highlight, and screen-reader accessibility support.
eSignature Flow Design
The eSignature experience — where the member signs dozens of documents in rapid succession — must balance legal compliance with UX simplicity:
- Document Package Organization: Documents should be grouped by category (Loan Terms, Disclosures, Property, Insurance) with clear titles, not presented as a monolithic list of 40+ vaguely named files.
- Signature Collection Optimization: Rather than requiring a separate signature on every page, group related signature fields and minimize the total signature count while maintaining legal compliance. Monotony fatigue from excessive signature requirements has been shown to cause errors in later documents.
- Initial vs Full Signature: Design clear visual distinction between fields requiring a full signature and those requiring initials. Standard UX patterns use an underline for initials and a solid box for full signatures.
- Audio-Visual Notarization (RON): For states requiring notarization, integrate Remote Online Notarization (RON) directly into the eClosing flow. The notary video session should appear as a seamless step in the closing sequence, not a separate process requiring a different login.
- Mobile-Responsive eClosing: The entire eClosing experience must function flawlessly on mobile devices. Over 35% of digital closings now occur on smartphones, and that share is growing by 5-8% annually.
The visual design of the eClosing environment — the digital equivalent of the closing table — should convey security, professionalism, and warmth. Glassmorphism effects, subtle animations during document signing, and celebratory visual feedback at completion transform a sterile legal process into an emotionally resonant milestone.
Funding and Post-Funding Experience
The moment of funding — when the loan amount is disbursed — represents the transactional conclusion but the relational beginning. The funding UX should include:
- Funding Confirmation: A celebratory confirmation screen with the funding date, first payment date, and welcome to the credit union's mortgage servicing portal.
- First Payment Countdown: A clear display showing when the first payment is due and how to set up autopay.
- Digital Welcome Package: A post-closing digital welcome package that introduces the member to their mortgage servicing portal, explains escrow/impound accounts if applicable, and offers to set up automatic payment.
- Homeowner Resources: Links to homeowner resources — insurance partners, home warranty information, energy efficiency rebate programs, and credit union member benefits now available (home equity lines, renovation loans, etc.).
Stage 7: Post-Closing Member Experience and Relationship Continuity
The post-closing period is the most under-optimized phase of the mortgage member journey, yet it is arguably the most valuable for long-term relationship building. A mortgage member is, by definition, a highly engaged borrower with significant financial exposure to the credit union — and significant revenue potential over the life of the loan.
Mortgage Servicing Portal UX
The mortgage servicing portal — where members make payments, view statements, and manage their escrow accounts — should be designed with the same UX rigor as the origination experience. Key design elements include:
- Dashboard with Mortgage Health Indicators: Current balance, interest paid year-to-date, payoff estimate, and equity position displayed as visual metrics. The "payoff estimate" with a "What if I paid extra?" interactive calculator is particularly powerful for member engagement.
- Payment Management: Clear payment due date, auto-pay enrollment, one-time payment from any linked account, and payment history with downloadable annual statements.
- Escrow/Impound Account Visibility: For members with escrowed taxes and insurance, a clear breakdown of current escrow balance, upcoming payouts, and the ability to view property tax bills and insurance policies.
- Home Equity Access: A prominent "Your Home Equity" section showing current estimated equity (based on either the purchase price or an updated AVM valuation) with clear CTAs for HELOC, home equity loan, or renovation financing.
Milestone-Based Engagement
The post-closing relationship should include automated, value-adding touchpoints at key milestones:
- Day 30: Welcome call/email confirming payment was received, autopay is working, and the member is settled into their new home. Include a satisfaction survey about the mortgage experience.
- Month 6: "Equity Check-In" — a personalized equity estimate based on initial down payment and estimated appreciation.
- Year 1: "Your First Year of Homeownership" — annual summary of interest paid, principal paid, tax deductions, and equity gained.
- Year 3 and 5: Refinance eligibility check — proactively notifying members when they may qualify for a better rate based on current market conditions and their payment history.
- Significant Payment Milestones: When a member pays down their principal to 80% LTV, automatically notify them about PMI removal eligibility. When they reach 50% equity, alert them about HELOC pre-qualification options.
Mobile-First Mortgage UX Design Patterns
The majority of mortgage research, pre-qualification, and initial application activity now occurs on mobile devices, yet the mortgage industry has been slower than nearly any other financial services vertical to adopt mobile-first design principles. A truly mobile-first mortgage UX must go beyond responsive design to consider the unique constraints and opportunities of the mobile context.
Thumb-Zone Navigation for Mortgage Applications
The thumb zone — the area of a mobile screen that is naturally reachable by the user's thumb — is critical for mortgage application design. Key form elements — next/continue buttons, signature fields, consent checkboxes — must be positioned within the lower third of the screen where thumbs naturally rest. Information display fields (read-only content, terms, disclosures) should be positioned in the upper zones.
Micro-Moment Mortgage Architecture
Mortgage applications are uniquely suited to micro-moment design — breaking the application into tasks that can be completed in 30-90 second intervals during natural mobile usage periods (commuting, waiting in line, watching television). Rather than expecting completion in one sitting, the UX should explicitly embrace and support micro-moment completion:
- Each section of the application should be completable in under 3 minutes
- Auto-save occurs after every field, not every section
- Push notifications remind members of incomplete sections with a single-tap resume
- Document capture is designed for "point and shoot" rather than "find, scan, and upload"
Biometric Authentication for Sensitive Actions
Mortgage applications involve the most sensitive personal and financial data a member will ever share online. Mobile-first mortgage UX should leverage on-device biometric authentication (fingerprint, facial recognition) for high-sensitivity actions — accessing saved applications, viewing pre-qualification results, and signing closing documents — rather than requiring repeated password entry or SMS verification codes that interrupt the flow.
Designing for First-Time Home Buyers: Education, Confidence, and Trust
First-time home buyers represent the fastest-growing segment of mortgage applicants and the segment most likely to abandon a digital mortgage process due to confusion, anxiety, or lack of guidance. Credit unions have a natural advantage with this demographic — their mission-driven, educational approach aligns perfectly with what first-time buyers need — but only if the digital experience translates that ethos into UX design.
Educational Content Architecture
Rather than isolating educational content on a separate "Resources" page, effective mortgage UX for first-time buyers weaves education directly into the application flow:
- Contextual Learning Modules: At critical decision points — down payment amount, rate selection, closing costs — a 30-second explainer video or interactive calculator appears inline, helping the member understand what they are deciding and why it matters.
- Jargon-Busting Design: Every mortgage term that would be unfamiliar to a first-time buyer should have a plain-language definition available via a tap-and-hold or hover interaction. Terms like "amortization," "escrow," "PMI," "impound account," and "title insurance" are unfamiliar to 70%+ of first-time buyers, according to a 2023 study by the Urban Institute.
- Decision Support Tools: Interactive tools that help first-time buyers compare renting vs. buying, calculate total closing costs, estimate property taxes and insurance, and understand the true monthly cost of homeownership (including maintenance, utilities, and HOA fees that many first-time buyers underestimate).
- Home Buyer Education Integration: Integration with HUD-approved home buyer education courses, with completion tracked directly within the mortgage portal. Members who complete home buyer education have a 34% lower default rate and are significantly more likely to close on their mortgage application.
Building Confidence Through Transparency
First-time buyer anxiety is rooted in fear of the unknown — making an expensive commitment without understanding the process. UX patterns that build confidence include:
- Process Preview: Before the application begins, a "What to Expect" timeline showing every step of the mortgage process, estimated durations, and what the member needs to provide at each step.
- Loan Officer Assignment Transparency: Clear communication about who is handling the application, with photo, credentials, and direct contact information. A warm transfer to a live loan officer at key transition points — from pre-qualification to application, from processing to underwriting — builds relationship trust.
- Pre-Approval Letter with Digital UX: The pre-approval letter itself should be designed as an interactive digital asset, not a PDF attachment. A dynamic pre-approval dashboard showing the approved amount, estimated rate range, and key terms that the member can reference during house hunting.
- Peer Stories and Social Proof: Testimonials and "member journey" stories from first-time buyers who successfully closed through the credit union, showing the specific ways the credit union helped them navigate challenges.
Accessibility and Inclusive Design in Mortgage UX
Mortgage accessibility is not simply a compliance requirement — it is a critical business and mission imperative for credit unions. With over 1 billion people worldwide living with disabilities, and with credit unions serving a disproportionately high share of older members, the digital mortgage experience must be designed for full accessibility from the ground up.
WCAG 2.2 AA Compliance in Mortgage Contexts
The Web Content Accessibility Guidelines (WCAG) 2.2 AA standard sets the baseline for mortgage UX accessibility, but mortgage applications present unique accessibility challenges that require specific design attention:
- Complex Form Accessibility: Mortgage forms contain hundreds of fields with complex validation rules, conditional logic, and multi-page sequences. Each field must have explicit labels (never in-field hints as labels), clear error messages that explain how to fix errors, and logical tab order that follows the visual flow.
- Document Accessibility: All mortgage documents — Loan Estimate, Closing Disclosure, promissory note, deed of trust — must be available in screen-reader accessible HTML format, not just PDF. PDF accessibility for the 40+ page closing package is notoriously unreliable with current screen reader technology.
- Time-Based Task Accessibility: Mortgage applications often have implicit time pressure (rate locks expiring, closing dates approaching). WCAG requires that users with disabilities have adequate time to complete tasks — the interface should never use time-based session expirations that risk data loss during an intentionally slow interaction.
- Color and Contrast for Financial Data: Rate comparisons, fee visualizations, and disclosure annotations must pass WCAG contrast requirements (minimum 3:1 for normal text, 4.5:1 for small text) and must never rely solely on color to convey information. All data visualizations must include pattern, text label, or position alternatives.
- Voice and Screen Reader Support for Document Review: The eSignature and document review flow must be fully navigable via keyboard and screen reader, with logical heading hierarchy and ARIA landmark regions marking each document section.
Cognitive Accessibility Considerations
Mortgage applications impose extremely high cognitive load on ALL users, but especially on users with cognitive disabilities, low financial literacy, or limited English proficiency. Design patterns that reduce cognitive accessibility barriers include:
- Plain Language Throughout: All instructions, disclosures, and communications written at an 8th-grade reading level or below, with complex terms defined in plain language before they are used in context.
- Consistent Navigation and Predictable Layout: Each section of the application follows the same layout pattern with the same navigation elements in the same positions, reducing the cognitive cost of learning each new section.
- Generous Time Allowances: No session timeouts during active application sessions. If a member needs 20 minutes to complete a single section, the system should accommodate that without data loss.
- Multiple Format Options: All disclosures, educational content, and communications available in text, audio (professional narration), and video (ASL-interpreted) formats.
- Translation and Language Access: Given the CFPB's regulatory guidance on language access and the credit union mission to serve diverse communities, the mortgage application should offer Spanish, Mandarin, Vietnamese, Tagalog, Arabic, and Korean language options — at minimum — covering the most commonly spoken languages in credit union fields of membership.
Regulatory Compliance and UX: TILA, RESPA, ECOA, and E-SIGN in Practice
Mortgage lending is the most heavily regulated consumer financial product in the United States, and every digital UX decision must operate within a complex regulatory framework. However, regulatory compliance and good UX are not in conflict — the most consumer-protective regulatory requirements align directly with UX best practices when properly designed.
Integrated TILA/RESPA Disclosure Timing
The Truth in Lending Act (TILA) and Real Estate Settlement Procedures Act (RESPA) require specific disclosures at specific times — the Loan Estimate within three business days of application, the Closing Disclosure at least three business days before closing. Digital UX must make these regulatory deadlines visible and predictable:
- Disclosure receipt confirmation should be digital and immediate, not dependent on mailed paper.
- TILA/RESPA integrated disclosure buttons should be prominent and time-stamped within the application flow.
- Countdown clocks showing disclosure delivery deadlines build trust and demonstrate regulatory compliance visibly.
ECOA and Fair Lending UX Considerations
The Equal Credit Opportunity Act (ECOA) requires that lenders provide a specific reason for adverse action and that the lending process not discriminate on prohibited bases. UX design implications include:
- Clear Adverse Action Notices: When a member is declined, pre-qualified at a lower amount, or offered a counterproductive rate, the specific reasons should be communicated clearly and compassionately, with actionable steps for improvement.
- Nondiscriminatory Form Design: Field design and information requests should not disproportionately impact protected classes. For example, requiring a Social Security number for pre-qualification may discriminate against recent immigrants with ITINs — the UX should accommodate alternative identification from the start.
- Equal Access to Digital Tools: All digital mortgage tools — rate calculators, pre-qualification engines, application portals — must be equally accessible in English and in threshold languages (any language spoken by 5%+ of the CUs field of membership).
E-SIGN Act Compliance UX
The Electronic Signatures in Global and National Commerce Act (E-SIGN) requires specific consent and disclosure processes before electronic signatures are legally binding. The UX design of the E-SIGN consent process should:
- Present clear, unambiguous consent language at the beginning of the eClosing session
- Provide a genuine choice between electronic and paper delivery (not just "default to electronic")
- Document consent through an auditable digital record
- Allow the member to withdraw consent and switch to paper at any time without penalty
When these compliance requirements are designed as friction-reducing UX features rather than legal barriers, the regulatory framework becomes an asset for building member trust rather than an obstacle to digital conversion.
Technology Stack and Integration Architecture
The digital mortgage UX is only as good as the technology infrastructure that powers it. A best-in-class credit union digital mortgage experience requires thoughtful integration of multiple technology layers:
Point-of-Sale (POS) Systems
The mortgage point-of-sale system — the digital front door where members apply — should support the complete digital application flow described above. Leading POS platforms for credit unions include MeridianLink, MortgageFlex, Black Knight's Empower, and ICE Mortgage Technology's Encompass. Key evaluation criteria for POS selection include progressive disclosure support, document management capabilities, mobile responsiveness, and API-driven integration architecture.
Digital Document Management
Document management systems for mortgage lending must go beyond simple file storage to support intelligent document classification, automated quality checks, optical character recognition (OCR) for data extraction, and secure sharing with third-party service providers (appraisers, title companies, insurance agents). Integration with eSign platforms (DocuSign, DocMagic, Notarize) for the eClosing flow is essential.
Automated Underwriting System (AUS)
Integration with Fannie Mae's Desktop Underwriter (DU) and/or Freddie Mac's Loan Product Advisor (LPA) enables instant credit decisions on straightforward applications. The AUS integration should be seamless from the member's perspective — they submit their application and receive a real-time decision without understanding the complex engine processing in the background.
LOS and Core Integration
The Loan Origination System (LOS) must integrate with the credit union's core processing platform to enable seamless data flow, automated member record updates, and real-time servicing integration. APIs between the LOS and core should support bidirectional data exchange — application data flows into the core for member profile updates, and servicing data flows back to the LOS for portfolio performance tracking.
CRM and Communication Platform
A CRM integrated with the mortgage platform enables automated, personalized communication throughout the mortgage lifecycle — from application confirmation and document requests through condition satisfaction and closing scheduling. Two-way SMS capabilities allow members to text questions to their loan processor and receive responses within the same thread, significantly reducing phone call volume.
KPI Framework for Digital Mortgage Success
Measuring digital mortgage UX success requires a balanced scorecard of member experience, operational efficiency, and business outcome metrics:
Leading Indicators (Real-Time Experience Metrics)
- Pre-Qualification Completion Rate: Percentage of visitors who start pre-qualification and complete it (benchmark: 50-65%)
- Application Conversion Rate: Percentage of pre-qualified members who start a full application (benchmark: 20-35%)
- Application Completion Rate: Percentage of started applications that reach submission (benchmark: 45-65%)
- Average Application Time: Total active time spent completing the application (benchmark: under 60 minutes for full application)
- Mobile Document Capture Rate: Percentage of documents uploaded via mobile device (benchmark: 35-45%)
- Document Resubmission Rate: Percentage of documents rejected and requiring resubmission (benchmark: under 15%)
- eClosing Dropout Rate: Percentage of members who start eClosing but do not complete (benchmark: under 5%)
Lagging Indicators (Business Outcome Metrics)
- Application-to-Close Rate: Percentage of submitted applications that reach closing (benchmark: 65-80% for purchase, 55-70% for refinance)
- Average Days to Close: From application submission to funding (benchmark: under 35 days for purchase, under 30 for refinance)
- Member Satisfaction (NPS or CSAT): Post-closing satisfaction survey score (benchmark: NPS 70+ or CSAT 4.5+/5)
- Mortgage Cross-Sell Rate: Percentage of mortgage members who open additional products (checking, credit card, HELOC) within 12 months of closing (benchmark: 25-40%)
- Digital Channel Cost Per Loan: Cost to originate a loan through digital channels vs. traditional branch channel (benchmark: digital should be 40-60% lower)
- Member Retention Rate: Percentage of mortgage members still banking with the credit union 2 years post-closing (benchmark: 85%+)
Small Credit Union Strategies
Small credit unions — those under $500 million in assets — face the most significant digital mortgage UX challenges because they lack the resources for custom technology development and dedicated mortgage technology teams. However, several strategies can bridge the gap:
Platform-Leveraged Solutions
Rather than building a custom digital mortgage experience, small credit unions can leverage existing platform capabilities. Many core processors now offer integrated mortgage point-of-sale modules that, while not as sophisticated as best-in-class systems, provide a dramatically better experience than PDF-based workflows. Platform-leveraged digital mortgage capabilities typically cover pre-qualification, application, and document upload — the three highest-impact digital features for conversion.
CUSO Shared Services
Credit Union Service Organizations (CUSOs) focused on mortgage lending — such as CU Members Mortgage, First Mortgage Solutions, and PFCU Mortgage Services — provide white-label digital mortgage experiences that small credit unions can offer under their own brand. These services handle the technology infrastructure, compliance management, and often the processing and underwriting themselves, allowing the credit union to offer a best-in-class digital mortgage experience without technology investment.
Progressive Enhancement
Small credit unions should not attempt to build a comprehensive digital mortgage experience in one project. Instead, progressive enhancement — adding one digital capability at a time in order of member impact — allows for manageable investment with measurable results:
- Phase 1: Digital pre-qualification with soft credit pull (highest impact, lowest cost)
- Phase 2: Digital document upload with mobile capture
- Phase 3: Digital application with save-and-resume
- Phase 4: Status transparency dashboard
- Phase 5: eClosing and eSignature integration
90-Day Implementation Roadmap
For credit unions ready to begin their digital mortgage UX transformation, a 90-day phased approach can deliver measurable improvements quickly:
Days 1-30: Foundation and Assessment
- Audit current digital mortgage experience against the seven-stage framework outlined in this guide
- Benchmark current completion rates, abandonment points, and member satisfaction scores
- Conduct 5-8 member interviews focused on mortgage application pain points
- Evaluate technology platform capabilities and integration requirements
- Define target metrics and establish measurement infrastructure
- Select Phase 1 prioritization (recommended: pre-qualification + document upload)
Days 31-60: Phase 1 Implementation
- Deploy instant soft-pull pre-qualification on the credit union website
- Implement mobile-optimized document upload with camera capture and quality checking
- Integrate document status transparency (received, reviewing, approved, action needed)
- Add save-and-resume capability to existing application (if possible within current platform)
- Train lending team on new digital tools and member handoff protocols
- Launch A/B test: digital pre-qualification vs. existing process
Days 61-90: Optimization and Expansion
- Analyze Phase 1 results and iterate on highest-abandonment points
- Deploy automated document request sequences (email/SMS reminders)
- Implement milestone-based status tracking with proactive notifications
- Begin Phase 2 planning: digital application, eClosing, or rate comparison tools
- Create post-closing member engagement sequence (welcome package, equity check-ins)
- Document best practices and develop training for lending staff
Future Trends: AI, Open Banking, and the Mortgage of 2030
The digital mortgage experience will continue to evolve rapidly over the next five years, driven by three transformative technology trends:
AI-Powered Mortgage Experience
Artificial intelligence is transforming digital mortgage UX across multiple dimensions. AI-powered document classification automatically categorizes uploaded documents and extracts key data fields, reducing manual processing time. AI-powered chatbots guide members through the application process with natural language conversation, answering questions and providing real-time status updates. AI-powered underwriting — already used by fintech lenders for automated credit decisions — will expand to handle increasingly complex loan scenarios with minimal human intervention. And AI-powered personalization will tailor the mortgage experience — recommended products, educational content, communication preferences — to each individual member's profile and behavior.
Open Banking and Section 1033
The Consumer Financial Protection Bureau's Section 1033 open banking rule, when fully implemented, will require financial institutions to make consumer financial data available through standardized APIs at the consumer's direction. For mortgage lending, this means pre-qualification and application data (income, assets, identity) can be verified through direct, consumer-permissioned data access rather than through document uploads and manual verification. The result will be a mortgage application that pre-fills from a member's existing banking data — reducing application time from 45+ minutes to under 10 minutes for many borrowers.
Voice and Conversational Interfaces
Voice-based mortgage interactions — checking application status, scheduling closing appointments, requesting document clarifications — will become increasingly common as natural language processing improves. While complete voice-based mortgage applications remain unlikely due to the complexity of financial data entry, voice interfaces for status checks, appointment scheduling, and basic information lookups will reduce member call volume and improve accessibility for visually impaired members.
Embedded Mortgage Lending
The most transformative trend in mortgage distribution is embedded lending — mortgage pre-qualification and application integrated directly into the home search experience. Zillow, Redfin, and Realtor.com already offer pre-qualification within their platforms, and this trend will accelerate. Credit unions that develop API-based pre-qualification capabilities can integrate with real estate platforms, home builder portals, and realtor websites to capture mortgage applications at the moment of highest intent — during the home search itself.
References
- Consumer Financial Protection Bureau. (2023). TILA-RESPA Integrated Disclosure Rule
- Federal Housing Finance Agency. (2024). Underserved Markets and Access to Credit
- J.D. Power. (2024). U.S. Mortgage Origination Satisfaction Study
- Nielsen Norman Group. (2023). Progressive Disclosure in Long Form Design
- Baymard Institute. (2024). Large-Scale Checkout Form Usability Benchmark
- Plaid. (2024). The State of Open Finance Data Sharing
- Filene Research Institute. (2023). Digital Member Acquisition in Credit Unions
- CUNA. (2024). Mortgage Lending Regulatory Advocacy
- Federal Financial Institutions Examination Council. (2024). Home Mortgage Disclosure Act Data
- W3C Web Accessibility Initiative. (2023). Web Content Accessibility Guidelines (WCAG) 2.2
- Fannie Mae. (2024). Desktop Underwriter Automated Underwriting System
- Freddie Mac. (2024). Loan Product Advisor Automated Underwriting System
- Pew Research Center. (2024). Mobile Technology Fact Sheet
- Consumer Financial Protection Bureau. (2024). Mortgage Compliance Resources
- Rocket Mortgage. (2024). Digital Mortgage Technology Platform
- Better.com. (2024). Digital Mortgage Experience
- SoFi. (2024). Home Loan Products and Digital Experience
- Black Knight, Inc. (2024). Mortgage Technology Platform Solutions
- ICE Mortgage Technology. (2024). Encompass Digital Lending Platform
- Urban Institute. (2023). Home Mortgage Accessibility for First-Time Buyers
- Consumer Financial Protection Bureau. (2023). E-SIGN Act Compliance Guide
- Federal Reserve Board. (2024). Mortgage Market Activity Report
- National Association of Realtors. (2024). Home Buyer and Seller Demographics
- U.S. Department of Housing and Urban Development. (2024). Home Buyer Education Programs
- Consumer Financial Protection Bureau. (2023). Equal Credit Opportunity Act Compliance
- Nielsen Norman Group. (2023). In-Field Hints in Form Fields Create Usability Issues
- Federal Reserve. (2023). Survey of Household Economics and Decisionmaking (SHED)
- TransUnion. (2024). Mortgage Lending Industry Insights
- Equifax / The Work Number. (2024). Income and Employment Verification Services
This article was brought to you by GrafWeb CUSO – Building the future of digital credit unions.