
Introduction: The Credit Card Experience Gap
Credit cards represent one of the most profitable and relationship-deepening products a credit union offers. According to industry data, credit card holders carry an average of 2.24 credit cards and hold approximately $3,911 in revolving debt per consumer. Yet for most credit union members, the digital experience of managing their credit card — from activation through ongoing rewards engagement to dispute resolution — falls dramatically short of what they expect.
The gap is not subtle. When a member receives a new credit card in the mail, their first digital touchpoint is card activation. At large fintechs and megabanks, this process takes under 60 seconds and flows seamlessly into mobile wallet enrollment. At many credit unions, it is a multi-step ordeal involving phone calls, clunky web forms, and separate app downloads. That first impression shapes the member's entire relationship with the product.
📑 Table of Contents
- Introduction: The Credit Card Experience Gap
- The Market Context: Why Credit Card UX Matters for Credit Unions
- First Impressions: Digital Card Activation and Mobile Wallet Enrollment
- The Rewards Dashboard: Making Points Visible and Valuable
- Spending Intelligence: Transaction Categorization, Insights, and Budgeting
- Payment Management: Auto-Pay, Statement Access, and Balance Tracking
- Card Controls and Security: Lock/Unlock, Travel Notifications, and Alerts
- Dispute Resolution UX: Turning a Pain Point into a Trust Signal
- Mobile-First Design Patterns for Credit Card Management
- Accessibility and Inclusive Design for Cardholder Portals
- AI-Driven Personalization for Credit Card Experiences
- Implementation Roadmap
- Small Credit Union Strategies
- Key Performance Indicators
- Future Trends in Credit Card Digital Experiences
- Conclusion
- References
This comprehensive playbook covers every dimension of the credit card digital experience: activation and mobile wallet enrollment, rewards dashboards and points visibility, spending intelligence and category insights, payment management and auto-pay configuration, card controls and travel notifications, dispute resolution, mobile-first design patterns, accessibility compliance, AI-driven personalization, and a phased implementation roadmap. Credit unions that invest in these A Technology and UX Implementation Guide for Remote Service — The AI-Powered Member Portal Personalization Layer: How Predictive Member Intelligence and Adaptive Digital Experiences Transform Video Banking Engagement and Drive Member Lifetime Value">digital experiences do not just reduce operational costs — they deepen member relationships, increase card usage, and create stickiness that reduces attrition to competitors.
The Market Context: Why Credit Card UX Matters for Credit Unions
The Numbers Behind the Opportunity
The US credit card market encompasses over 564 million open accounts with $4.4 trillion in total available credit limits as of late 2025. With total revolving debt approaching $1 trillion, credit card interest income and interchange fees represent a critical revenue stream for financial institutions. Credit unions collectively issue millions of credit cards, but they face fierce competition from Chase, Capital One, Citi, American Express, and a growing wave of fintech card issuers like Chime, SoFi, and Coinbase.
J.D. Power's 2025 US Credit Card Satisfaction Study found that digital experience is now the single strongest predictor of overall cardholder satisfaction, surpassing interest rates, rewards value, and customer service. Members who rate their credit union's mobile app or online banking experience as "excellent" are 3.4 times more likely to use their credit union credit card as their primary card. Conversely, members who encounter friction in digital card management are 47% more likely to consider switching their primary card to a competitor.
The Generational Imperative
Millennials and Gen Z now represent the largest demographic segments of credit card holders. These digital-native members expect:
- Instant virtual card issuance at approval, not physical card wait times
- One-tap mobile wallet enrollment (Apple Pay, Google Pay, Samsung Pay)
- Real-time transaction notifications with merchant logos and map locations
- Intelligent spending categorization with visual breakdowns
- Self-service card controls (lock, limit, travel notifications)
- Rewards redemption that feels more like a game than a form
Credit unions that cannot deliver these experiences lose their youngest and most valuable members to fintech disruptors that built their products around these expectations from day one.
The Credit Union Advantage
Despite the digital gap, credit unions possess structural advantages in credit cards: lower average interest rates (typically 2-5 percentage points below big banks), better member service, and community trust. The challenge is translating these advantages into a digital experience that competes. A well-designed credit card management portal does not need to match Chase's billion-dollar technology budget — it needs to eliminate friction at the critical moments that define the cardholder relationship.
First Impressions: Digital Card Activation and Mobile Wallet Enrollment
The Activation Moment
Card activation is the first digital interaction a member has with their new credit card product. It sets expectations for the entire relationship. In 2026, the benchmark for card activation is:
- Virtual card issuance at approval: The member should see their card number, CVV, and expiration date immediately upon approval, with the ability to add it to a mobile wallet before the physical card arrives. This is table stakes for competing with Chase, Apple Card, and SoFi.
- No-phone-call activation: If phone activation is required, it should be fully automated via IVR. Better yet, eliminate phone activation entirely and make it a digital-only process.
- Unified authentication: If the member is already logged into online banking or the mobile app, activation should not require re-authentication. A simple "Activate Your Card" button with a one-time code sent to a trusted device is sufficient.
- Card art preview: Show the member what their physical card will look like with a high-quality rendering, reinforcing the emotional connection to the product.
Mobile Wallet Enrollment
Apple Pay and Google Pay enrollment should be a one-tap process, not a multi-screen maze. The member should be able to complete enrollment without leaving the activation flow. Research from the Baymard Institute shows that each additional step in a digital process reduces completion rates by 10-20%. Mobile wallet enrollment that requires the member to navigate away from the app, open their phone settings, and manually enter card details will achieve adoption rates below 30%. In contrast, seamless in-flow enrollment achieves 70-80% adoption.
Design patterns for effective mobile wallet enrollment include:
- Post-activation prompt: Immediately after successful activation, present a clear choice: "Add to Apple Pay" or "Add to Google Pay" with prominent buttons and platform-specific icons
- Deep-linking: Use Apple's and Google's APIs to directly invoke the wallet enrollment flow rather than requiring manual entry
- Confirmation and animation: Show a micro-animation of the card sliding into the phone's wallet, accompanied by a confirmation message
- Enrollment tracking: Allow members to see which of their cards are enrolled in which wallets from the card management dashboard
Priority Digital Card Issuance
For credit unions using card processors that support digital issuance (such as Elan, CO-OP's card services, or PSCU), instant virtual card provisioning at the point of approval is the single highest-impact investment. Members who receive instant access to their card number via the credit union's mobile app are significantly more likely to use the card for an immediate purchase, establishing usage momentum that drives long-term engagement.
The Rewards Dashboard: Making Points Visible and Valuable
Rewards are the primary reason members choose a credit union credit card over a debit card or competing product. Yet most credit union rewards programs obscure point balances behind multiple clicks, make redemption cumbersome, and fail to communicate the accumulating value of rewards in terms members care about.
Always-Visible Points Balance
The cardinal rule of rewards UX: points should never be hidden. When a member logs into the mobile app or online banking, their current points balance and estimated dollar value should be visible on the first screen — ideally on the accounts overview dashboard alongside their card balance. Design patterns include:
- Card-level rewards summary: Next to the card balance display, show "12,430 points ($124.30)" as a single glanceable metric
- Rewards tile: A dedicated "Rewards" tile on the dashboard that shows total points, recent points earned, and a prominent "Redeem" button
- Transaction-level points: Each transaction in the recent activity list should show how many points were earned for that specific purchase
Point Accrual Visualization
Points are an abstract concept. Effective design transforms them into a tangible, motivational display:
- Progress toward next reward: "You're 2,500 points away from a $25 statement credit" with a visual progress bar
- Earning patterns: A simple chart showing "Points earned this month" vs. previous months, reinforcing the behavior of using the card
- Category breakdown: "You earned 1,200 points on dining this month" with a color-coded visual breakdown of earning categories
- Estimated annual value: "At your current spending rate, you'll earn approximately 36,000 points ($360) this year"
Redemption Experience
Redemption is where most credit union rewards programs fail. The member has accumulated points but cannot figure out how to use them, or the redemption options are limited and confusing.
- One-tap statement credit: The simplest, most popular redemption option should be the most prominent: "Apply points as statement credit" with a clear calculation of how much the member will save
- Visual comparison: Show redemption options in a card-based layout that allows side-by-side comparison of value: statement credit ($25), gift card ($25 value for 2,500 points), travel credit ($25+ value), merchandise
- Points + cash hybrid: Allow members to use a combination of points and cash to "buy" any redemption option, preventing the "I don't have enough points" barrier
- Redemption history: Show what the member has redeemed in the past year, reinforcing the value they have already received
Tiered Rewards and Bonus Categories
Many credit union credit cards offer tiered rewards — 3% on dining, 2% on groceries, 1% on everything else. The digital experience must make these tiers clear and actionable:
- Category spotlight: A visual card or badge showing "This month's bonus category: Dining — 3x points" that updates dynamically
- Spending by category: A treemap or donut chart showing the member's spending breakdown by category alongside the points earned in each
- Bonus tracker: "You've earned 450 bonus points this month on dining purchases" with a progress indicator toward any category spending cap
- Seasonal promotions: Clear, prominent display of limited-time bonus offers with countdown timers to create urgency
Spending Intelligence: Transaction Categorization, Insights, and Budgeting
Credit card statements are a rich source of personal financial data, but most credit unions present this data as a raw list of transactions. Members increasingly expect the kind of spending intelligence that fintechs like Mint, YNAB, and Cleo provide.
Transaction Categorization
Automatic, accurate transaction categorization is the foundation of spending intelligence. Modern machine learning models can categorize 95%+ of transactions with merchant metadata:
- Merchant logos and maps: Each transaction should display the merchant's logo and a map link, adding visual context that makes the list scannable
- Editable categories: Allow members to recategorize transactions with a simple tap-and-select interface, improving the model over time
- Category-level summary: "This month: $1,247 in Dining (+12% vs last month), $543 in Groceries (-5% vs last month)"
Spending Insights
Beyond categorization, intelligent insights turn transaction data into actionable information:
- Recurring subscription detection: "You have 8 recurring subscriptions totaling $214/month. Would you like to see a full list?"
- Spending trends: "Your monthly credit card spending has increased 18% over the last 3 months. Here's where the growth is happening."
- Unusual spending alerts: "Your spending at gas stations is 40% higher than usual this month. Tap to review."
- Comparison to peers: "Credit union members similar to you spend an average of $380/month on dining. Your dining spend is $520/month." (Must be opt-in for privacy)
Budgeting Integration
Integrating credit card spending into a broader budgeting view gives members a complete picture of their finances:
- Credit card budget cap: Allow members to set a monthly spending limit on their card with real-time tracking and alerts
- Category budgets: "You set a $400 dining budget for this month. You've spent $320 (80%), with 12 days remaining."
- Rollover tracking: Show how credit card spending impacts overall cash flow and savings goals
Payment Management: Auto-Pay, Statement Access, and Balance Tracking
Balance Display
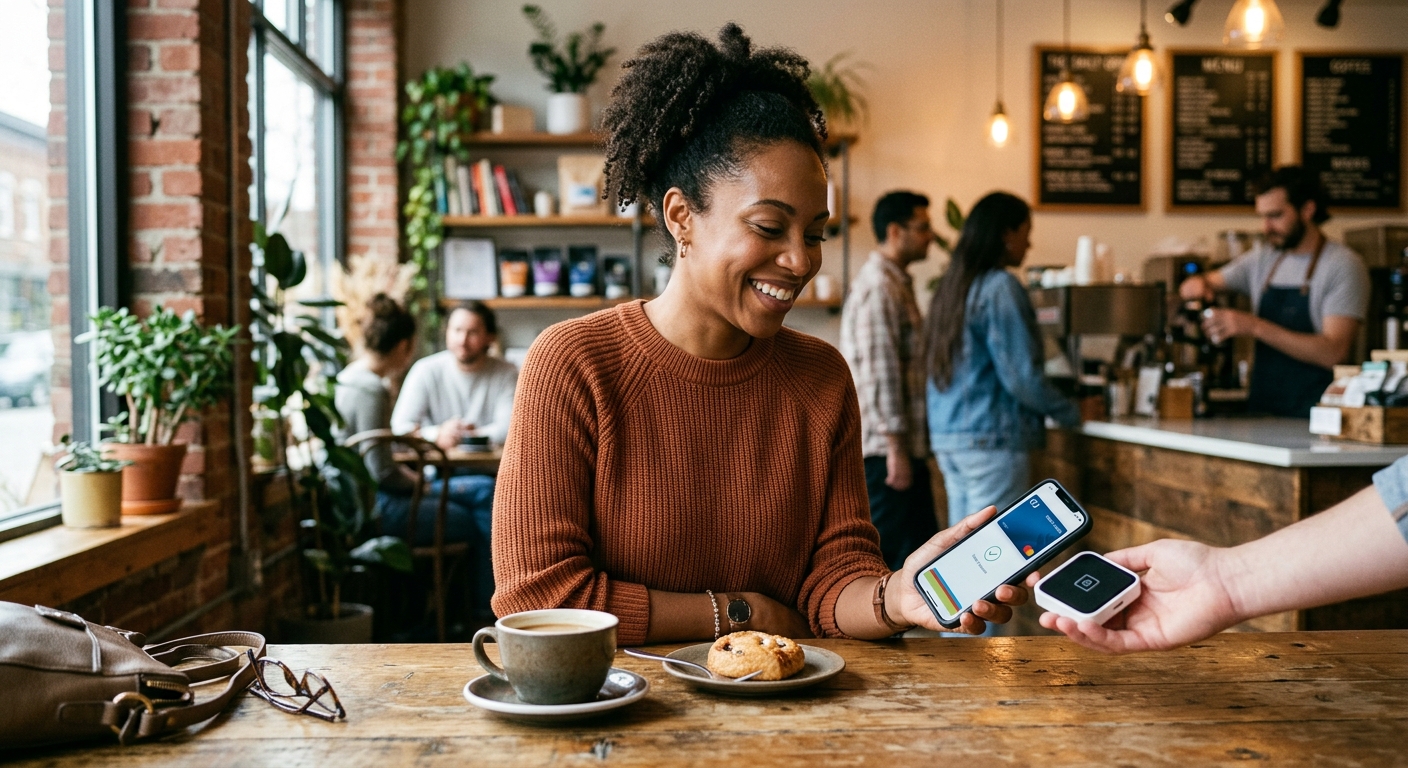
Credit card balance presentation requires more nuance than deposit accounts because of the revolving nature of the debt:
- Multi-value display: Show current balance, available credit, total credit limit, minimum payment due, and payment due date in a glanceable card format
- Visual utilization: A color-coded progress bar showing credit utilization (green under 30%, yellow 30-50%, red over 50%)
- Grace period indicator: "Pay $1,247 by October 15 to avoid interest on new purchases" — a clear call to action tied to the grace period
- APR transparency: Show the card's purchase APR and cash advance APR with an educational "Learn how interest is calculated" link
Auto-Pay Configuration
Auto-pay reduces late payments, improves members' credit scores, and lowers operational costs. But auto-pay setup is often buried behind multiple menu levels:
- One-tap setup: "Set up automatic payments" should be a single-tap action, not a multi-page form
- Flexible options: Allow members to choose "minimum payment," "full statement balance," or "custom amount" with clear explanation of each
- Payment date selection: Let members choose the day of month for auto-payments, aligned with their pay cycle
- Funding source: Allow selection of the deposit account for auto-pay funding with balance verification
Statement Access
Digital statements remain a regulatory requirement and a member expectation, but the experience is often archaic:
- Inline viewing: Display statements as interactive HTML in the browser or app, not just PDF downloads
- Searchable transactions: Allow members to search and filter transactions within the current statement period without downloading
- Paperless enrollment: Prominent paperless enrollment with clear savings messaging ("Save trees and get earlier access to your statements")
- Archived access: At least 24 months of statement history accessible with one tap, 7 years via request
Card Controls and Security: Lock/Unlock, Travel Notifications, and Alerts
Instant Card Lock/Unlock
The ability to instantly lock a lost or potentially compromised credit card is the most important security feature a credit union can offer. It is also a feature where speed matters more than anything else:
- Zero-click lock from notification: When a fraud alert notification fires, the lock/unlock action should be available directly in the notification without requiring app login
- Prominent toggle: On the card detail screen, the lock/unlock toggle should be the first interactive element, with a clear visual state (green = active, red = locked)
- Instant propagation: The lock action must take effect at the processor level within seconds, not minutes. Test this regularly with your card processor.
- Confirmation and next steps: After locking a card, show "Your card is locked. No new transactions will be authorized. Here's how to request a replacement."
Travel Notifications
As international travel returns to pre-pandemic levels, travel notification management is a critical UX touchpoint:
- Intelligent travel detection: Rather than requiring members to submit travel notifications, use transaction location data to detect travel and ask "Are you traveling?"
- Simple form: If manual notification is needed, require only three fields: destination, departure date, return date. Everything else is optional.
- Recurring traveler profiles: Allow members to save travel profiles (e.g., "Annual trip to Florida") for one-tap future use
- Auto-expire: Travel notifications should auto-expire on the specified return date without requiring member action
Transaction Alerts
Real-time transaction alerts are the backbone of cardholder security confidence. The best alert design follows these principles:
- Immediate push notification: Alerts should arrive within seconds of authorization, not batched and delayed
- Actionable: Each alert should include "Was this you?" with "Yes" and "No" buttons that trigger appropriate follow-up
- Merchant details: Include merchant name, amount, location (map link), and category in the alert
- Customizable thresholds: Allow members to set their own alert preferences: all transactions, transactions over $X, international transactions, online-only transactions
Spending Limits
Giving members control over their card's spending parameters builds trust and prevents fraud:
- Transaction limit: "Set a maximum amount for a single transaction" — useful for parents with authorized user cards for teens
- Daily limit: "Maximum total spend per day"
- Merchant category blocks: "Block transactions at gambling, adult entertainment, and cryptocurrency merchants"
- International block: Separate toggle for international transaction authorization
- Online-only toggle: Option to restrict the card to in-person chip/contactless transactions only, preventing card-not-present fraud
Dispute Resolution UX: Turning a Pain Point into a Trust Signal
Dispute resolution is simultaneously the most stressful member interaction with their credit card and the most powerful trust-building opportunity a credit union has. According to Finder.com research, the most common credit card complaint in 2025 was "an unknown purchase appearing on the card" (31% of complaints). How the credit union handles this moment defines the member's perception of the institution.
In-App Dispute Initiation
The member should never have to call a phone number to dispute a transaction:
- Two-tap initiation: From any transaction in the activity list, a "Report a problem" or "Dispute" action should be available. Tap it, select the reason from a short list (I didn't make this purchase / Wrong amount / Duplicate charge / Item not received / Other), and submit.
- Transaction context preserved: The dispute form should auto-populate with the transaction details — merchant, amount, date — so the member only has to explain why they are disputing
- Guided resolution: Before submitting a formal dispute, offer "Quick resolution" options where appropriate. For duplicate charges: "Tap to report a duplicate. We'll credit the duplicate immediately and investigate."
- Clear timeline: "We'll issue a provisional credit within 5 business days and resolve this within 30 days." Show a progress tracker for the dispute lifecycle.
Dispute Status Tracking
Once a dispute is filed, the member should never have to wonder what is happening:
- Dedicated disputes center: A "Disputes" section in the card management area showing all open and resolved disputes
- Status updates via push: Automatically notify the member at each stage: filed, under investigation, provisional credit issued, resolution reached
- Document upload: Allow members to upload supporting documents (receipts, correspondence) directly to the dispute case
- Resolution summary: When resolved, show a clear summary of what happened and what action was taken
Fraud Prevention Communication
Proactive fraud prevention communication builds trust before problems occur:
- Fraud protection overview: A dedicated card security page explaining zero-liability protection, how fraud monitoring works, and what to do if the card is compromised
- Social engineering warnings: In-app education about common scams targeting credit card holders — phishing, vishing, smishing — with realistic examples
- Post-dispute confidence: After a dispute is resolved in the member's favor, send a follow-up: "We resolved your dispute and the charge was removed. Your card remains protected. Here's how to stay safe."
Mobile-First Design Patterns for Credit Card Management
Over 65% of credit card management interactions now occur on mobile devices, according to J.D. Power data. Every aspect of the credit card digital experience must be designed for the smartphone form factor first, with responsive desktop adaptation as a secondary concern.
Thumb-Zone Information Architecture
The most important actions for a credit card — view balance, make a payment, lock the card, see rewards — must be within easy thumb reach on the main card screen. This means:
- Bottom navigation: Place primary actions (Pay, Lock, Rewards, Dispute) in a persistent bottom bar or floating action button
- Priority card summary: The top half of the card screen should show the glanceable essentials: current balance, available credit, minimum payment due, and payment due date
- Scrolling activity: Below the summary, a scrollable transaction list with infinite scroll or pagination
- Quick actions card: A horizontally scrollable row of action cards: "Make a Payment," "View Rewards," "Card Controls," "Report a Problem"
Card Visualization
Show the physical card as a visual element that the member can interact with:
- Card image: A realistic rendering of the card (front and back) that the member can flip with a tap
- Card art customization: Allow members to choose from available card designs, making the product feel personal
- Digital card reveal: A "Show card details" option that reveals the full card number, CVV, and expiration date with an animated card flip, complete with auto-dismiss after 30 seconds for security
Progressive Disclosure for Complex Actions
Credit card management involves some inherently complex operations — setting up auto-pay, filing a dispute, understanding interest calculations. Progressive disclosure prevents overwhelming the member:
- Start simple, offer depth: Auto-pay setup starts with "Pay full balance on due date from my primary checking" as a one-tap option, with "Customize" revealing additional options
- Just-in-time education: Show tooltips or short explanations at the point of need: "What is APR?" appears as a small info icon next to the APR display, not as a FAQ page buried in settings
- Save-and-resume: For multi-step processes (disputes, credit limit increases, balance transfers), allow the member to save progress and resume later
Accessibility and Inclusive Design for Cardholder Portals
WCAG 2.2 AA compliance is not optional for credit union digital credit card experiences. With over 4,600 ADA lawsuits filed against websites in 2025 (Seyfarth Shaw data), and the Department of Justice's continued emphasis on digital accessibility, credit unions must ensure their card management portals are usable by members with visual, motor, cognitive, and hearing disabilities.
Visual Accessibility
- Color contrast: All card management interfaces must meet WCAG 2.2 AA contrast ratios (4.5:1 for normal text, 3:1 for large text). The rewards dashboard, spending charts, and transaction lists are common failure points.
- Screen reader compatibility: Transaction lists must be properly marked up with ARIA roles. "Pay now" buttons, "Lock card" toggles, and rewards values must communicate their state programmatically.
- Alternative text for card images: The card visualization must include meaningful alt text: "GrafWeb Credit Card — Platinum Visa — ending in 1234 — Active"
- Zoom support: All interfaces must remain functional at 200% zoom without horizontal scrolling or content cutoff
Cognitive Accessibility
- Plain language: Replace jargon ("APR," "credit utilization ratio," "revolving balance") with plain-language equivalents or in-context definitions
- Financial literacy support: For members with lower financial literacy, offer guided experiences: "Let us help you choose a payment amount" with clear explanations of minimum payment vs. full balance tradeoffs
- Error prevention: Before submitting a payment or dispute, show a clear summary screen: "You're about to pay $1,247 from your checking account ending in 4567. Does this look right?"
- Consistent navigation: Maintain consistent placement of card management actions across the mobile app and online banking. A member should not have to re-learn navigation patterns between devices.
Motor Accessibility
- Large touch targets: All interactive elements (buttons, toggles, links) must be at least 44x44px (ideally 48x48px) for easy tapping
- Gesture alternatives: Swipe-based card navigation or gesture-based actions require fallback tap-based alternatives
- Extended timeouts: Session timeouts should provide at least 20 seconds of warning before expiring, with options to extend
- Voice input support: Enable voice dictation for dispute descriptions and other free-text fields
AI-Driven Personalization for Credit Card Experiences
Artificial intelligence is transforming how credit unions can personalize the credit card experience without requiring massive technology teams. The key is focusing on high-impact, achievable personalization patterns rather than attempting to replicate Amazon-level recommendation engines.
Spending Pattern Personalization
- Intelligent category surfacing: Show the member the spending categories most relevant to their behavior. A member who frequently dines out should see dining insights prominently; a member who rarely dines out should not.
- Personalized rewards recommendations: Based on spending patterns, suggest redemption categories the member would find most valuable: "You spent $340 on gas last month. Consider our Gas Rewards card for 3% back on fuel."
- Spending anomaly detection: "Your spending at home improvement stores is 3x higher than usual. Are you planning a renovation? We have a Home Improvement Loan offer that might save you money."
Predictive Payment Reminders
Rather than sending the same reminder to every member at the same interval, AI can personalize payment reminders based on individual behavior patterns:
- Payment timing prediction: For members who typically pay 2-3 days before the due date, send reminders 4 days before. For members who have missed payments in the past, send reminders 7 days before with a stronger call to action.
- Channel optimization: Send reminders via the member's preferred channel — push notification for app users, SMS for text-first members, email for desktop-oriented members
- Balance-sensitive messaging: For members carrying a high balance relative to their limit, include educational content about interest savings from paying more than the minimum
Life Event Card Personalization
Major life events trigger changes in spending patterns and credit needs:
- New cardholder: In the first 90 days, emphasize activation, mobile wallet enrollment, and first purchase with targeted onboarding content
- Traveler: When the member's transaction pattern suggests travel (airline purchases, hotel bookings), surface travel notifications and foreign transaction fee information
- High spender: For members consistently nearing their credit limit, offer credit limit increase pre-approvals and balance transfer options
- Dormant card: For cards that have not been used in 90+ days, send re-engagement communications highlighting the card's benefits or an incentive offer
Implementation Roadmap
Implementing a comprehensive digital credit card experience does not require a ground-up rebuild. The following phased approach allows credit unions to make meaningful improvements incrementally.
Phase 1: Foundation (Weeks 1-8)
Goal: Deliver the basics with minimal friction.
- Redesign the card detail screen with glanceable balance, available credit, and minimum payment due
- Implement one-tap card lock/unlock with instant processor propagation
- Add real-time push notification transaction alerts with merchant details and "Was this you?" actions
- Simplify auto-pay setup to a single-screen flow with three options (minimum, full, custom)
- Deploy in-app dispute initiation with two-tap flow and auto-populated transaction context
Phase 2: Rewards and Intelligence (Weeks 9-16)
Goal: Make points visible, valuable, and actionable.
- Add always-visible points balance to the accounts dashboard and card detail screen
- Launch a rewards dashboard with points balance, earning history, category breakdown, and redemption options
- Implement one-tap statement credit redemption
- Add transaction categorization with merchant logos and category summaries
- Launch basic spending insights: monthly spend comparison, top categories, recurring subscription detection
Phase 3: Security and Controls (Weeks 17-24)
Goal: Give members comprehensive self-service security controls.
- Add travel notifications with intelligent detection and auto-expire
- Implement spending limits per transaction, per day, per category, and by geography
- Launch digital card issuance (virtual card at approval) and mobile wallet deep-linking
- Add card detail reveal with auto-dismiss security timer
- Launch fraud protection education center with in-app security tips
Phase 4: Personalization and Optimization (Weeks 25-36)
Goal: Deliver tailored experiences that deepen the member relationship.
- Implement AI-driven spending pattern personalization and personalized rewards recommendations
- Add predictive payment reminders with channel optimization
- Launch life event triggers for targeted cardholder communication
- Implement card art customization options
- Deploy automated A/B testing framework for card management UX optimization
Small Credit Union Strategies
Credit unions with under $250 million in assets face unique challenges in delivering sophisticated digital card experiences. However, several strategies can help small credit unions compete:
Leverage Card Processor Capabilities
Most credit union card processors (Elan, PSCU, CO-OP, Fiserv) offer API-level access to card management features: card status changes, transaction data, rewards balances, and digital issuance. Before building custom solutions, audit what your processor already provides. Many offer white-label mobile wallet enrollment and virtual card issuance that simply needs to be surfaced in the credit union's app.
Platform-First Approach
Rather than building custom credit card management screens, leverage the capabilities of your digital banking platform. Most modern platforms (Jack Henry Banno, NCR Digital Insight, Q2, Alkami) have card management modules that can handle 80%+ of the functionality described in this playbook. Focus custom development on the 20% that differentiates your credit union — typically rewards visualization, spending insights, and dispute resolution UX.
CUSO Shared Services
Card Services CUSOs can provide shared infrastructure for rewards programs, fraud monitoring, and digital card issuance that no single small credit union could afford independently. Evaluate CUSO partnerships that bundle card processing with digital experience enhancements.
Phased Investment
Small credit unions should prioritize the highest-impact, lowest-cost improvements first: one-tap card lock, transaction alerts, simplified auto-pay setup, and basic rewards visibility. These four features alone address the most common member pain points and can be implemented within existing platform capabilities for minimal incremental cost.
Key Performance Indicators
Measuring the impact of credit card digital experience improvements requires a balanced scorecard across five dimensions:
Adoption and Usage
- Digital activation rate: Percentage of new cards activated via digital channel (target: >80%)
- Mobile wallet enrollment rate: Percentage of active digital cards enrolled in Apple Pay/Google Pay (target: >50%)
- Auto-pay enrollment rate: Percentage of cards with auto-payment configured (target: >40%)
- App login frequency: Average number of card management app sessions per month (target: >4x)
Engagement
- Rewards dashboard views: Percentage of cardholders who view rewards in a 30-day period (target: >30%)
- Redemption rate: Percentage of earned points redeemed annually (target: >60%)
- Spending insights interaction: Click-through rate on spending insight cards (target: >15%)
- Card control usage: Percentage of cardholders who have used lock/unlock or travel notifications (target: >20%)
Operational Efficiency
- Digital dispute initiation rate: Percentage of disputes initiated via digital channel vs. phone (target: >60%)
- Self-service card lock rate: Percentage of lost/stolen card events handled via self-service lock (target: >70%)
- Call deflection: Reduction in card-related call center volume attributable to digital self-service (target: >25%)
Satisfaction and Retention
- Cardholder satisfaction (CSAT): Post-interaction survey score for card management experiences (target: >4.0/5.0)
- Primary card usage: Percentage of cardholders who use the credit union's card as their primary card (target: >60%)
- Card churn rate: Annual card closure rate (target: <10%)
- Net Promoter Score (NPS): Card-specific NPS compared to overall credit union NPS (target: card NPS > overall NPS)
Financial Performance
- Interchange revenue per active card: Average monthly interchange income (target: benchmarking against card processor peer group)
- Interest income per revolver: Average monthly interest income from cardholders carrying a balance (target: tracking trend over time)
- Cross-sell conversion: Credit card holders who add deposit accounts, loans, or other credit union products (target: >25%)
Future Trends in Credit Card Digital Experiences
Looking ahead to 2027 and beyond, several emerging trends will reshape credit union credit card digital experiences:
Tokenized Digital Card Issuance
The physical plastic card is rapidly becoming optional. Tokenized digital cards — unique card numbers generated for each mobile wallet or merchant — offer superior security and instant issuance. Credit unions that implement tokenized digital card issuance at the point of approval will eliminate the 7-10 day waiting period entirely, matching the Apple Card and SoFi experience.
AI-Powered Fraud Prevention
Next-generation fraud detection uses real-time behavioral analytics and machine learning to identify fraudulent transactions with far greater accuracy than traditional rules-based systems. The key UX implication: fewer false positive declines mean fewer friction points for legitimate members while maintaining or improving fraud prevention effectiveness.
Embedded Credit Card Experiences
Credit card management is moving beyond the banking app into the contexts where members actually use their cards: checkout flows, merchant apps, digital wallets, and even in-car payment systems. Credit unions need to ensure their card management capabilities are accessible via APIs so that members can lock a card, check a balance, or view rewards without navigating back to the credit union's app.
Open Banking and Data Portability
Section 1033 of the Dodd-Frank Act, as implemented by the CFPB, will require financial institutions to make consumer financial data available via standardized APIs. For credit cards, this means members will be able to authorize third-party apps to access transaction data, rewards balances, and card terms. Credit unions should proactively prepare by building well-documented, secure APIs for card data access, turning regulatory compliance into a competitive advantage.
Voice and Conversational Card Management
Voice-activated card management — "Lock my credit card," "What's my current balance?" "How many rewards points do I have?" — is becoming a standard expectation. Credit unions should integrate card management commands into their existing IVR and voice assistant capabilities, ensuring natural language understanding covers the most common cardholder inquiries.
Personalized Card Benefits Communication
Beyond rewards points, credit cards offer a wealth of benefits that most members never use or even know about: purchase protection, extended warranty, travel insurance, rental car collision coverage, price protection, and return protection. AI-driven personalization can surface the most relevant benefits based on the member's spending patterns: "You purchased a laptop last week. Your card includes extended warranty coverage — no enrollment needed. Tap to learn more."
Conclusion
The credit card digital experience is one of the most important yet underinvested areas of credit union digital banking. While credit unions have focused enormous energy on digital account opening, mobile check deposit, and person-to-person payments, the everyday experience of managing a credit card has been treated as a commodity feature rather than a strategic differentiator.
This is a mistake. Credit cards are the most frequently used financial product for millions of members. Every transaction generates a notification or statement entry. Every month brings a payment decision. Every year brings rewards redemption choices. These high-frequency, high-engagement touchpoints represent an ongoing opportunity to demonstrate the credit union's value, build trust, and deepen the member relationship.
The credit unions that will win in 2027 and beyond are those that treat the credit card digital experience as a product in its own right — designed with the same care, attention to detail, and member-centric thinking that they apply to their mobile app, website, and branch experience. The strategies outlined in this playbook — from instant digital card issuance and one-tap mobile wallet enrollment to intelligent rewards dashboards and AI-powered personalization — provide a roadmap for transforming the credit card from a commodity product into a relationship anchor.
Credit unions do not need to outspend Chase or Capital One. They need to out-execute them on the digital moments that matter most to their members. When a member can activate their card in 10 seconds, see their rewards grow in real-time, lock their card in one tap, resolve a dispute without a phone call, and receive personalized spending insights that actually help them manage their finances — they will not just keep that card. They will make it their primary card. And they will tell their friends about it.
This article was brought to you by GrafWeb CUSO – Building the future of digital credit unions.
References
- Finder.com — Credit Card Statistics in the United States, 2025
- J.D. Power — 2025 US Credit Card Satisfaction Study
- Baymard Institute — Form Abandonment Research
- Nielsen Norman Group — Cognitive Load and Form Design
- Seyfarth Shaw — ADA Lawsuit Trends in Digital Accessibility, 2025
- W3C — Web Content Accessibility Guidelines (WCAG) 2.2
- Pew Research Center — Mobile Technology Fact Sheet, 2025
- McKinsey & Company — The Personalization Dividend in Financial Services
- Bain & Company — Customer Loyalty in Retail Banking
- Cornerstone Advisors — What's Going on in Banking, 2025
- Filene Research Institute — Credit Union Member Experience Research
- Federal Reserve — Payments Study and Consumer Credit Data
- Consumer Financial Protection Bureau — Credit Card Regulations
- CUNA — Credit Union Member Demographics and Credit Card Trends
- FIS — Digital Banking and Credit Card Innovation Report
- NerdWallet — Credit Card Research and Consumer Data
- CreditCards.com — Credit Card Industry Statistics
- Bankrate — Credit Card Rate and Fee Research
- Apple Inc. — Apple Card Digital Experience Design
- Fintech Futures — Emerging Trends in Digital Card Experiences, 2026
Request a proposal from GrafWebCUSO · (201) 632-1771 · [email protected]