
Introduction: The P2P Payment Revolution and the Credit Union Opportunity
Person-to-person (P2P) payments have fundamentally reshaped how Americans move money between one another. What began as a convenience feature has evolved into a core banking expectation, particularly for members under 45. Venmo, Cash App, and Zelle now process hundreds of billions of dollars annually, and the adoption trajectory shows no signs of deceleration. For credit unions, the P2P payment experience represents both an existential threat and a strategic opportunity.
The threat is straightforward: when a member's primary money movement happens through a Venmo or Cash App account rather than their credit union's digital banking platform, the credit union relationship weakens. The member's daily financial interactions — splitting dinner bills, paying the babysitter, reimbursing a coworker — occur outside the credit union's ecosystem, reducing engagement, diminishing the credit union's role in the member's financial life, and increasing the likelihood that the member will eventually move their direct deposit and loan business to the fintech or neobank that processes their P2P transactions.
📑 Table of Contents
- Introduction: The P2P Payment Revolution and the Credit Union Opportunity
- The Competitive Landscape: Venmo, Cash App, Zelle, and Why Credit Unions Must Act Now
- Zelle Integration: The Essential P2P Infrastructure for Credit Unions
- Designing the P2P Send Flow: From Contact Selection to Confirmation
- Request and Split Payment UX Design: Making Group Expenses Effortless
- Mobile-First P2P Interface Design Patterns
- P2P Security and Fraud Prevention UX: Building Trust in Digital Money Movement
- P2P Onboarding and First-Use Experience: Driving Adoption from Day One
- Notification and Receipt Architecture: Keeping Members Informed
- P2P for Business Members and Shared Accounts
- Accessibility and Inclusive P2P Design
- Regulatory Compliance for P2P Payments
- Small Credit Union Strategies for P2P Success
- KPI Framework for P2P Payment Success
- 90-Day P2P Implementation Roadmap
- Future Trends in P2P and Embedded Payments
- Conclusion
- References
The opportunity is equally compelling. Credit unions that invest in a seamless, intuitive, and trusted P2P payment experience — particularly through Zelle integration, which reaches over 2,400 financial institutions — can recapture those daily financial interactions, deepen member relationships, and position themselves as the primary financial institution for a generation that expects instant, mobile-first money movement. Data from Cornerstone Advisors consistently shows that 47% of consumers under 40 would switch their primary banking relationship for a better digital experience, and P2P payment functionality is one of the most frequently cited deal-breakers in digital banking satisfaction surveys (Cornerstone Advisors, 2025).
This comprehensive playbook covers every dimension of credit union P2P payment UX and UI design: from foundational Zelle integration architecture through the nuances of split payment flows, request interfaces, mobile-first design patterns, security UX, member education, regulatory compliance, and a 90-day implementation roadmap. Whether your credit union already offers Zelle and needs to optimize the experience, or you are evaluating P2P strategy for the first time, this guide provides the detailed, research-backed framework you need to compete effectively with Venmo, Cash App, and neobank P2P experiences.
The Competitive Landscape: Venmo, Cash App, Zelle, and Why Credit Unions Must Act Now
The Three-Headed P2P Market
The U.S. P2P payment market is dominated by three major platforms, each with distinct strengths, user demographics, and integration models that credit unions must understand to develop an effective competitive strategy.
Venmo, owned by PayPal, pioneered the social P2P experience with its signature newsfeed-style transaction feed, emoji-laden payment notes, and social interactions. With an estimated 85 million active users as of 2026, Venmo is the dominant P2P platform among Millennials and Gen Z. Its social feed feature — where payments are shared with friends (or the public) — transformed money movement from a private utility into a social experience. Venmo's weakness for credit unions is its business model: Venmo makes money through instant transfer fees, debit card interchange, and merchant payment processing, and it has increasingly positioned itself as a full-featured financial services platform with Venmo Credit Card, Venmo Savings, and cryptocurrency trading — making it a direct competitor for credit union member relationships rather than just a payment utility.
Cash App, owned by Block (formerly Square), has approximately 55 million monthly active users and has differentiated itself through deep integration with Bitcoin trading, stock investing, and direct deposit functionality. Cash App's $Cashtag system — where users claim a unique identifier (@username) for receiving payments — eliminated the need to share phone numbers or email addresses, reducing a significant friction point in P2P transactions. Cash App has been particularly aggressive in targeting underbanked consumers and younger users who may not have traditional bank accounts, offering early direct deposit access, free ATM withdrawals at specific limits, and a debit card that functions as a full replacement for a traditional checking account.
Zelle, owned by Early Warning Services (a consortium of major U.S. banks), takes a fundamentally different approach. Rather than building a standalone app with social features, Zelle operates as an infrastructure layer embedded directly within financial institution mobile banking apps. Zelle does not hold funds, does not create a separate account, and does not add social features — it simply moves money between bank accounts in minutes. Zelle's integration with over 2,400 financial institutions — including many credit unions — means that it reaches more consumers than any standalone P2P app, with an estimated 130 million consumers having access through their banking app (Zelle / Early Warning Services, 2026). Zelle's transaction volume surpassed $800 billion in 2025, growing at over 25% annually.
The Credit Union P2P Reality
For credit unions, Zelle is the natural P2P partner. It integrates directly into existing digital banking platforms, enables instant settlement between enrolled users, requires no account funding step (transfers come directly from the member's checking account), and carries the trust and security of the credit union brand rather than a fintech intermediary. However, many credit unions have struggled with Zelle adoption and member satisfaction due to suboptimal UX design: buried navigation, confusing enrollment flows, unclear fee structures, and lackluster request and split payment experiences.
The stakes of getting P2P right have never been higher. According to the Federal Reserve's 2025 Payments Study, P2P transaction volume in the United States grew 28% year-over-year, with over 12 billion P2P payments processed in 2025 alone (Federal Reserve Payments Study, 2025). Pew Research data indicates that 78% of smartphone users under 50 have used a P2P payment app, and among 18-29 year olds, P2P payment usage is nearly universal at 91% (Pew Research Center, 2025). Yet credit unions capture only a fraction of this volume — most P2P transactions among credit union members still flow through Venmo and Cash App, representing lost engagement opportunities and weakening member relationships.
The win for credit unions is clear: a superior integrated Zelle experience — one that is faster, more intuitive, better designed, and more trusted than the standalone apps — can recapture P2P transaction volume, increase mobile banking engagement, drive primary financial institution status, and create natural opportunities for cross-selling additional products. The remainder of this playbook provides the detailed UX/UI guidance to make that vision a reality.
Zelle Integration: The Essential P2P Infrastructure for Credit Unions
Understanding Zelle's Integration Model
Zelle offers two primary integration paths for credit unions, and the choice between them has significant UX implications that affect everything from enrollment flow design to transaction speed and member communication.
Zelle Pay (Standard Integration): The standard integration allows credit unions to embed Zelle functionality within their existing mobile banking app. Members enroll by verifying their U.S. mobile number or email address, which becomes their Zelle identifier. Transactions between enrolled Zelle users typically complete within minutes, and funds settle directly into the member's checking account — no holding account or transfer step required. The credit union controls the branding, the UI, and the member experience, with Zelle operating as a backend clearing and settlement network. For most credit unions, this is the recommended integration path because it maintains the member within the credit union's digital ecosystem, reinforces the credit union brand, and allows full control over UX design.
Zelle Partners (Lite Integration/Third-Party): Some smaller credit unions, particularly those with limited core integration capabilities or older digital banking platforms, may use Zelle through a third-party partner that handles the technical integration. In this model, the member may be redirected to a co-branded or partner-branded interface for some P2P flows, which introduces UX fragmentation and potential abandonment. Credit unions using this model should work closely with their partner to minimize visual and functional dissonance, ensuring that the P2P experience still feels like part of the credit union's digital banking platform.
Core Integration Requirements
Regardless of the integration path, credit unions should ensure the following core Zelle integration capabilities are in place before designing the member-facing experience:
Real-time enrollment enrollment: Members should be able to enroll in Zelle directly from the P2P send flow without leaving the transaction context. A separate enrollment flow — where members must navigate away, enroll, and return — creates unnecessary friction and abandonment. The enrollment step should be a lightweight, inline experience that captures the member's mobile number or email, sends a one-time verification code, and immediately enables P2P sending capability.
Contact discovery: The Zelle network can identify enrolled contacts from the member's phone's contact list. This discovery should surface automatically during the send flow, showing which contacts are already enrolled in Zelle (and can receive instant payments) versus those who need to be invited. Visual distinction between enrolled and unenrolled contacts is critical for managing member expectations about delivery speed.
Transaction limits and fee transparency: Zelle transactions have dollar limits that vary by financial institution. These limits must be communicated clearly at the transaction point (not buried in fine print), and members should be informed when a transaction exceeds available limits before they complete the send flow. Fees — which most credit unions do not charge for standard Zelle transactions — must be disclosed transparently per Reg E requirements.
Integration with account selection and balance display: The P2P send flow must integrate cleanly with the member's existing accounts, showing the sending account balance and enabling account switching without leaving the send flow. For members with multiple checking accounts, the ability to select the sending account at the point of transaction is essential.
Designing the P2P Send Flow: From Contact Selection to Confirmation
The Four-Stage Send Flow Architecture
A well-designed P2P send flow follows a clear, progressive four-stage architecture that minimizes cognitive load at each step while maintaining forward momentum toward completion. Each stage has specific UX requirements, interaction patterns, and success metrics.
Stage 1: Recipient Selection. The recipient selection stage is the first and most critical interaction in the P2P send flow. Members should be able to select a recipient by any of the following methods, with all options available at the top of the selection screen: recent contacts (automatically surfaced from transaction history), contact list import (phone contacts with Zelle enrollment status), direct entry of email or mobile number, and Zelle Tag search (a vanity identifier like @username). The recipient selection screen should prioritize speed: the most frequently used contacts should appear first, enrolled contacts should be visually distinguished from unenrolled ones, and search should return results instantly with fuzzy matching. A common anti-pattern is requiring members to choose a method first (e.g., "Select from contacts or enter manually") before seeing any options — this adds an unnecessary decision step. Instead, present all methods in a unified interface with the contact list as the primary option and a prominent "Send to someone new" entry point.
Stage 2: Amount Entry. The amount entry screen should be a dedicated, distraction-free input with a numeric keypad (not a text input, which forces the device keyboard). Key requirements include: large, prominently displayed digit entry with comma separators for thousands; a memo/note field that defaults to the previous transaction note to the same recipient; the ability to split a predefined amount (if the member is responding to a payment request); and real-time balance display that updates as the member types. The amount entry screen is also the appropriate place to display transaction limits — show both the remaining daily limit and the available balance, with the send button enabled only when the entered amount is within both constraints.
Stage 3: Confirmation and Review. The confirmation screen presents a complete summary of the transaction before final execution. This should include: recipient name and identifier (partially masked email/phone for privacy), amount and sending account, delivery speed estimate (e.g., "Arrives in minutes" for enrolled recipients, "They need to enroll" for unenrolled), a prominent edit button for each field, and the final send button with clear action text ("Send $50.00" rather than just "Send"). The confirmation screen serves dual purposes: it reduces errors by forcing deliberate review, and it builds trust through transparency about what is happening and when the money will arrive.
Stage 4: Result and Next Actions. The result screen is often treated as an afterthought but is critical for member satisfaction and engagement. After a successful send, display a clear success animation or state change, the transaction amount and recipient, the estimated delivery time, and contextual next actions. For an enrolled recipient: "Sent! Your $50.00 to Sarah should arrive within minutes." For an unenrolled recipient: "Notification sent! Sarah has 14 days to enroll and claim the payment." Contextual next actions should include: "Send to someone else," "Request from someone," "View transaction in activity," and "Add to favorites" (if the recipient is new). This screen is also the ideal moment to offer additional services: "Track this payment" or "Set up recurring payments to [recipient]."
Managing the Unenrolled Recipient Experience
One of the most challenging UX problems in credit union P2P design is the experience of sending money to someone who is not yet enrolled in Zelle. The current standard — sending a notification that directs the unenrolled recipient to download the sender's credit union app and enroll — introduces significant friction and delivery uncertainty. The recipient must: receive the notification (SMS or email), follow a link, potentially download an app, go through enrollment, find the payment, and claim it — all within 14 days or the payment expires and reverses.
Best practice design patterns for the unenrolled recipient flow include: clear up-front communication before the send confirming that the recipient is not enrolled and explaining what will happen, simplified recipient enrollment that directs to a lightweight web enrollment rather than requiring a full app download (Zelle's open enrollment option), proactive sender notification when the recipient has enrolled and claimed the payment, a clear expiration countdown, and automated reminder notifications as the 14-day window closes. Credit unions should also consider offering an alternative send method — such as a one-time ACH or wire transfer — when the P2P recipient enrollment barrier is prohibitive, particularly for larger amounts.
Request and Split Payment UX Design: Making Group Expenses Effortless
The Request Payment Flow
Payment requests — where a member asks another person to send them money — are a surprisingly under-designed feature in many credit union P2P implementations. Yet request flows represent a significant engagement opportunity: members who request payments are typically organizing group expenses (dinner parties, group gifts, shared bills), and a smooth request experience builds loyalty and creates recurring transaction patterns.
The request flow follows the same four-stage architecture as the send flow, with critical differences at each stage. In the recipient selection stage, the member selects who to request from rather than who to send to — this is a subtle but important mental model shift that should be reflected in the interface language. The amount entry stage should include split functionality by default: "Split evenly among X people," "Split by custom amounts," or "Request full amount from each person." The request confirmation should clearly say "You're requesting $XX.XX from [name]" rather than sending. And the result screen should show the request in a pending state with the ability to send a reminder, cancel the request, or track whether the recipient has paid.
Group split functionality particularly deserves careful UX attention. When a member wants to split a dinner bill of $156.47 among four friends, the interface should make this effortless. Best-in-class split UIs allow: entering the total amount and the number of splits for automatic per-person calculation, adding individual line items to specific people, removing specific items or people from the split, selecting who covers tax and tip, and sending all split requests simultaneously. The Cash App split experience — where users can photograph a receipt and tap items to assign them to specific people — represents the current gold standard that credit unions should study and adapt to their own UX patterns.
Request management deserves its own dedicated section within the P2P experience. Members should be able to: view all pending requests (both sent and received), see request status (paid, pending, expired), send reminders automatically after configurable intervals, cancel their own requests, and dispute a request they believe is incorrect. A poorly designed request management experience — where requests disappear into a transaction history black hole — erodes trust and reduces future request engagement.
Mobile-First P2P Interface Design Patterns
P2P payments are, by their nature, a mobile-first activity. The vast majority of P2P transactions occur on smartphones — often while someone is standing in a store, sitting at a restaurant table, or responding to a last-minute request from a friend. The P2P interface must be optimized for these contexts: one-handed operation, quick interactions, minimal typing, and instant feedback.
Bottom sheet send flow: Rather than navigating to a separate page, the send flow should open as a bottom sheet overlay on the mobile banking dashboard or account detail page. This keeps the member in context — they can see their balance and recent transactions while entering payment details — and reduces the perception of leaving the banking app to use a separate feature. The bottom sheet should expand progressively as the member advances through the four-stage flow.
Thumb-zone optimized layout: All primary interaction elements — the numeric keypad, the send button, contact selection — should be positioned within the thumb zone (the lower two-thirds of the screen for one-handed operation). The confirmation summary, amount display, and recipient name function as read-only information that can live in the upper zone where thumbs naturally rest when not actively tapping.
Gesture-based interactions: Power users will appreciate gesture-based shortcuts: long-pressing a contact to send a predefined amount, swiping right on a recent transaction to repeat it, or shaking the phone to undo a recently completed transaction (similar to Cash App's shake-to-undo feature). These gesture patterns are not discoverable by design — they should be introduced through contextual tooltips on first use and an optional tutorial flow.
Quick amounts and favorites: The amount entry screen should surface quick-amount buttons ($10, $20, $50, $100) that appear after the member selects a recipient with a prior transaction history. Members who frequently send $25 to their child for allowance or $50 to their weekly lunch group should be able to complete the transaction in under 10 seconds: select contact, tap $50, confirm. The favorites feature — where members can designate specific contacts as favorites for one-tap sending — is particularly valuable for recurring P2P relationships.
Context-aware suggestions: When a member opens the P2P flow, the system should use context to reduce friction. If the member received a payment request notification and taps it, the flow should pre-populate the recipient and amount. If the member typically sends money to their spouse every Friday for groceries, the flow could surface that contact with "Send $200?" as a suggestion on Friday mornings. These context-aware patterns — powered by transaction history analysis — transform P2P from a multi-step task into a near-instant operation.
Dark mode and visual accessibility: The P2P interface must support the member's system-wide dark mode settings and provide sufficient color contrast for outdoor use (bright sunlight is the most common environment for mobile P2P transactions). The numeric keypad should have high-contrast key borders, the send button should have clear visual feedback on press, and all status indicators (success, pending, failed) should use both color and iconography to support colorblind members.
P2P Security and Fraud Prevention UX: Building Trust in Digital Money Movement
Security concerns are the single biggest barrier to P2P adoption among credit union members, particularly older members who may be wary of digital money movement. The Federal Trade Commission reported over $10 billion in fraud losses in 2025, with P2P payment scams — including fake payment requests, account takeover, and social engineering — accounting for a growing share (FTC Consumer Sentinel Network, 2025). Credit unions have a trust advantage over standalone fintechs in this dimension, but that advantage must be operationalized through thoughtful security UX design, not simply assumed.
In-Flow Security Patterns
Recipient verification nudges: When a member attempts to send money to a new recipient, the interface should add a lightweight verification step that does not break flow but does force deliberate action. This could be a simple prompt: "Sending to [name] for the first time. This phone number was registered 3 days ago. Send anyway?" or a confirmation dialog that requires the member to type CONFIRM or SEND to proceed.
Amount-based friction escalation: Security friction should scale proportionally with transaction risk, not uniformly. For small, routine transactions to frequent contacts — such as sending $20 to a family member who has been a recipient for years — the flow should be nearly frictionless. For large transactions, new recipients, or unusual transaction patterns, additional verification steps should activate: biometric confirmation, one-time passcode verification, or even a short wait period (Cash App's "security hold" for suspicious transactions). This graduated security model balances convenience with protection.
Fraud education at teachable moments: The moment a member sends money to a new recipient for the first time is a teachable moment for fraud prevention. Instead of a generic, dismissible security warning, provide context-specific education: "You're sending money to someone you haven't paid before. Remember: only send money to people you know and trust. Zelle payments to enrolled recipients are typically instant and cannot be reversed." This targeted education — delivered when it's most relevant — is significantly more effective than general fraud prevention content buried in the help center.
Transaction reversal communication: One of the most significant UX challenges in Zelle is managing expectations about transaction reversibility. Zelle payments are typically irreversible once sent to an enrolled recipient — there is no chargeback mechanism like credit cards. The interface must communicate this clearly before the member confirms the transaction, but in a way that does not create unnecessary anxiety. The pattern should be: "This payment will arrive in minutes and typically cannot be canceled. Please confirm the recipient and amount." This sets appropriate expectations without implying that Zelle is fundamentally unsafe.
Push notification for transaction confirmation: After a P2P transaction completes, the member should receive an immediate push notification with transaction details, reducing the anxiety of "Did that go through?" and providing a natural mechanism for fraud detection (members can immediately see transactions they did not authorize). These notifications should include: recipient name, amount, timestamp, remaining balance, and a direct link to transaction details or dispute initiation.
P2P Onboarding and First-Use Experience: Driving Adoption from Day One
For many credit union members, Zelle P2P will be a feature they discover — or don't discover — on their own within the mobile banking app. Passive discovery often leads to low adoption rates: members simply do not know the feature exists, or they are uncertain about how it works and default to the familiar Venmo or Cash App experience. A proactive onboarding strategy is essential for driving P2P adoption.
The First-Use Sequence
Discovery and entry points: P2P should have multiple, persistent entry points throughout the mobile banking experience: a prominent "Send Money" button on the dashboard, an entry within the account detail page for checking accounts, a quick action in the navigation bar, and contextual prompts within transaction activity (e.g., "Send money to Sarah" when viewing a recent Venmo transaction imported through account aggregation). The entry point should never be buried in a settings menu or behind a "More" overflow — P2P is a top-tier mobile banking feature that deserves top-tier placement.
First-time enrollment as progressive onboarding: When a member taps "Send Money" for the first time, the enrollment flow should be framed as a simple, low-commitment step rather than a heavyweight registration process. The messaging should emphasize speed and ease: "Send money to anyone with just their email or phone number. Let's get you set up in under 30 seconds." The enrollment should require only: accepting the Zelle terms of service, entering or confirming a mobile number, verifying the number via SMS code (automated, not manual), and choosing whether to also enroll an email address. This should take no more than three screens with clear progress indication.
First-send guided flow: The first P2P transaction after enrollment should include gentle guidance cues that disappear after the transaction completes: tooltips explaining the contact search, a brief walkthrough of the confirmation screen, and a clear explanation of what happens after the send. These guidance cues should be contextual — appearing only when the member needs them — and should progressively fade as the member gains experience.
Zero-balance confidence building: For members who are hesitant about P2P, offering a small guided test transaction — sending $1 to themselves or a family member — can dramatically increase confidence and subsequent adoption. Pattern this as an optional step: "Want to see how it works? Send $1 to your own email to test the experience." This low-stakes introduction lets members experience the full send flow before they need to use it in a real scenario.
Notification and Receipt Architecture: Keeping Members Informed
The P2P notification architecture must balance two competing objectives: keeping members informed about transaction status without overwhelming them with alerts. A well-designed notification system builds trust through transparency; a poorly designed one creates notification fatigue — and potentially causes members to miss genuinely important fraud alerts.
Send confirmation (immediate, high priority): Every completed send should trigger an immediate push notification with the amount, recipient, and a confirmation message. This notification serves dual purposes: it confirms success and it enables rapid fraud detection. If a member receives a send notification for a transaction they did not authorize, they can immediately tap to dispute it.
Delivery confirmation (event-based): When the recipient claims the payment (if unenrolled) or when the payment lands in their account, the sender should receive a delivery notification. This notification closes the transaction loop and provides the assurance that the money has reached its intended destination.
Request received (immediate, medium priority): When someone requests money from a member, they should receive a notification that includes the requester's name, the amount, and the request memo. The notification action should take the member directly to the send flow with the amount and recipient pre-populated, enabling one-tap payment.
Enrollment invitation status (delayed, low priority): When a member sends money to an unenrolled recipient, they should receive periodic status updates: a reminder after 3 days if the recipient has not enrolled, another at day 7, and a final warning at day 12 that the payment will expire and reverse if not claimed by day 14. These reminders should be actionable (tap to resend notification to recipient) and should not feel like spam.
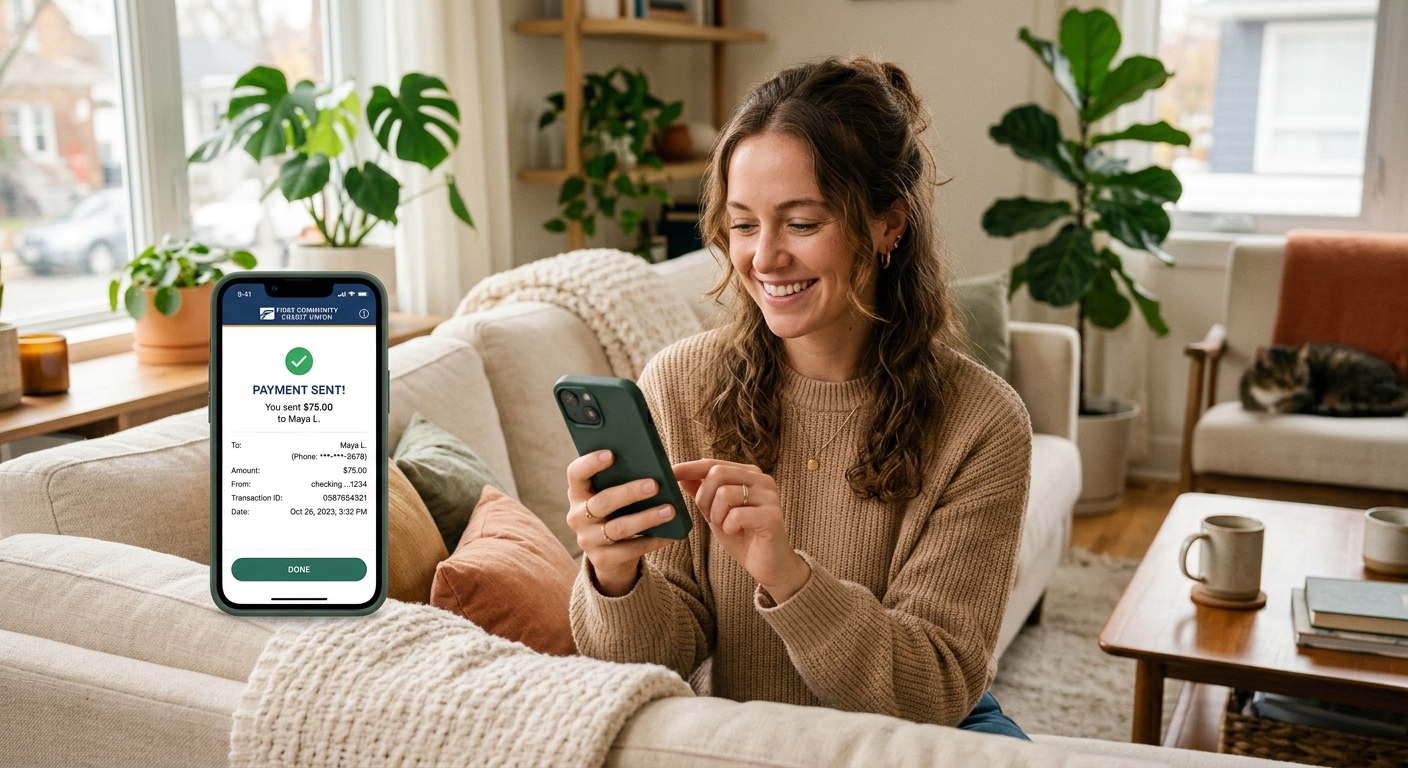
Receipt design: The digital receipt for a P2P transaction should be comprehensive yet scannable: date and time, transaction ID, sending and receiving accounts (partially masked), amount, any fees, delivery method and estimated timing, and the credit union's customer service contact for disputes. The receipt should be available as a downloadable PDF or shareable link for members who need transaction records for expense reporting or shared household accounting.
P2P for Business Members and Shared Accounts
Business P2P payments represent a significant growth opportunity for credit unions that serve small business owners, freelancers, sole proprietors, and entrepreneurs. Zelle for Business offers many of the same features as consumer Zelle but with business-specific requirements around record-keeping, transaction limits, and multi-user access.
Business vs. personal account distinction: Members who use a single checking account for both personal and business transactions need clarity about which Zelle profile they are using for each payment. The interface should clearly label whether the member is sending from their personal or business Zelle profile (if they maintain both), and the transaction activity should filter accordingly.
Invoice and payment request integration: For small businesses, the request payment flow is more important than the send flow. Freelancers and sole proprietors need to request deposits, invoice payments, and project retainers from clients. The P2P interface should support: creating a payment request with a business memo field, recurring request templates for monthly retainers, integration with invoicing tools, and the ability to include a business name (rather than the individual's name) in the payment request.
Higher transaction limits: Business accounts typically need higher P2P transaction limits than consumer accounts. The interface should surface these limits clearly and provide a pathway for requesting temporary limit increases for known upcoming large transactions — for example, a contractor expecting a $10,000 project payment who needs a temporary daily limit increase.
Multi-user access: Small businesses with multiple employees may need delegated access to P2P features: an accountant who can request payments, a project manager who can send supplier payments, a business owner who approves transactions above a threshold. The P2P interface should integrate with the credit union's business digital banking permissions model, respecting role-based access controls within the P2P send and request flows.
Shared accounts — joint checking accounts used by couples, family members, or roommates — present a different set of P2P UX challenges. Both account holders need access to the P2P feature associated with the shared account, but transaction activity must be attributable to the individual who initiated it. The send flow should identify which account holder is sending (useful for joint account reconciliations), and notifications should go to both account holders for transparency.
Accessibility and Inclusive P2P Design
P2P payment interfaces must be accessible to all members, including those with visual, motor, cognitive, and hearing disabilities. WCAG 2.2 AA compliance is the baseline, but truly inclusive P2P design goes beyond compliance to consider the specific accessibility challenges of P2P transactions.
Screen reader compatibility: The P2P send flow — contact selection, amount entry, confirmation, and result — must be fully navigable via screen reader. This means: proper ARIA labels on all interactive elements (including the numeric keypad), logical tab order through the four send stages, announcement of status changes (transaction sent, delivery confirmed), and accessible error messages that describe both the error and the correction action. The numeric keypad, in particular, requires careful ARIA implementation: each digit button must be labeled with its value, the backspace button must be labeled as "delete" or "backspace," and the decimal point must be clearly identified.
Motor accessibility: Members with limited fine motor control may find small touch targets frustrating. All interactive elements in the P2P interface should meet the WCAG 2.2 minimum target size of 24 by 24 CSS pixels, and the recommended size for frequently used controls (the send button, digit keys) is 44 by 44 pixels or larger. Gesture-based interactions (swipe, long-press) should always have keyboard-accessible alternatives.
Cognitive accessibility: P2P transactions involve money — a domain that can be anxiety-inducing for members with cognitive disabilities, numeracy challenges, or financial literacy gaps. The interface should use plain language (not "initiate a P2P transfer" but "send money"), provide visual confirmation of dollar amounts (not just numeric but also written: "$50.00 — fifty dollars"), and avoid making assumptions about the member's financial literacy. Error messages should be supportive rather than blaming: "The amount you entered is more than your available balance. Would you like to enter a different amount?"
Color and contrast: All status indicators (success, pending, failed) must be communicated through both color and text or iconography. A green checkmark with "Sent" text is accessible; a green screen with no textual confirmation is not. The send button must meet a 4.5:1 contrast ratio for normal text and 3:1 for large text, and the interface must respect the device's dark mode and high-contrast settings.
Language access: Credit unions with significant non-English-speaking member populations should offer the P2P interface in the member's preferred language. This goes beyond translation to include culturally appropriate examples, local customs for money communication, and consideration of how money requests are framed in different cultural contexts. The Zelle enrollment and transaction flows should inherit the member's language preference from the digital banking platform's locale settings.
Regulatory Compliance for P2P Payments
P2P payment regulation is a complex and evolving landscape. Credit unions must navigate multiple federal and state regulatory frameworks while designing the member experience, and regulatory requirements should be treated as UX constraints that shape — but need not degrade — the member experience.
Regulation E (Electronic Fund Transfer Act): Reg E is the primary federal regulation governing P2P payments. It establishes error resolution procedures, disclosure requirements, and consumer liability limits for unauthorized electronic fund transfers. Key UX implications include: clear upfront disclosure of any fees associated with P2P transactions, a well-defined error resolution process accessible from the transaction detail view, timely provisional credit for reported unauthorized transactions (within 10 business days), and clear member-facing documentation of error resolution rights. The P2P error reporting flow — which must be accessible from the mobile app — should guide the member through the Reg E dispute process with clear language about timelines, documentation requirements, and expected resolution.
BSA/AML and OFAC compliance: P2P transactions are subject to Bank Secrecy Act, anti-money laundering, and Office of Foreign Assets Control screening requirements. Credit unions must implement transaction monitoring that flags suspicious activity without creating false positive friction for legitimate members. The UX challenge is managing the rare but inevitable scenario where a legitimate transaction is flagged: the member should receive a clear, timely notification that their transaction is under review, an estimated review timeline, and a pathway to provide additional information to expedite resolution. A complete black-box experience — where the transaction simply fails with no explanation — erodes trust and drives members to alternative P2P providers.
UDAAP (Unfair, Deceptive, or Abusive Acts or Practices): The CFPB's UDAAP authority applies to P2P payment marketing and disclosure practices. Credit unions must avoid misleading members about transaction speed (Zelle payments to enrolled recipients typically arrive in minutes, but the credit union should not guarantee instant delivery), reversibility (as noted, Zelle payments are generally not reversible), and fee structures. The confirmation screen language should be precise: "Typically arrives within minutes" rather than "Instant delivery."
State money transmission laws: States have varying requirements for money transmission, disclosure, and consumer protection. Credit unions operating in multiple states should ensure their P2P interface respects state-specific disclosure requirements and that the member's experience is consistent across state lines while meeting local regulatory requirements.
Section 1033 (Open Banking): The CFPB's Section 1033 rule on open banking — which requires financial institutions to make consumer financial data available to authorized third parties — has implications for P2P payment data. Members who authorize a third-party P2P service (such as Venmo or a budgeting app) to access their transaction history must have their P2P transaction data included in that access. Credit unions should ensure their P2P data architecture supports the standardized data access required by Section 1033, with appropriate authentication and consent mechanisms.
Small Credit Union Strategies for P2P Success
Small and mid-size credit unions often face the greatest pressure to deliver competitive P2P experiences while operating with limited technology budgets, smaller development teams, and fewer integration resources. However, several strategic approaches can help smaller credit unions deliver P2P experiences that rival those of much larger institutions.
Platform-leveraged P2P: Many core processing platforms (Symitar, Episys, DNA, Portico) offer P2P functionality as a platform module. Credit unions should start by maximizing the P2P capabilities already included in their core platform before building custom experiences. Platform modules have the advantage of pre-built core integration, compliance validation, and ongoing regulatory updates — at the cost of UX flexibility. For many small credit unions, a well-configured platform P2P module with thoughtful member-facing content and onboarding guidance will significantly outperform a poorly executed custom integration.
Digital banking platform enhancements: If the core platform's P2P experience is suboptimal but the digital banking platform (Digital Insight, NCR, Jack Henry Banno, Alkami) offers customization options, focus investment on the presentation layer. Customizing the P2P send flow UI within the digital banking platform — even when the backend processing runs through the core platform module — can dramatically improve the member experience without requiring deep core integration work.
CUSO and shared services: P2P technology investment is a natural domain for credit union service organization (CUSO) collaboration. Multiple small credit unions can pool resources to develop or procure a shared P2P UX layer that each credit union can brand as its own. This cooperative approach — consistent with the credit union philosophy of collaboration — enables smaller institutions to deliver P2P experiences comparable to those of billion-dollar credit unions and regional banks.
Progressive P2P enhancement: Small credit unions should plan for progressive P2P enhancement over time rather than attempting to build a complete experience all at once. Phase 1: Core Zelle send and receive with basic enrollment. Phase 2: Request flow and split payments. Phase 3: Enhanced notification architecture and fraud prevention. Phase 4: Business P2P and advanced features. A phased approach controls development cost, allows the credit union to learn from member behavior before investing in Phase 3 and 4 features, and ensures that foundational functionality is solid before adding complexity.
Staff as P2P advocates: For small credit unions, frontline staff are the most powerful P2P adoption driver. Training tellers, member service representatives, and digital banking support staff to demonstrate Zelle enrollment during account opening calls, member service interactions, and lobby conversations can drive adoption rates that rival or exceed those of large credit unions with expensive digital marketing campaigns. A member who enrolls in Zelle during a 90-second conversation with a trusted staff member is significantly more likely to use the feature repeatedly.
KPI Framework for P2P Payment Success
Measuring P2P payment success requires a balanced framework that captures adoption, engagement, member satisfaction, operational efficiency, and financial impact. The following KPIs provide a comprehensive view of P2P performance.
Adoption KPIs: Percentage of digital banking active users enrolled in Zelle (target: 40%+ within 6 months of launch); monthly P2P enrollment conversion rate (target: 20%+ of non-enrolled digital banking users who initiate P2P for the first time); first-use completion rate (percentage of members who start the enrollment flow and complete a first transaction — target: 70%+).
Engagement KPIs: Average P2P transactions per enrolled user per month (target: 3+); average P2P transaction value (baseline: $50-$100, varies by member segment); P2P transaction growth rate (target: 20%+ quarter-over-quarter); percentage of P2P transactions by type (send vs. request vs. split — request and split indicate deeper engagement).
Member satisfaction KPIs: P2P feature satisfaction score (from in-app or post-transaction survey — target: 8+/10); P2P Net Promoter Score (measured separately from overall digital banking NPS — target: 60+); percentage of transactions completed without errors or disputes (target: 99.5%+); average time to complete a P2P send (from tapping "Send Money" to confirmation — target: under 30 seconds for experienced users).
Operational KPIs: P2P-related member service contacts per 1,000 transactions (target: fewer than 5 per 1,000); average resolution time for P2P disputes (target: under 48 hours for simple disputes, under 10 business days for Reg E disputes); percentage of expired/reversed payments due to unenrolled recipients (target: under 5% — higher rates indicate enrollment friction).
Business impact KPIs: Correlation between P2P enrollment and digital banking login frequency (P2P-enrolled members should log in 30%+ more frequently), correlation between P2P usage and primary financial institution status (P2P-active members should be significantly more likely to designate the credit union as their primary FI), direct deposit capture from P2P onboarding (members who enroll during account opening should complete direct deposit setup at higher rates).
90-Day P2P Implementation Roadmap
Transforming your credit union's P2P payment experience from functional to exceptional requires a structured, phased approach. The following 90-day implementation roadmap provides a realistic timeline for a credit union with dedicated digital product and development resources.
Phase 1: Foundation (Days 1-30)
- Week 1: Audit current Zelle integration — identify enrollment friction points, broken flows, known member complaints, and regulatory compliance gaps. Document the current-state member journey with screenshots and process maps.
- Week 2: Define the target-state member journey map for P2P send, request, split, and enrollment flows. Prioritize flows based on member impact and development effort.
- Week 3: Design high-fidelity mockups for the send flow (the highest-impact flow). Test with 5-8 members using clickable prototypes. Revise based on feedback.
- Week 4: Begin development of the redesigned send flow. Prepare supporting content (help articles, FAQs, notification copy).
Phase 2: Core Delivery (Days 31-60)
- Weeks 5-6: Complete development and internal QA of the redesigned send flow, confirmation screen, and result screen. Conduct regression testing on enrollment, limits, and compliance requirements.
- Week 7: Deploy the redesigned send flow to a 10% member cohort (or beta testers). Monitor transaction completion rates, error rates, and member feedback. Iterate on high-priority issues.
- Week 8: Full rollout of the redesigned send flow. Activate the data dashboard for monitoring adoption and engagement KPIs. Begin design work on request and split payment flows.
Phase 3: Expansion (Days 61-90)
- Weeks 9-10: Design, develop, and test the request payment flow and group split functionality using the same four-stage architecture validated in Phase 2.
- Week 11: Deploy request and split flows. Launch the P2P onboarding campaign — in-app enrollment prompts, staff training, targeted email and SMS communication to high-potential member segments.
- Week 12: Launch the enhanced notification architecture (delivery confirmations, request reminders, fraud alerts). Publish KPI dashboard for ongoing P2P performance monitoring. Plan Phase 4 features: business P2P, advanced fraud prevention, and deeper integration with digital banking personalization.
Future Trends in P2P and Embedded Payments
The P2P payment landscape continues to evolve rapidly, and credit unions that design their P2P experience with future trends in mind will maintain competitive advantage as the market shifts.
Embedded P2P in conversational banking: The next frontier for P2P is embedding payment initiation within conversational banking interactions — AI-powered chatbots, SMS banking, and voice assistants. A member should be able to say, "Send Sarah $50 for dinner" in a chat interface and have the P2P transaction initiated without ever opening the dedicated P2P flow. This requires robust natural language processing, recipient disambiguation, and secure voice/text authentication — but represents the most frictionless possible P2P experience.
Request-to-pay and proactive P2P: Rather than requiring the member to initiate a send or request, proactive P2P flows use contextual intelligence to anticipate payment needs. If the system detects from calendar integration that the member had lunch at a restaurant they frequently split with Sarah, it might proactively offer: "Ready to split yesterday's lunch with Sarah? $38 each?" These proactive suggestions — powered by transaction history, calendar data, and location context — transform P2P from a reactive utility into a proactive assistant.
Instant payment networks and P2P convergence: The Federal Reserve's FedNow real-time payment network and The Clearing House's RTP network are converging with P2P payment infrastructure, enabling instant settlement for transactions that previously took 1-3 business days (ACH) or required a specific P2P network. Credit unions should ensure their P2P architecture can integrate with multiple instant payment rails, routing each transaction to the optimal network based on speed, cost, and recipient preferences.
Digital identity and P2P: The evolution of digital identity — including mobile driver's licenses, verified business identities, and self-sovereign identity — will simplify P2P recipient verification and reduce fraud. A member should be able to send money to anyone with a verified digital identity, not just to people in the Zelle network or with a specific app. Credit unions that invest in digital identity infrastructure today will be positioned to reduce P2P fraud while simultaneously simplifying the send flow.
Cross-border P2P: The line between domestic and cross-border payments is blurring, and credit union members increasingly need to send money to family members, contractors, and service providers outside the United States. Future P2P experiences will need to handle multi-currency transactions, know-your-customer requirements for international recipients, and real-time exchange rate transparency — all within the same intuitive send flow that members use for domestic P2P.
Open banking P2P aggregation: As open banking (Section 1033) enables members to view all their financial accounts in one place, P2P transaction history from other financial institutions — Venmo, Cash App, neobanks — will be available within the credit union's digital banking platform. This creates an opportunity: the credit union can become the unified P2P activity hub even for transactions that occur outside its ecosystem, reinforcing its role as the member's primary financial relationship.
Conclusion
The P2P payment experience is not a peripheral feature of digital banking — it is a strategic relationship anchor that determines whether the credit union remains central to its members' daily financial lives or cedes that ground to Venmo, Cash App, and neobank competitors. Credit unions that invest in a thoughtfully designed, mobile-first, trust-centered P2P experience — anchored by seamless Zelle integration — can recapture daily money movement interactions, deepen member engagement, and position themselves as the primary financial institution for a generation that expects instant, intuitive, and secure digital payments.
The playbook outlined above provides a comprehensive framework: from foundational Zelle integration architecture and the four-stage send flow design, through request and split payment UX, mobile-first patterns, security design, accessibility compliance, regulatory navigation, and a concrete 90-day implementation roadmap. The path from a functional P2P feature to a strategically differentiating P2P experience requires deliberate investment in UX design, member research, and continuous optimization — but the return on that investment, measured in member engagement, retention, and acquisition, makes it one of the highest-leverage investments a credit union can make in its digital future.
Credit unions that act decisively to transform their P2P payment experience will not only retain members who might otherwise drift toward fintech alternatives — they will attract new members who are actively seeking a financial partner that combines the convenience they expect from digital payments with the trust, relationship focus, and community commitment that only a credit union can provide.
This article was brought to you by GrafWeb CUSO – Building the future of digital credit unions.
References
- Cornerstone Advisors. "What's Going On in Banking 2025." Cornerstone Advisors, 2025.
- Federal Reserve System. "Federal Reserve Payments Study." Board of Governors of the Federal Reserve System, 2025.
- Pew Research Center. "Mobile Technology and Financial Services." Pew Research Center, 2025.
- Federal Trade Commission. "Consumer Sentinel Network 2025 Data Book." FTC, 2025.
- Early Warning Services. "Zelle Network: Financial Institution Integration Guide." Zelle, 2026.
- J.D. Power. "2025 U.S. Banking Satisfaction Study." J.D. Power, 2025.
- NACHA. "2025 ACH Payments Study." NACHA, 2025.
- Filene Research Institute. "Digital Trust and Member Engagement." Filene Research Institute, 2025.
- CUNA. "Credit Union Digital Banking Technology Survey." Credit Union National Association, 2025.
- Bain & Company. "The Future of Banking: Digital Payments and Member Loyalty." Bain & Company, 2025.
- McKinsey & Company. "Global Payments Report 2025." McKinsey & Company, 2025.
- Forrester Research. "The State of Digital Banking UX, 2025." Forrester Research, 2025.
- Nielsen Norman Group. "P2P Payment UX: Best Practices for Mobile Money Movement." NNGroup, 2025.
- Federal Trade Commission. "Regulation E: Electronic Fund Transfer Act Compliance Guide." FTC, 2025.
- Consumer Financial Protection Bureau. "Section 1033: Consumer Financial Data Rights." CFPB, 2025.
- W3C. "Web Content Accessibility Guidelines (WCAG) 2.2." World Wide Web Consortium, 2025.
- Early Warning Services. "Zelle for Business: Implementation Guide." Early Warning Services, 2026.
- Federal Reserve System. "FedNow Service: Instant Payment Infrastructure." Federal Reserve, 2025.
- The Clearing House. "RTP Network: Real-Time Payments for Financial Institutions." TCH, 2025.
- American Bankers Association. "P2P Payment Fraud Prevention Best Practices." ABA, 2025.
- NerdWallet. "Best P2P Payment Apps in 2026: Venmo vs. Cash App vs. Zelle." NerdWallet, 2026.
- Bankrate. "P2P Payment App Statistics and Usage Trends 2025-2026." Bankrate, 2026.
- PYMNTS. "The P2P Payment Ecosystem: How Financial Institutions Can Compete." PYMNTS, 2025.
- Mercator Advisory Group. "P2P Payments Market Outlook 2025-2027." Mercator Advisory Group, 2025.
- Celent. "Digital Banking UX Benchmark: Mobile Payments Edition." Celent, 2025.
- FICO. "Fraud in P2P Payments: Trends and Mitigation Strategies." FICO, 2025.
- LexisNexis Risk Solutions. "2025 Digital Banking Fraud Report." LexisNexis, 2025.
- Accenture. "The Digital Payments Experience: Banking Redefined." Accenture, 2026.
- Deloitte. "Embedded Finance and the Future of P2P Payments." Deloitte Digital, 2025.
- SIFMA. "Digital Identity and the Future of Financial Services." SIFMA, 2025.
- TransUnion. "2025 Digital Banking Consumer Pulse Report." TransUnion, 2025.
Request a proposal from GrafWebCUSO · (201) 632-1771 · [email protected]