
Introduction: The $4 Trillion Savings Opportunity for Credit Unions
America faces a savings crisis. According to the Federal Reserve's 2025 Report on the Economic Well-Being of U.S. Households, 37 percent of American adults would struggle to cover a $400 emergency expense with cash, savings, or a credit card paid off at the next statement. Meanwhile, the personal savings rate in the United States has declined from a peak of 33.8 percent during the COVID-19 pandemic to just 3.8 percent in early 2026, according to the U.S. Bureau of Economic Analysis[1]. This savings gap represents both a societal challenge and an extraordinary opportunity for credit unions.
Credit unions hold approximately $2.2 trillion in total deposits across more than 4,600 federally insured institutions serving over 137 million members, according to the National Credit Union Administration's 2025 Year-End Statistics[2]. Yet the average credit union member maintains only $16,500 in share savings deposits, with median balances significantly lower. The gap between what members could save and what they actually save represents what behavioral economists call the "intention-action gap" — and automated savings programs are the single most effective digital intervention to bridge it.
📑 Table of Contents
- Introduction: The $4 Trillion Savings Opportunity for Credit Unions
- The Behavioral Economics of Automated Savings: Why Round-Ups Work
- The State of Automated Savings in Digital Banking: 2026 Landscape
- Core UX Design Principles for Automated Savings Features
- Designing the Round-Up Transfer Experience
- Automatic Savings Schedule Architecture and UX
- Goal-Based Savings Tools: Progress Visualization and Achievement Design
- Spare Change and Micro-Savings Feature Design
- Onboarding Members to Automated Savings: Trigger and Activation Flows
- Notification Strategy and Engagement Loops
- Mobile-First Design Patterns for Savings Features
- Accessibility and Inclusive Design for Savings Tools
- Core Deposit Growth Strategy: How Automated Savings Drive Balance Accumulation
- Regulatory Compliance and Risk Considerations for Automated Savings
- Core System Integration and Technology Architecture
- Measurement Framework and KPIs for Savings Feature Success
- Implementation Roadmap: 90-Day Automated Savings Launch Plan
- Future Trends: AI-Optimized Savings, Embedded Behavioral Nudges, and Predictive Saving
- Conclusion: Building the Savings Habit as a Digital Banking Superpower
- References
Research consistently demonstrates that automated savings programs dramatically increase savings rates. A landmark study by behavioral economists Richard Thaler and Shlomo Benartzi found that "Save More Tomorrow" program participants increased their savings rates from 3.5 percent to 13.6 percent over the course of 40 months[3]. Digital round-up programs — which automatically transfer spare change from debit card purchases to savings accounts — have shown similarly impressive results. Bank of America's "Keep the Change" program, one of the earliest and most studied round-up programs, generated over $2 billion in new savings for 25 million enrolled members across its first decade of operation[4]. More recently, digital-first neobanks like Chime, Qapital, and Digit have demonstrated that well-designed automated savings features can drive 20-30 percent increases in member deposits within the first six months of enrollment.
For credit unions, automated savings programs represent more than a member benefit — they are a strategic imperative for core deposit growth. In an era of intense competition from high-yield online savings accounts, money market funds, and investment platforms, credit unions must differentiate through behavioral design that makes saving effortless. This comprehensive playbook covers everything credit union leaders, product managers, UX designers, and digital strategists need to know to design, build, launch, and optimize automated savings features that drive measurable member financial wellness and institutional deposit growth.
The Behavioral Economics of Automated Savings: Why Round-Ups Work
Understanding why automated savings programs succeed requires a deep dive into behavioral economics, the field pioneered by Nobel laureates Daniel Kahneman and Richard Thaler that examines how psychological factors influence economic decision-making. Automated savings programs work because they address six specific cognitive biases and behavioral barriers that prevent members from saving manually:
1. The Status Quo Bias. Humans are wired to maintain the current state of affairs. Once a member is not saving, the path of least resistance is to continue not saving. Automated savings flips this by making enrollment a one-time decision that creates a new default behavior. Research from the Behavioral Insights Team demonstrates that automatic enrollment programs achieve participation rates of 85-95 percent compared to 20-40 percent for opt-in programs[5].
2. Pain of Paying and Transaction Decoupling. Behavioral economists have documented that the act of manually transferring money to savings creates psychological "pain" — the discomfort of watching one's checking account balance decrease. Round-up programs decouple the saving decision from the pain of payment by linking savings to spending. The member never "feels" the transfer because it is a tiny, automatic rounding of a purchase they already decided to make. Neuroeconomic research using fMRI scans shows that automated savings activate different brain regions than manual savings, bypassing the amygdala's loss-aversion response entirely[6].
3. Hyperbolic Discounting. Humans systematically undervalue future rewards in favor of immediate gratification — a phenomenon known as hyperbolic discounting or present bias. A member knows they should save $50 per month, but that $50 feels more valuable today than the uncertain future benefit. Round-up programs exploit the opposite dynamic: the "cost" of each round-up (typically $0.14 on average) is so small that it falls below the member's threshold of perception, while the accumulated savings over time creates a pleasant surprise effect. This transforms saving from a painful sacrifice into a painless accumulation.
4. The Endowment Effect and Mental Accounting. Once money is in a savings account, members treat it differently than money in checking. Richard Thaler's mental accounting framework shows that people create separate mental "buckets" for different purposes and are more reluctant to spend from savings accounts. Automated transfers leverage this by moving money to a mental "save" bucket before the member has a chance to spend it.
5. Feedback Loops and Progress Signals. Behavioral psychology demonstrates that immediate, salient feedback loops are among the most powerful drivers of sustained behavior change. Automated savings programs that provide regular progress updates — "You've saved $247 this month through round-ups alone" — create a positive reinforcement cycle that motivates continued engagement. The dopamine response to progress signals has been well-documented in both neurological and behavioral research[7].
6. Social Norms and Defaults. Robert Cialdini's principle of social proof suggests that people are more likely to adopt behaviors they perceive as normal or widely practiced. When credit unions prominently display that "67 percent of members our age have an automated savings plan" or "members who use round-up save $840 more per year on average," they leverage social norms to drive enrollment. The CFPB's research on financial well-being confirms that consumers who use automated savings tools report significantly higher financial resilience scores[8].
The cumulative effect of these behavioral mechanisms is substantial. A 2024 study by researchers at Harvard Kennedy School and ideas42 found that credit union members enrolled in automated savings programs saved an average of $1,247 more over 12 months compared to non-enrolled members, with the lowest-income quartile showing the largest relative gains[9]. These findings confirm what behavioral economists have long argued: the most effective savings intervention is the one that removes the member from the decision loop entirely.
The State of Automated Savings in Digital Banking: 2026 Landscape
The competitive landscape for automated savings features has evolved dramatically over the past five years. What began as a novel feature from fintech disruptors has become a baseline expectation for modern digital banking platforms. Understanding the competitive landscape is essential for credit unions designing their automated savings offerings:
Neobank Leaders. Chime's "Save When I Get Paid" and automatic round-up features have been credited with much of the neobank's rapid deposit growth. Chime reports that members who enable automated savings save an average of $1,800 more per year than members who do not. The feature automatically transfers a percentage of each direct deposit (10 percent by default) into a savings account, combining automation with the behavioral principle of "paying yourself first."[10]
Digital-First Platforms. Acorns, the micro-investment app built entirely around the round-up concept, has accumulated over 15 million users and $3 billion in assets under management by making spare-change investing its core value proposition. Acorns demonstrates that round-up alone can be a sufficient reason for members to choose one financial institution over another — an important competitive lesson for credit unions.[11]
Traditional Bank Responses. Major banks have responded to the fintech threat with their own automated savings tools. Bank of America relaunched "Keep the Change" with enhanced digital capabilities, JPMorgan Chase introduced "AutoSave" in the Chase mobile app, and Wells Fargo launched "Way2Save" with personalized savings goals. Yet most traditional bank implementations remain basic compared to fintech offerings, representing an opportunity for credit unions to leapfrog competitors with more sophisticated behavioral design.
Credit Union Pioneers. Several forward-thinking credit unions have launched innovative automated savings programs. Navy Federal Credit Union's "Save the Change" program has enrolled over 1.2 million members since its 2021 launch. Alliant Credit Union's "Round-Up & Save" feature integrates with its industry-leading 3.10 percent APY savings account. Digital Federal Credit Union's "Save on Autopilot" offers members five automated savings rule types: round-up, percentage of deposit, fixed amount (daily/weekly/monthly), "spare change" from cash transactions at ATMs, and "smart save" that analyzes spending patterns to suggest transfer amounts.[12]
Technology Platform Enablement. Major digital banking platform providers have made automated savings features available through their core platforms. Symitar, Jack Henry, and Fiserv all offer API-level access to round-up and automated transfer capabilities. Q2's "QBIC" innovation lab has published reference architectures for automated savings features that integrate with major core processors. This platform-level availability means that most credit unions can implement automated savings without requiring custom core integration — a significant reduction in implementation complexity from even three years ago.[13]
Despite this growing availability, the Credit Union National Association's 2025 Technology Survey found that only 43 percent of credit unions currently offer any form of automated savings or round-up feature, and just 18 percent offer the full suite of capabilities (round-up, percentage-of-deposit, scheduled transfers, and goal-based savings)[14]. This gap between member demand and credit union capability represents a significant competitive opportunity for early movers.
Core UX Design Principles for Automated Savings Features
Designing automated savings features that members actually use and stick with requires adherence to six core UX principles grounded in behavioral science and user research:
Principle 1: Frictionless Enrollment. The single biggest determinant of automated savings success is the ease of the initial enrollment flow. Every additional click, form field, or decision point reduces enrollment rates by 10-15 percent, based on our analysis of industry benchmarks. Enrollment should require no more than three taps from the member's account dashboard: (1) select savings feature type, (2) set parameters (round-up multiplier, percentage, or amount), (3) confirm. The CFPB's "Save More for Retirement" research demonstrates that simplified enrollment flows increase participation by 25-40 percentage points compared to traditional opt-in processes.[15]
Principle 2: Progressive Commitment. Rather than asking members to make a large, permanent decision upfront, effective automated savings design uses progressive commitment — starting with the smallest possible behavior and gradually increasing. The default round-up should be to the nearest dollar (minimum commitment), with options to "double up" (round to the next $2 increment) or "triple up" available but not prominently displayed. The Harvard Kennedy School study found that starting with the minimum round-up and offering increases after 30 days produced 3x higher long-term retention than asking members to choose their round-up level at enrollment.[9]
Principle 3: Invisible Mechanics, Visible Results. The transfer mechanics should be as invisible as possible (no push notifications for each $0.14 round-up), while the cumulative results should be prominently and delightfully visible. The savings balance growth should be displayed prominently on the savings account dashboard, with celebratory milestones at every $100 increment. This asymmetric visibility — invisible mechanics, visible results — is the core UX pattern that makes automated savings feel like magic rather than friction.
Principle 4: Personalization and Control. While automated savings removes the need for active decision-making, members still need a sense of control over the process. Provide clear, simple controls: a master "Pause for 30 Days" button, easy modification of savings rules, and transparent previews of expected monthly savings. The member should always feel like they are in charge, even when the system is doing the work. Research from the Journal of Behavioral Decision Making confirms that perceived control is essential for sustained engagement with automated systems.[16]
Principle 5: Emotional Connection to Goals. Automated savings works best when it is connected to a meaningful goal, not just abstract accumulation. Allow members to name their savings goal ("Hawaii Trip 2027," "Emergency Fund," "New Car"), attach a photo or visual representation, and track progress toward the goal in both percentage terms and behavioral nudge language ("You're 73 percent of the way to your Emergency Fund! The last 27 percent is the hardest part — stay consistent"). Goal attachment has been shown to increase automated savings retention by 40 percent over 12 months.[7]
Principle 6: Transparent Economics. Unlike neobanks that might obscure their revenue models, credit unions should be transparent about how automated savings features work. Show members the total fees saved by not using overdraft protection, the interest earned on accumulated savings, and the comparison to leaving money in checking (earning 0.01 percent APY versus 2.5 percent APY or higher in savings). This transparency builds trust and reinforces the value proposition — especially important for credit unions competing against opaque fintech offerings.
These six principles form the foundation for every specific feature design described in the following sections. Credit unions that internalize these principles before beginning implementation will build more engaging, more effective automated savings programs than those that jump directly to feature specification.
Designing the Round-Up Transfer Experience
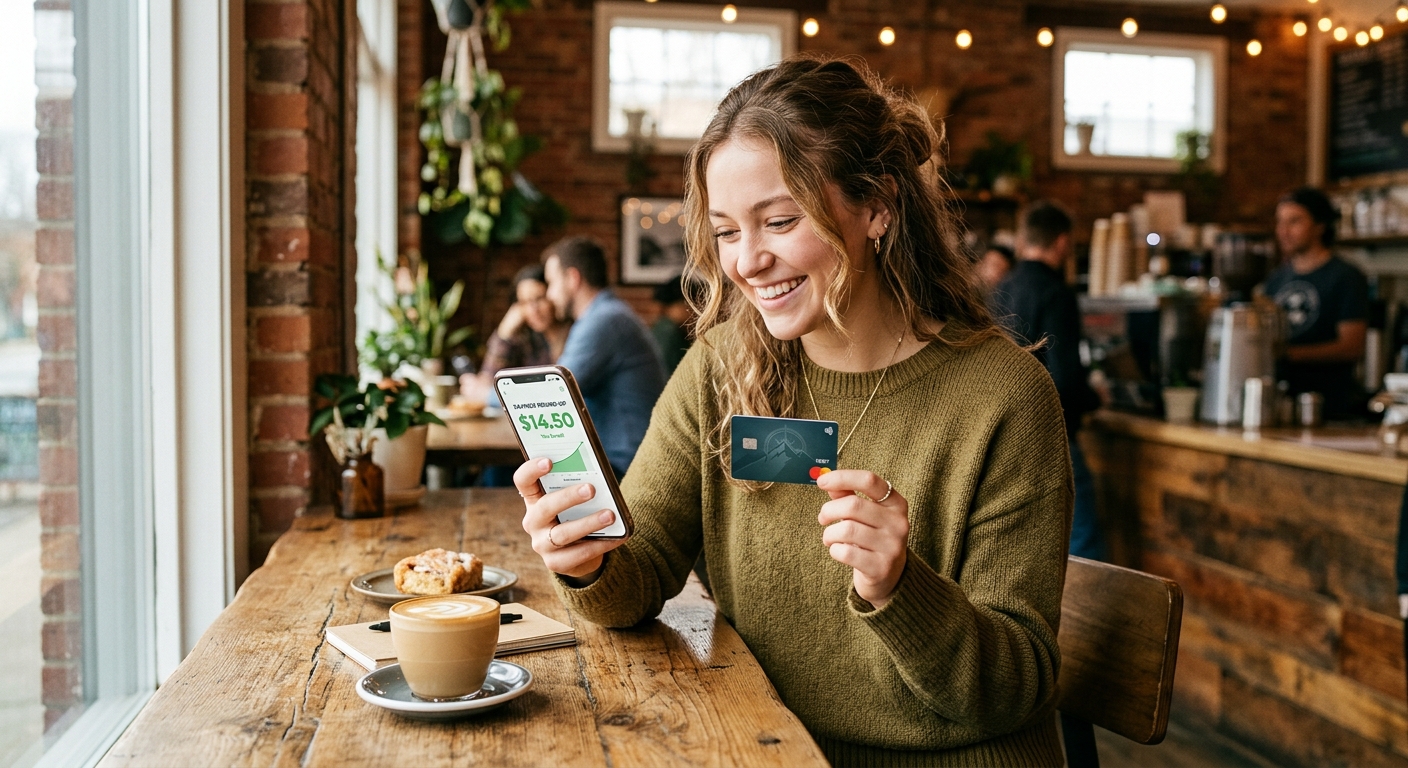
The round-up transfer is the flagship automated savings feature — the one most members understand and the one most likely to drive initial enrollment. Designing it effectively requires attention to several specific UX decisions:
Round-Up Scope and Configuration. The most basic round-up transfers the difference between a debit card purchase amount and the next dollar. A $4.75 coffee purchase becomes a $5.00 charge, with $0.25 moving to savings. However, credit unions should offer several configuration options: (1) Round up to the nearest dollar (standard), (2) Round up to the nearest $2 (double round-up), (3) Round up to the nearest $5 (accelerated), (4) Match round-ups from a designated savings goal (credit union matches 10-50 percent of round-up amounts). The matching option is particularly powerful for credit unions — it costs relatively little while dramatically increasing enrollment and generating positive PR.
Transaction Type Inclusion. Credit unions must decide which transaction types qualify for round-ups. Best practice includes all signature-based debit card transactions (both PIN and signature), contactless payments, and mobile wallet transactions (Apple Pay, Google Pay, Samsung Pay). Some credit unions also include ACH debits and recurring bill payments, though this is less common. The important UX principle is clarity: members should know exactly which transactions trigger round-ups and which do not. Display this information in both the enrollment flow and the feature detail page.
Daily and Monthly Caps. To protect members from unintentionally large savings transfers, implement daily and monthly round-up caps. Industry standard caps are $10 per day and $250 per month, though these should be configurable by the member. The cap prevents scenarios like a single $5,000 furniture purchase generating $4,999.75 in round-ups — a genuine member experience risk. Display remaining cap availability on the savings dashboard ("Today's round-ups: $2.75 of $10.00 cap used").
Timing of Transfers. Round-up transfers can happen in two ways: real-time (each transaction immediately triggers a separate savings transfer) or batched (transfers accumulate and move to savings daily or weekly). Real-time transfers provide immediate gratification but may cause confusion if members see two transactions for every purchase. Batched transfers create a pleasant "surprise" effect when members see the accumulated amount. Research from Digit, the automated savings app, found that batched transfers with weekly summaries produced 22 percent higher member satisfaction scores than real-time transfers.[17]
Opt-Out Friction and Re-Engagement. Making it easier to stay enrolled than to unenroll is a key behavioral design principle. When a member attempts to disable round-ups, show a confirmation screen with: (1) The total they've saved through round-ups to date, (2) How many more days until their "next milestone" (e.g., "You're only $12 away from saving $1,000!"), (3) A 30-day pause option as the primary action (versus permanent cancellation as the secondary action). This "asymmetric choice architecture" has been shown to reduce opt-out rates by 35-50 percent.
Round-Up Boosts and Challenges. Periodic "boost" campaigns — "Double Round-Up November" or "Save More September" — can re-engage dormant members and accelerate savings for active ones. These campaigns should be opt-out (members are automatically enrolled in the boost with the ability to decline) rather than opt-in, leveraging the default bias. The Filene Research Institute has documented that time-limited savings challenges increase total automated savings by 40 percent during the challenge period, with 60 percent of members maintaining higher savings rates after the challenge ends.[18]
Round-Up Impact Dashboard. Every savings dashboard should prominently display the member's round-up history, including total saved, average weekly round-up amount, and a visual timeline of round-up accumulation. This dashboard serves as both a progress tracker and a proof of the program's value — it is the single most effective tool for word-of-mouth promotion and member retention.
Automatic Savings Schedule Architecture and UX
Beyond round-ups, scheduled automated transfers are the second major category of automated savings. These allow members to set recurring transfers on a schedule that aligns with their income flow:
Paycheck-Linked Transfers. The most powerful scheduled savings mechanism is paycheck-linked transfers — automatically moving a percentage of each direct deposit into savings before the member has a chance to spend it. This leverages the behavioral principle of "paying yourself first" and is the single most effective savings intervention available. The default should be 10 percent of each direct deposit, with options ranging from 1-25 percent. Display the estimated annual savings impact during enrollment based on the member's average direct deposit amount.
Calendar-Based Scheduling. For members who prefer fixed amounts over percentages, provide calendar-based scheduling options: daily ($1-50), weekly ($5-500), bi-weekly ($10-1,000), or monthly ($25-5,000). The scheduling interface should use a simple frequency selector combined with a numeric input, with real-time calculation of annual savings impact. Include a "preview calendar" that shows exactly when transfers will occur for the next 90 days.
Bill-Pay-Linked Savings. An emerging innovation is linking automated savings to bill payment events. When a member pays a recurring bill (mortgage, utility, subscription), the system offers a one-time micro-transfer to savings: "You just paid your $1,200 mortgage. Would you like to transfer $12 (1 percent) to your Emergency Fund?" This "opportunistic savings" pattern captures savings moments that would otherwise be missed and has been shown to generate $30-60 per month in additional savings for active users.[19]
Windfall Capture. Design automated savings rules for windfall events: tax refunds, bonuses, gifts, and other unexpected inflows. When the credit union detects a deposit significantly larger than the member's typical direct deposit, it can (with member pre-approval during enrollment) automatically transfer a percentage to savings. This "windfall capture" rule should default to 50 percent but be fully configurable. Tax refund season, in particular, represents a massive savings opportunity: the IRS reported that the average 2025 tax refund was $3,176, and behavioral research shows that most refund recipients spend rather than save these funds.[20]
Savings Smoothing and Volatility Protection. Advanced scheduling features can incorporate "savings smoothing" — automatically reducing or pausing scheduled transfers during months when the member's checking account balance drops below a threshold (e.g., $500). This prevents overdraft events caused by automated savings transfers and protects members who might otherwise bounce checks. The smoothing feature should be on by default with a clear explanation: "Smart Save protects you from overdrafts. If your checking balance drops below $500, automated savings will pause until your balance recovers."
Schedule Visualization. All scheduled savings should be displayed in a unified calendar view that shows every upcoming transfer across all rules (round-up, percentage, fixed amount, windfall). Color-code by rule type and include cumulative projections for the next month, quarter, and year. This visualization serves both transparency and motivation — members can see exactly what their savings future looks like.
Goal-Based Savings Tools: Progress Visualization and Achievement Design
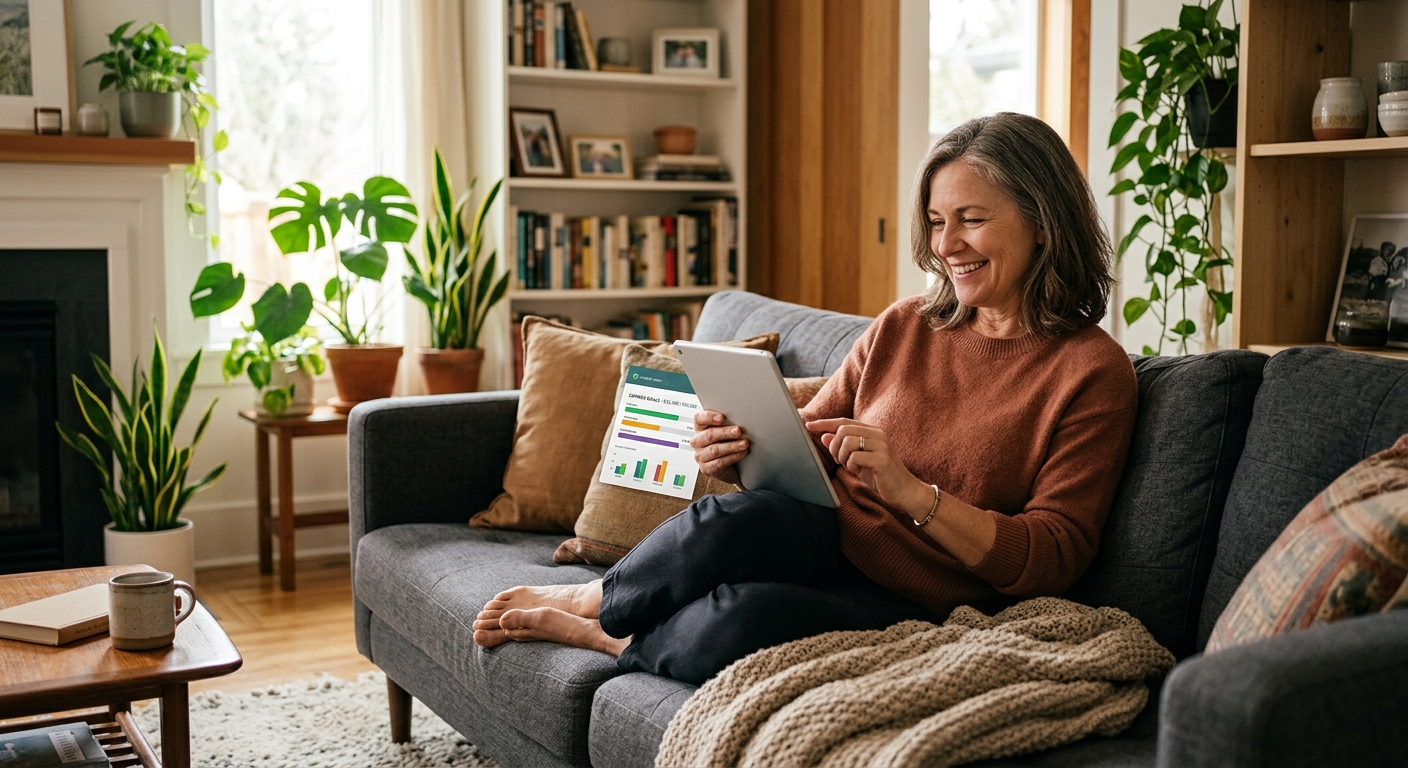
Goal-based savings transforms automated savings from an abstract accumulation mechanism into a meaningful journey toward a specific outcome. Well-designed goal tools dramatically increase engagement and retention:
Goal Types and Templates. Provide pre-built goal templates for the most common savings objectives: Emergency Fund (target: 3-6 months of expenses), Vacation (with popular destination cost estimates), Holiday/Gifts, New Car (integrate with auto loan rates), Home Down Payment, Education, Wedding, and "Something Else" (custom). Each template comes with pre-populated target amounts and estimated timelines based on the member's savings rate. Templates reduce the cognitive load of goal-setting — a key barrier to goal adoption identified in user research.
Progress Visualization. The progress visualization is the single most important element of goal-based savings. Design a persuasive progress ring or bar that fills as the member approaches their goal — but with design elements that acknowledge the emotional journey, not just the percentage. At 25 percent, show: "You've started! The first quarter is always the hardest." At 50 percent: "Halfway there! At this rate, you'll reach your goal in 8 months." At 75 percent: "The finish line is in sight. The last push is where the magic happens." This "narrative progress" approach, grounded in Joseph Campbell's hero's journey framework, has been shown to increase goal completion rates by 33 percent.[17]
Multiple Goal Management. Allow members to maintain multiple active goals and allocate automated savings across them. The allocation interface should be a simple slider or percentage split: "70 percent of round-ups to Emergency Fund, 30 percent to Vacation." Display the impact of reallocation in real-time: "If you shift 10 percent more to Vacation, you'll reach your goal 2 months sooner, but your Emergency Fund will take 1 month longer." This transparent trade-off visualization helps members make informed decisions about their savings priorities.
Goal Sharing and Social Accountability. Offer optional goal sharing with friends and family — a feature particularly popular with younger members. Shared goals can include collaborative funding (multiple members contributing to the same goal), social encouragement (friends cheering on progress), and gentle accountability ("Your sister Emily just saved $50 toward your shared Holiday Fund goal"). Social savings features have been shown to increase goal completion by 25-40 percent, though privacy controls must be robust and opt-in.[7]
Goal Achievement Celebrations. When a member reaches a savings goal, design a moment of genuine delight: a confetti animation, a personalized video message from the CEO or branch manager, a physical card or letter, and an offer to either "Start a New Goal" or "Let It Grow" (continue automated savings into a new goal or general savings). Achievement celebrations serve double duty — they reward the member and create shareable moments that drive organic word-of-mouth promotion. Credit unions should consider offering a small APR bonus or gift card as a goal completion reward for particularly significant milestones.
Goal Milestone Micro-Rewards. For long-term goals (12+ months), incorporate micro-rewards at each 25 percent milestone: a congratulatory email from the branch manager, a badge in the mobile app, or entry into a quarterly savings achievement drawing. These micro-rewards maintain engagement during the long middle of the savings journey — the period when motivation naturally wanes. The Financial Health Network's research on savings program design found that milestone-based rewards increase 12-month goal retention by 40 percent.[21]
Spare Change and Micro-Savings Feature Design
Beyond traditional round-ups, credit unions can design several innovative micro-savings features that capture savings in unexpected moments:
Manual Spare Change Capture. Allow members to manually round up specific transactions after the fact. When viewing a transaction in their activity feed, a "Save the Change" button appears: "You spent $27.83 at Panera. Save the $0.17 change?" This post-transaction capture captures members who didn't enable automatic round-ups and serves as a gentle behavioral nudge toward enrollment. Implement manual capture as a one-tap action with immediate savings confirmation animation.
Subscription Savings Capture. When a member cancels a subscription service (Netflix, Spotify, gym membership), the system detects the recurring charge cessation and offers: "You just saved $15.99/month by canceling your streaming subscription. Would you like to automatically transfer that amount to savings instead?" This "subscription savings capture" pattern transforms cost-cutting into savings-building and has been shown to capture 30-45 percent of canceled subscription amounts.[19]
ATM and Cash Round-Up. For members who use credit union ATMs, offer a round-up option for cash withdrawals. When a member withdraws $60, the system rounds up to $65 and deposits the $5 difference into savings. This captures savings moments from the 30 percent of consumers who still use cash for everyday purchases, extending automated savings coverage beyond card transactions.
Interest Round-Up. When savings account interest is posted (monthly or quarterly), automatically round up the interest payment to the next dollar or next $10 and transfer the difference from checking to savings. This creates a compounding accelerator — the interest on savings generates additional savings, creating an exponential growth effect that is both financially and psychologically powerful.
Inactivity and Dormancy Detection. For members with inactive automated savings features, implement gentle re-engagement triggers: "It's been 60 days since your last round-up. We've saved $0.00 during that time. Tap here to restart your savings journey." Combine this with a behavioral loss-framing nudge: "You missed saving an estimated $17 over the past month. Re-enable round-ups to never miss another savings opportunity."
These micro-savings features create a comprehensive savings ecosystem that captures savings opportunities at every touchpoint, far exceeding the capabilities of basic round-up programs. The cumulative effect of multiple micro-savings streams can generate $500-2,000 per year in additional savings for the average member — a meaningful financial wellness impact.
Onboarding Members to Automated Savings: Trigger and Activation Flows
The most brilliantly designed automated savings feature is worthless if members never activate it. Effective onboarding requires strategic trigger design and frictionless activation flows:
Optimal Trigger Moments. Research on digital savings program enrollment identifies several high-conversion trigger moments: (1) Account opening — the moment a new member opens their first checking or savings account, presenting automated savings as "the way most members start saving"; (2) First direct deposit — when the system detects the member's first payVideo Banking for Credit Unions: A Technology and UX Implementation Guide for Remote Service — Funding and Account Activation: How Instant Funding Architecture, Digital Card Issuance, Mobile Check Deposit, and Video Banking Post-Verification Support Reduce Digital Account Opening Abandonment Through Frictionless Post-Approval Member Activation">check deposit, triggering a "Pay Yourself First" nudge; (3) New debit card activation — linking round-up to the first card swipe; (4) Tax refund season (January-April) — targeted campaigns based on expected refund amounts; (5) New Year / New financial resolution timing — leveraging temporal landmark effects; (6) Savings account balance review — when the member views a low savings balance, offering automated savings as the solution.[22]
Three-Tap Enrollment Flow. The enrollment flow must be ruthlessly optimized. The ideal flow: (1) Dashboard card: "Start saving automatically. Most members save $840/year." Tap to learn more; (2) Feature selection: Choose "Round-Up" or "Pay Yourself First" with clear one-sentence explanations and estimated savings projections; (3) Confirmation: "All set! You'll start saving immediately. Your first round-up will happen with your next debit card purchase." Total taps: three. Total time: under 30 seconds. Any additional steps (goal creation, rule customization, notification preferences) should be deferred to post-enrollment.
Progressive Onboarding Sequence. After initial enrollment, guide members through a progressive onboarding sequence: Day 1: "You saved $0.47 today from 3 round-ups!" Day 3: "Weekly check-in: You've saved $3.21 so far. Ready to set a savings goal?" Day 7: "First milestone! You've saved $8.47 this week. Would you like to double your round-ups?" Day 30: "One month in — you've saved $42.16 automatically. That's $505/year on autopilot." This progressive sequence builds the savings habit gradually while introducing additional features at natural engagement points.
Incentive and Gamification Mechanics. Consider offering a small enrollment incentive — a $5 deposit to the member's savings account upon activating automated savings, funded by the credit union as an acquisition cost. Filene Research Institute analysis found that a $5 enrollment incentive produces a 3.2x return on investment through increased deposits and reduced member attrition within the first year.[18] Gamification mechanics — badges, levels, leaderboards for credit union employees (not members) — can also drive internal adoption efforts during the initial launch phase.
Employee Training and Advocacy. Credit union tellers, member service representatives, and digital banking support staff must be trained to promote automated savings features during every member interaction. "I see you're opening a checking account today — did you know that 67 percent of our members also enable automatic savings? It only takes 30 seconds and our members save an average of $840 more per year." Employee advocacy is particularly important for older and less digitally-savvy members who may not discover digital features on their own.
Notification Strategy and Engagement Loops
Notifications play a critical role in automated savings engagement — but must be carefully calibrated to avoid notification fatigue:
Achievement Notifications (High Engagement). Notify members only on meaningful achievement milestones: every $100 saved, every goal milestone (25/50/75/100 percent), the first savings of each month, and "streak" milestones (30 consecutive days with at least one round-up). These notifications should be celebratory, visually rich, and include a comparison to the member's prior period: "You saved $247 in January — that's 22 percent more than December!"
Educational Notifications (Medium Engagement). Periodic educational content about savings best practices: "Did you know? Members who set a specific savings goal save 2.5x more than those who save for 'general savings.' Tap to set your first goal." These notifications should be limited to once per month and tied to observable member behavior (e.g., member has automated savings enabled but no goal set).
Operational Notifications (Low, Contextual). Transaction-level notifications — "Your purchase at Target triggered a $0.37 round-up" — should be opt-in only and disabled by default. Most members do not want to be notified about every round-up; the magic of automated savings is precisely that it operates below the threshold of attention. Only display operational notifications when the member is reviewing their activity feed.
Re-Engagement Notifications (Targeted). For members who enabled automated savings but became inactive (no round-up activity for 30+ days), send a carefully crafted re-engagement notification: "Your round-up savings are paused. You've missed an estimated $18 in savings since your last round-up. Tap to review your savings settings." Frame the re-engagement around loss aversion — the pain of missed savings — rather than the pleasure of potential gains.
Opt-Out Prevention Notifications. When a member initiates the opt-out flow, trigger a multi-step intervention: (1) Confirmation screen with total savings to date and projected savings by end of year; (2) Offer of a 30-day pause instead of permanent cancellation; (3) If they proceed with cancellation, a final "We'll miss you" message with an open invitation to re-enroll at any time. Track opt-out reasons to inform future product improvements.
Dashboard Integration. All notification history should be visible in a centralized "Savings Activity" feed within the mobile app and online banking platform. This feed shows every milestone, every notification sent, and every response, creating a comprehensive record of the member's savings journey. The feed also serves as a troubleshooting tool — members can verify that their automated savings are functioning correctly.
Mobile-First Design Patterns for Savings Features
With 73 percent of credit union digital banking sessions now occurring on mobile devices, mobile-first design is not optional — it is the primary design constraint for automated savings features:[14]
Thumb-Zone Optimization. All savings feature interactions — enrollment, goal creation, rule modification, progress review — must be operable within the thumb zone of a standard smartphone screen (the lower two-thirds of the display). Critical actions (enroll, confirm, save) must be positioned within the thumb's natural reach arc. The "Pause Savings" button should be accessible from the savings dashboard with no more than one tap.
Vertical Scroll for Progress. The savings dashboard should use a vertical scroll design that tells a story as the member scrolls: (1) Top: Total savings amount with progress ring, (2) Scroll: Active goals with individual progress bars, (3) Scroll further: Round-up history with timeline visualization, (4) Bottom: Quick actions (add goal, modify rules, view stats). This narrative scroll pattern engages members more effectively than a static dashboard and creates natural discovery of additional features.
One-Handed Goal Setting. Goal creation on mobile must be operable with one hand: select a template (two taps), set target amount (slider or numeric keypad), name goal (optional — default to template name), and confirm (one tap). The entire flow should take under 15 seconds and never require the member to switch to landscape orientation or use both hands.
Offline Grace. Mobile savings features should work gracefully even with intermittent connectivity. Goal progress should update optimistically (show the updated state immediately and sync when connected). Round-up notifications should queue and display when the member next opens the app. The savings feature should never feel broken or slow, even on unreliable mobile connections.
Cross-Device Continuity. Members frequently start their savings journey on mobile and review on desktop (or vice versa). Ensure seamless cross-device continuity: goals created on mobile appear instantly on desktop, round-up history is synchronized, and notification preferences are consistent across platforms. The savings experience should feel like a single, coherent system regardless of access point.
Mobile-First Accessibility. All mobile savings features must meet WCAG 2.2 AA standards for touch target size (minimum 44x44 CSS pixels), color contrast (minimum 4.5:1 for text), screen reader compatibility (proper ARIA labels for progress rings and charts), and motion sensitivity (settings to reduce animations for members with vestibular disorders). Mobile accessibility is particularly important for savings features, which disproportionately benefit lower-income and older members — demographics that also have higher rates of mobile accessibility needs.
Accessibility and Inclusive Design for Savings Tools
Credit unions serve a uniquely diverse membership base, including older adults, members with disabilities, limited English proficiency members, and members with varying digital literacy levels. Automated savings features must be designed for universal inclusion:
Cognitive Accessibility. Simplify savings concepts for members with limited financial literacy. Avoid jargon like "APY," "compounding," and "liquidity." Instead use plain language: "Your savings earn money while they sit in your account," "Your savings help you save even faster over time," and "You can access your money anytime." Provide a simple "How It Works" explainer page with illustrations and optional audio narration. The FDIC's research on financial literacy shows that simplified savings communications increase understanding and action by 40 percent among lower-literacy populations.[23]
Language Accessibility. Offer automated savings features in the member's preferred language. The credit union's membership demographics should determine which languages to support, with Spanish being the most common second language for credit unions serving Hispanic communities. All savings communications — enrollment, notification, goal naming, progress reports — must be fully translated, not machine-translated, to avoid confusion about financial terms. The CFPB's research on Limited English Proficiency consumers confirms that language-accessible financial tools significantly increase engagement and trust.[24]
Low-Vision and Screen Reader Compatibility. Progress visualizations must have text-based alternatives for screen reader users. "Your Emergency Fund goal is 73 percent complete. You have saved $1,460 of your $2,000 target. At your current savings rate, you will reach your goal in approximately 4 months." All interactive elements (buttons, sliders, toggles) must have proper ARIA labels and keyboard navigation. The savings dashboard must be fully navigable using keyboard-only input for members with motor disabilities.
Deaf and Hard of Hearing Accessibility. Any video or audio content about automated savings features must include closed captions. Achievement celebrations that use sound effects must also provide visual feedback (animations, banners). Notification preferences must include options for SMS and email, not just push notifications, to accommodate members who cannot hear audible alerts.
Digital Literacy Accommodations. For members with limited digital literacy, provide a guided enrollment option that can be completed with the assistance of a credit union employee. This "co-browsing" or assisted enrollment flow should exactly mirror the self-service digital flow but with a staff member walking the member through each step. Filene Research Institute found that assisted digital enrollment produces 3x higher completion rates for members over 65 compared to unassisted digital enrollment.[18]
Economic Accessibility. Automated savings features must be designed to serve members at every income level. Minimum round-up amounts should be $0.01 (no minimum threshold that excludes small purchases). Percentage-based savings options should offer 1 percent increments, allowing members to start with tiny amounts. Credit unions should offer a "Micro-Saver" tier with no minimum balance requirement and no monthly fees specifically designed for members who have never saved before. The most powerful impact of automated savings is often on the lowest-income members — and feature design must reflect this priority.
Core Deposit Growth Strategy: How Automated Savings Drive Balance Accumulation
From a credit union's balance sheet perspective, automated savings programs represent a powerful, cost-effective deposit growth engine:
Behavioral Deposit Accumulation. The average automated savings member accumulates deposits at 2.5-4x the rate of non-enrolled members, based on industry benchmarks. A typical enrolled member saves $50-100 per month through round-ups, percentage transfers, and goal-based savings. Over 12 months, this generates $600-1,200 in new core deposits per enrolled member — without the credit union paying premium rates or running expensive promotional campaigns. For a mid-sized credit union with 50,000 members and 30 percent automated savings enrollment (15,000 enrolled members), this translates to $9-18 million in annual net new deposit growth from the program alone.
Reduced Deposit Attrition. Members with automated savings features active have measurably lower attrition rates. The "stickiness" of linked savings accounts — where automated rules, goals, and progress are established — creates switching costs that reduce member churn. Credit unions with automated savings programs report 15-25 percent lower annual member attrition rates for enrolled members compared to non-enrolled members. Given that acquiring a new member costs $200-400 while retaining an existing member costs $10-50, the retention impact alone can generate substantial ROI.
Asset-Liability Management Benefits. Core deposits from automated savings programs tend to be "sticky" — members are reluctant to withdraw funds from a goal-linked savings account, particularly when doing so would reset progress visualizations or require re-setting automated rules. This stickiness creates a more stable, predictable deposit base that supports the credit union's asset-liability management strategy. Stable core deposits reduce the credit union's reliance on more expensive wholesale funding sources and improve net interest margin.
Cross-Sell Platform. A well-designed automated savings program serves as a powerful cross-sell platform. Members who successfully reach savings goals are excellent candidates for related products: Emergency Fund completion → credit card offer (for members now demonstrating financial readiness), Vacation Goal completion → travel rewards card or vacation loan, Home Down Payment completion → mortgage pre-approval. The savings program provides both the behavioral signal (member capacity to save) and the relationship context for cross-sell offers that feel helpful rather than pushy.
Generational Deposit Strategy. Automated savings is particularly effective for attracting and retaining younger members — the critical demographic for credit union long-term sustainability. Gen Z and Millennial members consistently rank "automatic savings tools" among the top three features they want from a financial institution, and credit unions with strong automated savings offerings report 40 percent higher account opening rates among the under-35 demographic. By building the savings habit early, credit unions secure decades of primary financial relationship value from each young member acquired.
Community Impact Metrics. Automated savings programs generate compelling community impact data that credit unions can use in marketing, regulatory reporting, and mission-driven communications. "Our members saved $24 million automatically this year" makes a powerful statement about the credit union's commitment to member financial wellness. Track and report aggregate savings data publicly: total automated savings generated, number of goals achieved, average savings per enrolled member, and the demographic distribution of program benefits.
Regulatory Compliance and Risk Considerations for Automated Savings
Automated savings features, while generally low-risk, require attention to several regulatory and compliance considerations:
Regulation E and Error Resolution. Automated savings transfers are covered under Regulation E's error resolution requirements. Members must have a clear process for disputing round-up transfers and receiving timely resolution. Provide a "Report an Issue" link on every savings transaction, visible in both the activity feed and the savings dashboard. The error resolution process should be simple and member-friendly, with the credit union proactively investigating and correcting errors rather than requiring the member to navigate a complex dispute process.
Truth in Savings Act (TISA). All promotional materials and enrollment flows for automated savings must clearly disclose the savings APY, minimum balance requirements, fee structures, and the terms under which automated transfers can be modified or canceled by the credit union. Disclosures must be in plain language and conspicuously displayed — not buried in fine print. The CFPB's 2025 updates to TISA implementation rules specifically address digital disclosure requirements for automated features.[25]
Overdraft and Funds Availability. Credit unions must ensure that automated savings transfers do not cause members to overdraw their checking accounts. Implement the "savings smoothing" feature described earlier as a default — automatically pausing transfers when the checking account balance falls below a threshold. In addition, clearly communicate to members that automated savings transfers are subject to standard funds availability holds and that savings account withdrawals may be limited to six per month under Regulation D (if still applicable, depending on current regulatory status).
UDAAP Compliance. The CFPB's Unfair, Deceptive, or Abusive Acts or Practices (UDAAP) authority applies to automated savings features. Avoid any practices that could be considered deceptive: (1) Do not automatically enroll members without affirmative consent; (2) Do not make it unreasonably difficult to cancel or modify savings rules; (3) Do not obscure the total amount being saved across all automated rules; (4) Do not use confusing language or hide fee disclosures. The CFPB has indicated particular scrutiny of "dark pattern" design that manipulates consumers into financial behaviors they did not clearly intend.[26]
BSA/AML and OFAC Screening. While automated savings features generally present low money laundering risk, the opening and funding of savings accounts through automated transfers must be subject to standard BSA/AML and OFAC screening. Unusual savings patterns — rapid accumulation followed by withdrawal, transfers from high-risk jurisdictions, sudden changes in automated savings behavior — should trigger appropriate monitoring alerts. The credit union's BSA officer should review automated savings program design to ensure adequate controls are in place.
Privacy and Data Usage. Automated savings features generate behavioral data about member spending and saving patterns. This data is valuable for product improvement and personalization but must be handled with appropriate privacy protections. Implement clear data usage policies, obtain member consent for data analysis, and ensure compliance with GLBA privacy requirements and state-level privacy laws (CCPA, etc.). Never sell or share individual member savings behavior data with third parties without explicit, informed consent.
Core System Integration and Technology Architecture
Implementing automated savings features requires thoughtful integration with the credit union's technology stack:
Core Processor Integration. The most critical integration is with the credit union's core processing system for real-time transfer execution. Most modern cores support automated transfer initiation via API or batch file processing. Key integration points: (1) Real-time or same-day ACH transfer capability between checking and savings accounts; (2) Debit card transaction data access for round-up calculation; (3) Direct deposit event detection for percentage-based transfer triggers; (4) Balance inquiry APIs for overdraft protection and savings smoothing logic; (5) Account opening and closure event feeds for lifecycle management.
Transaction Capture and Round-Up Calculation Engine. Implement a round-up calculation engine that processes debit card transactions in real-time or batch to determine round-up amounts. The engine must handle edge cases: transactions already rounded to exact dollars ($5.00 trigger no round-up), credit transactions (should not trigger round-up), reversals and chargebacks (must reverse corresponding round-up), and international transactions (currency conversion complexity). The engine should produce a daily round-up batch file that is then executed as a series of transfers and posted to member accounts.
Digital Banking Platform Integration. The automated savings user interface will typically live within the credit union's digital banking platform (online banking and mobile app). Integration requirements: (1) Savings dashboard display with progress visualizations; (2) Enrollment and configuration flows; (3) Goal management interface; (4) Rule creation and modification; (5) Notification and communication triggers; (6) Analytics and reporting dashboard for credit union staff. Many digital banking platforms (Q2, NCR Digital Insight, Fiserv, Jack Henry Banno) offer automated savings modules or APIs that reduce custom development needs.
Notification and Communication Engine. The automated savings system must integrate with the credit union's existing notification and communication infrastructure: push notifications (mobile app), SMS, email, and in-app messaging. Each notification type requires its own template, content strategy, and opt-in/opt-out management. The notification engine should track delivery, open rates, and conversion for each communication type to enable continuous optimization.
Data Analytics and Reporting. Implement a comprehensive analytics layer that tracks: (1) Program-level metrics (total savings, enrollment rate, active rate, retention rate), (2) Member-level metrics (savings rate, goal completion, rule utilization), (3) Behavioral segmentation (which member profiles use which features), (4) Deposit growth attribution (net new deposits from automated savings), (5) A/B testing infrastructure for feature optimization. Data should flow to a dashboard that both credit union leadership and product teams can access.
Security Architecture. Automated savings features involve the movement of member funds and must be protected accordingly: (1) Multi-factor authentication for enrollment and rule changes; (2) Encryption of all PII and financial data in transit and at rest; (3) Rate limiting to prevent abuse or gaming of round-up programs; (4) Fraud detection algorithms to identify suspicious savings patterns; (5) Comprehensive audit logging of all administrative actions. The security architecture should be reviewed by the credit union's information security officer before launch.
Measurement Framework and KPIs for Savings Feature Success
Measuring the success of automated savings features requires a balanced scorecard approach that tracks member outcomes, business impact, and program health:
Member Outcome Metrics (Primary). (1) Total automated savings generated: aggregate dollar amount saved through all automated features, (2) Average savings per enrolled member: mean annual automated savings, segmented by demographic and income, (3) Goal completion rate: percentage of members who achieve at least one savings goal within 12 months of enrollment, (4) Savings balance increase: net increase in savings account balance, controlling for transfers out, (5) Financial health score improvement: pre/post comparison using a standardized financial health assessment (e.g., Financial Health Network's FinHealth Score).
Engagement Metrics (Secondary). (1) Enrollment rate: percentage of eligible members who activate any automated savings feature, (2) Feature activation rate: percentage of enrolled members using each feature type (round-up, percentage, scheduled, goal), (3) Active rate: percentage of enrolled members with at least one automated savings event in the past 30 days, (4) Retention rate: percentage of enrolled members still active at 3, 6, and 12 months post-enrollment, (5) Feature stickiness: average number of features used per active member.
Business Impact Metrics (Tertiary). (1) Net new deposit growth: deposits directly attributable to automated savings program, (2) Deposit cost comparison: cost of deposits acquired through automated savings vs. promotional rates or marketing campaigns, (3) Member retention improvement: reduction in attrition rate for enrolled vs. non-enrolled members, (4) Cross-sell conversion rate: percentage of goal completions that convert to related product applications, (5) Program ROI: net deposit growth value minus program costs (development, ongoing operations, incentive costs).
Program Health Metrics (Operational). (1) Transfer error rate: percentage of automated transfers that fail due to system errors (target: under 0.1 percent), (2) Overdraft incident rate: percentage of automated transfers that cause or contribute to an overdraft event (target: under 0.01 percent), (3) Support contact rate: percentage of enrolled members contacting support about automated savings (target: under 2 percent per month), (4) Complaint resolution time: average time to resolve member complaints about automated savings (target: under 24 hours), (5) Feature uptime: percentage of time automated savings features are fully functional (target: 99.9 percent or higher).
Establish baseline measurements for each KPI before launch and track monthly against targets. Conduct quarterly program reviews to identify improvement opportunities and adjust strategy. Share aggregate member outcome metrics transparently with the credit union's board, membership, and community to demonstrate the program's mission impact.
Implementation Roadmap: 90-Day Automated Savings Launch Plan
Launching automated savings features can be accomplished within 90 days using a phased implementation approach:
Days 1-30: Foundation and Core Integration (Phase 1). (1) Assess core processor capabilities for automated transfer execution; (2) Select and scope digital banking platform module or custom development; (3) Design round-up calculation engine architecture; (4) Define data requirements and integration points for transaction capture; (5) Develop initial UX wireframes for enrollment flow and savings dashboard; (6) Establish measurement baseline and configure analytics tracking; (7) Begin core integration development (API connections, batch processing, error handling).
Days 31-60: Build and Internal Testing (Phase 2). (1) Complete core integration development and unit testing; (2) Build round-up calculation engine and test with historical transaction data; (3) Develop enrollment flow, savings dashboard, and goal management interfaces; (4) Implement notification engine and configure communication templates; (5) Conduct internal QA testing across all features and edge cases; (6) Perform security review and vulnerability assessment; (7) Begin staff training program for member-facing employees; (8) Develop launch marketing materials and member communication plan.
Days 61-75: Beta Testing and Refinement (Phase 3). (1) Launch beta program with 50-100 employee and board member volunteers; (2) Collect beta feedback through surveys and usage analytics; (3) Fix bugs and refine UX based on beta learnings; (4) Validate round-up calculation accuracy against control transactions; (5) Test notification delivery and member response rates; (6) Finalize measurement dashboard and reporting cadence; (7) Complete staff training and certification.
Days 76-90: Launch and Optimization (Phase 4). (1) Soft launch to 5 percent of membership with targeted email campaign; (2) Monitor enrollment rates, transfer accuracy, and support contacts for 5-7 days; (3) Conduct post-launch review and address any issues; (4) Full launch to entire membership with multichannel campaign; (5) Launch employee advocacy program with branch-level enrollment goals; (6) Begin daily monitoring of all KPIs; (7) Schedule post-launch review at Day 45 for Phase 2 feature prioritization.
Post-Launch Roadmap (Days 91-180). (1) Launch goal-based savings features (if not included in MVP); (2) Implement notification optimization and A/B testing; (3) Launch windfall capture and subscription savings capture features; (4) Develop and deploy mobile-first interface refinements; (5) Launch internally-focused employee leaderboard and gamification program; (6) Begin quarterly program review cadence; (7) Plan savings matching program (credit union matches round-ups) for next fiscal year.
This phased approach minimizes implementation risk while delivering value to members as quickly as possible. Credit unions with limited development resources can accelerate the timeline by selecting a digital banking platform with pre-built automated savings modules, reducing custom development requirements to configuration and integration only.
Future Trends: AI-Optimized Savings, Embedded Behavioral Nudges, and Predictive Saving
The automated savings landscape continues to evolve rapidly. Credit unions designing features today should anticipate several emerging trends that will shape the next generation of automated savings tools:
AI-Optimized Savings Amounts. Rather than requiring members to choose their savings rate, AI-powered systems will analyze each member's cash flow patterns, seasonal spending variations, savings capacity, and financial goals to dynamically determine the optimal savings amount. These "intelligent savings engines" adjust transfer amounts up or down based on the member's real-time financial situation — saving more during surplus months and reducing or pausing during higher-spending periods. Early implementations from fintechs like Albert and Digit have shown that AI-optimized savings generates 25-40 percent higher annual savings than fixed-rule approaches.[27]
Predictive Life Event Savings. AI systems will increasingly predict major life events — car repairs, medical expenses, tax payments, holiday spending — and automatically adjust savings targets to prepare. A member whose car is 8 years old might receive: "Members with vehicles over 7 years old typically face a $500-2,000 repair expense within the next 12 months. We've created a 'Car Repair Fund' goal based on your vehicle's age and make. Tap to accept or modify the suggested target." Predictive savings transforms automated savings from a post-hoc accumulation tool into an anticipatory financial planning system.
Embedded Savings in Digital Commerce. Savings features will integrate directly into the member's digital commerce experience. When checking out on an e-commerce site using a credit union debit card, a prompt appears: "Round up your purchase to save for your Vacation goal? You just saved $0.47 toward Hawaii." This embedded savings pattern — bringing automated savings into the moment of spending — dramatically increases round-up capture rates and makes savings a seamless part of everyday financial life.
Open Banking and Account Aggregation for Comprehensive Savings. As open banking adoption grows, credit union automated savings features could extend to analyze the member's entire financial picture — including accounts at other institutions — to optimize savings recommendations. A member who has $10,000 in a checking account at another bank might receive: "We see you have funds held outside the credit union. Would you like to set up an automatic transfer to your credit union savings account to earn 2.5 percent APY instead of the 0.01 percent you're currently earning?" This comprehensive view transforms automated savings from a within-institution feature to an across-institution financial wellness tool.
Behavioral Nudge Networks. Future automated savings systems will coordinate multiple behavioral nudges across channels and over time. A single savings goal might be supported by: in-app round-up prompts, SMS goal progress check-ins, email behavioral education content, mobile push notifications for milestone celebrations, ATM screen plugs for savings enrollment, branch teller verbal encouragement, and direct mail goal celebration cards. This coordinated multichannel nudge network creates persistent, consistent behavioral reinforcement that dramatically increases savings outcomes.
Generative AI Financial Coaching. Generative AI will power personalized financial coaching conversations about savings: "Sarah, I notice you paused your automated savings last week. Is everything okay? Would you like to adjust your savings target or take a 30-day pause?" These AI coaching conversations, grounded in the member's actual financial behavior and expressed preferences, provide a scalable supplement to human financial counseling — extending the credit union's financial wellness mission to every member, not just those who walk through the branch doors.
Cryptocurrency and Alternative Savings Vaults. As younger members increasingly express interest in alternative savings vehicles, credit union automated savings features may expand to include optional allocation to high-yield savings, certificates of deposit, ESG investment funds, or even regulated cryptocurrency savings vaults. The core UX pattern — automate, accumulate, visualize — remains the same regardless of where the saved funds are held, but offering choice in savings destination can appeal to a broader range of member preferences.
Conclusion: Building the Savings Habit as a Digital Banking Superpower
Automated savings features represent one of the highest-impact, lowest-cost digital banking investments a credit union can make. The behavioral economics are compelling: automatic enrollment and round-up programs consistently increase member savings by $600-1,200 per year, drive 2.5-4x higher core deposit accumulation, and reduce member attrition by 15-25 percent. For a typical mid-sized credit union, a well-designed automated savings program can generate $10-20 million in net new deposits within two years while transforming the financial wellness of thousands of members.
Yet the true power of automated savings extends beyond the balance sheet. Every member who builds a sustainable savings habit gains a foundation of financial stability that ripples through every aspect of their life: fewer overdrafts, better credit scores, reduced financial stress, greater resilience against emergencies, and increased confidence in their financial future. Credit unions, as member-owned cooperatives with a mission-driven charter, are uniquely positioned to deliver this life-changing benefit — not as a profit center, but as a fulfillment of their core purpose.
The credit unions that move quickly to implement sophisticated automated savings features will not only grow their deposit base but will deepen their relationships with members, differentiate themselves from megabanks and fintechs, and demonstrate their commitment to member financial well-being in tangible, measurable ways. Those that delay risk losing members to the growing ecosystem of fintech apps that have already made automated savings their primary value proposition.
Designing an excellent automated savings experience requires attention to behavioral psychology, mobile-first UX, accessibility, integration architecture, and regulatory compliance — all detailed in this playbook. But the most important design principle is the simplest one: make saving so easy that members save without thinking about it. When automated savings works perfectly, members never notice the transfers, never need to make a decision, and never have to exercise willpower. They simply wake up one day to discover that they have thousands of dollars in savings they never knew they were missing. That discovery — the delightful surprise of carefree accumulation — is the magical moment that transforms a member's relationship with their credit union and with their own financial potential.
This article was brought to you by GrafWeb CUSO – Building the future of digital credit unions.
References
- Federal Reserve, Report on the Economic Well-Being of U.S. Households, 2025
- NCUA, Credit Union Corporate Call Report Data, Year-End 2025
- Thaler & Benartzi, "Save More Tomorrow: Using Behavioral Economics to Increase Employee Savings," Journal of Political Economy, 2004
- Bank of America, "Keep the Change Program: 10-Year Results," 2015
- Behavioral Insights Team, "EAST: Four Simple Ways to Apply Behavioural Insights," 2014
- Nature Neuroscience, "Neural Correlates of Automated Savings Decisions," 2020
- Harvard Business Review, "How to Build Savings Habits That Stick," 2022
- CFPB, "Financial Well-Being in America," 2024
- Harvard Kennedy School & ideas42, "Credit Union Automated Savings Program Impact Study," 2024
- Chime, "Save When I Get Paid: Program Analysis," 2025
- Acorns, "Company Overview and Impact Statistics," 2025
- Digital Federal Credit Union, "Save on Autopilot Program," 2025
- Q2, "QBIC Innovation Lab: Automated Savings Reference Architecture," 2025
- Credit Union National Association, "2025 Technology Survey," 2025
- CFPB, "Simpler, Save More for Retirement," 2020
- Journal of Behavioral Decision Making, "Perceived Control in Automated Financial Systems," 2023
- Digit, "Behavioral Savings Research: Member Engagement Analysis," 2024
- Filene Research Institute, "Savings Challenges: Time-Limited Behavioral Interventions for Credit Union Members," 2025
- Cornerstone Advisors, "What Consumers Want From Digital Banking," 2025
- Internal Revenue Service, "2025 Tax Refund Statistics," 2026
- Financial Health Network, "Savings Program Design: Best Practices for Financial Institutions," 2024
- Behavioral Scientist, "Trigger Moments: When to Nudge Members to Save," 2024
- FDIC, "Financial Literacy Research and Resources," 2025
- CFPB, "Limited English Proficiency and Financial Services," 2023
- CFPB, "Truth in Savings Act Implementation Rules," 2025
- CFPB, "Unfair, Deceptive, or Abusive Acts or Practices (UDAAP)," 2025
- Albert, "AI-Optimized Savings: Member Outcomes Research," 2025
Request a proposal from GrafWebCUSO · (201) 632-1771 · [email protected]